
Company Coverage
City Developments (CIT SP): Resilient Operating Performance
BUY (Maintained)
Current price:
Target price:
Upside:
S$7.12
S$11.85
66.4%
Analyst
Highlights
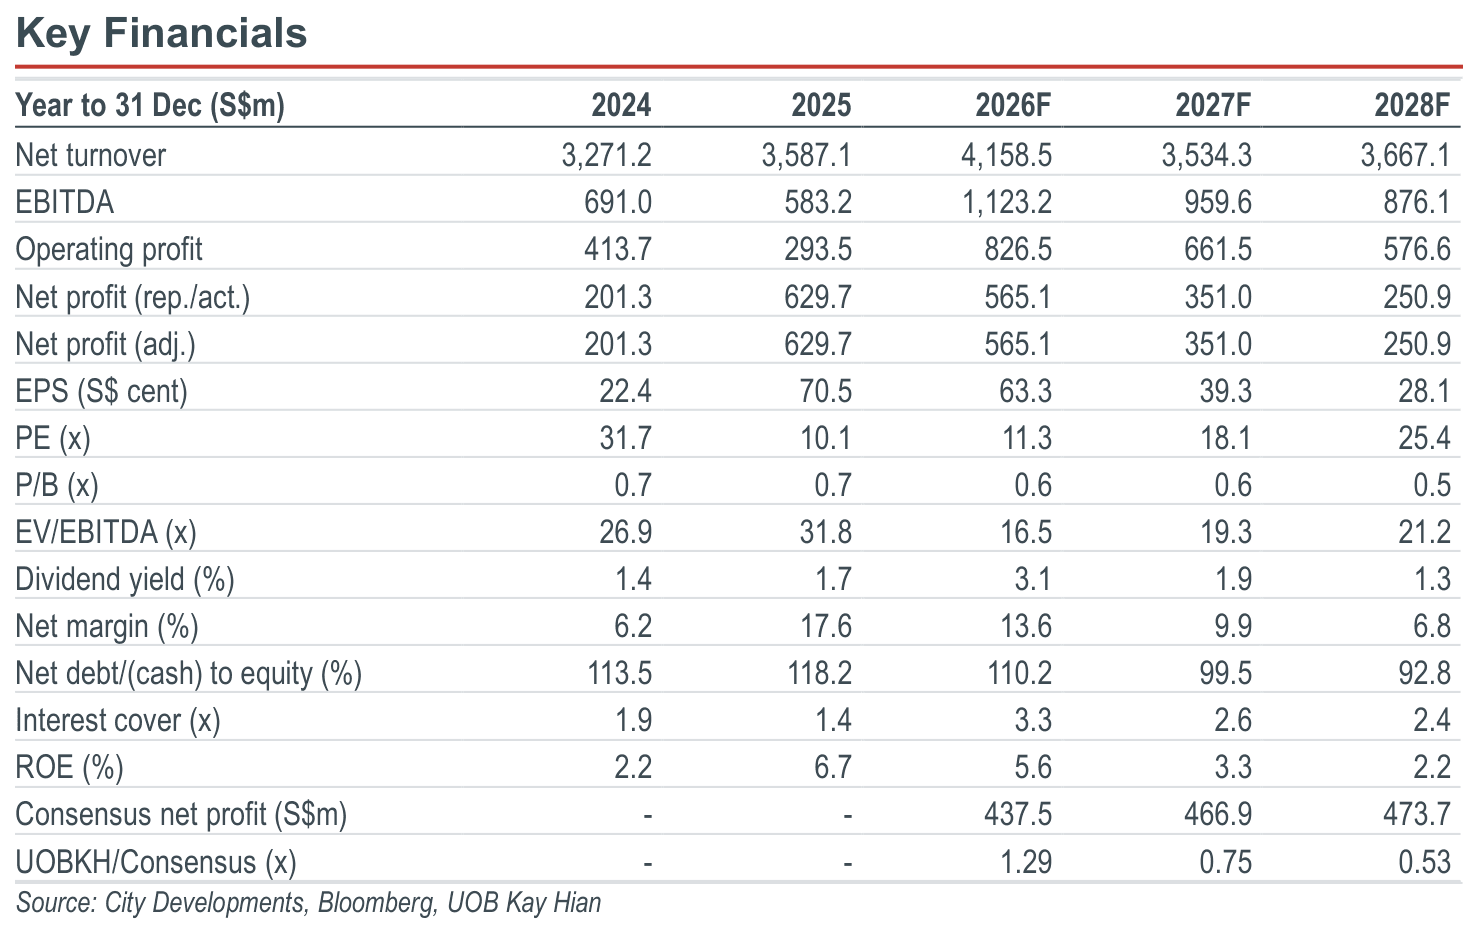
- Business as usual. In its 3Q26 operational update, CIT reported stable residential sales value yoy while its investment property portfolio enjoyed higher occupancy amid positive rental reversion. Its hospitality segment saw an improved 6.4% growth in portfolio RevPAR. Gearing stayed stable qoq at 75% as at end-3Q26.
- Guiding for 2H26 to be weaker yoy. Although this does not come as a surprise given the very high base of PATMI in 2H25 (due mainly to divestment gains from South Beach), CIT alerted that forex losses on its SGD-denominated intercompany loan receivable due to the strengthening of Korean won vs S$ could drag on earnings while year-end property valuations may result in impairment losses.
- Capital recycling transactions delayed to 2027. CIT updated that under the current challenging market conditions, certain capital recycling transactions originally envisaged for the remainder for 2026 are now expected to complete in 2027 instead. Nonetheless, CIT remains committed to executing its strategic objectives to: a) unlock embedded value through S$6b of divestments, and b) strengthen its financial position by lowering gearing to 55% by 2029.
- Maintain BUY with a target price of S$11.85.
Analysis
- Reported S$322.6m residential sales in 3Q26, bringing 9M26 sales to around S$1.2b. While 3Q26 sales value was slightly ahead of 3Q25’s level, the 9M26 sales value was below the S$2.5b recorded for 9M25. After 3Q26, there has been a continued increase in take-up rates at Lucerne Grand (73% sold) and Union Square Residences (80% sold), while Canning Hill Piers obtained TOP.
- 730 new units to be launched in 1Q27. City Developments (CIT) is scheduled to roll out two executive condominium (EC) projects in 1Q27 – 430-unit Wynwood Grand in Woodlands and 300-unit Solano Grand at Senja Close. We expect these two developments to be well received as both sites were acquired under the previous EC framework.
Highlights
- Business as usual. In its 3Q26 operational update, CIT reported stable residential sales value yoy while its investment property portfolio enjoyed higher occupancy amid positive rental reversion. Its hospitality segment saw an improved 6.4% growth in portfolio RevPAR. Gearing stayed stable qoq at 75% as at end-3Q26.
- Guiding for 2H26 to be weaker yoy. Although this does not come as a surprise given the very high base of PATMI in 2H25 (due mainly to divestment gains from South Beach), CIT alerted that forex losses on its SGD-denominated intercompany loan receivable due to the strengthening of Korean won vs S$ could drag on earnings while year-end property valuations may result in impairment losses.
- Capital recycling transactions delayed to 2027. CIT updated that under the current challenging market conditions, certain capital recycling transactions originally envisaged for the remainder for 2026 are now expected to complete in 2027 instead. Nonetheless, CIT remains committed to executing its strategic objectives to: a) unlock embedded value through S$6b of divestments, and b) strengthen its financial position by lowering gearing to 55% by 2029.
- Maintain BUY with a target price of S$11.85.
Analysis
- Reported S$322.6m residential sales in 3Q26, bringing 9M26 sales to around S$1.2b. While 3Q26 sales value was slightly ahead of 3Q25’s level, the 9M26 sales value was below the S$2.5b recorded for 9M25. After 3Q26, there has been a continued increase in take-up rates at Lucerne Grand (73% sold) and Union Square Residences (80% sold), while Canning Hill Piers obtained TOP.
- 730 new units to be launched in 1Q27. City Developments (CIT) is scheduled to roll out two executive condominium (EC) projects in 1Q27 – 430-unit Wynwood Grand in Woodlands and 300-unit Solano Grand at Senja Close. We expect these two developments to be well received as both sites were acquired under the previous EC framework.
BUY (Maintained)
Current price:
Target price:
Upside:
S$7.12
S$11.85
66.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Sept 2026
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy

25 Sept 2026
Wilmar International (WIL SP): Integrated Business Model To Navigate The Challenging Operating Environment

30 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): 3Q26: Uptick For Office Occupancy; Firmer Reversion For Retail
Our latest research

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

12 Nov 2026
Yangzijiang Shipbuilding (YZJSGD SP): Strong New Contract Wins Bring Orderbook To A New Record-high Level, Extending Earnings Visibility Through 2030

12 Nov 2026