
Company Coverage
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.86
S$1.30
51.0%
S$1.79
Analyst
Analyst
Highlights
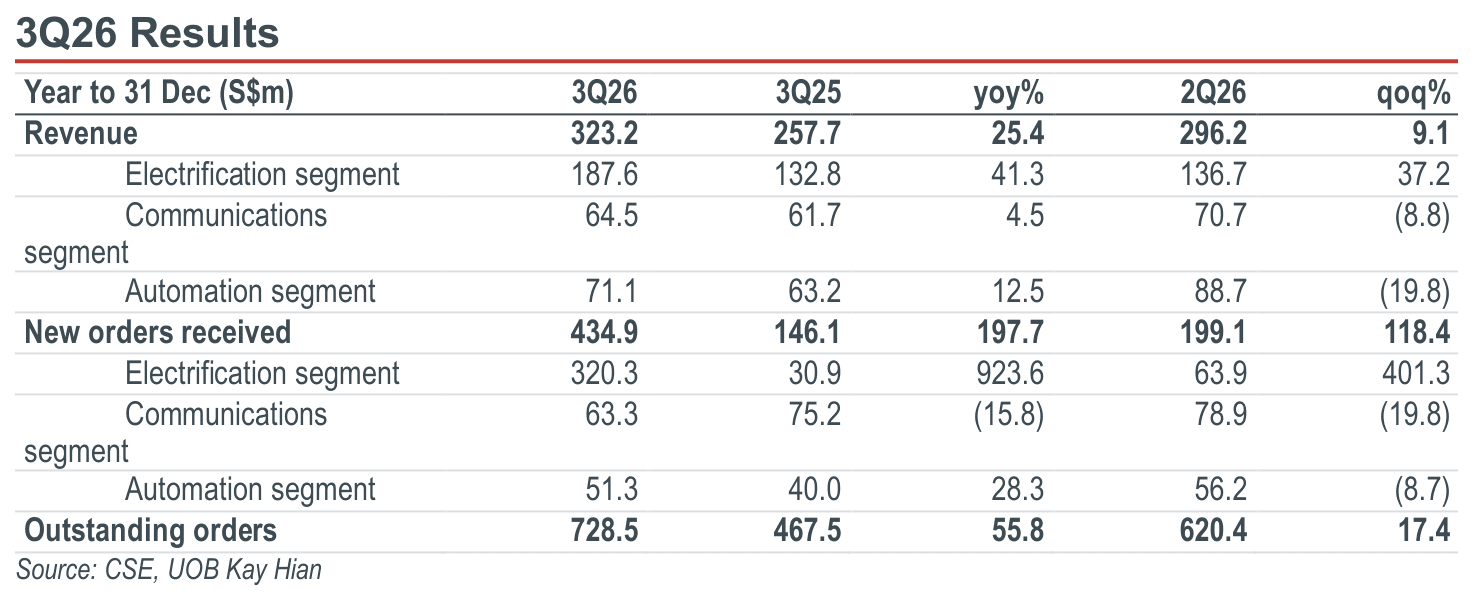
- 9M26 revenue grew 26.6% yoy to S$884.6m, forming 78.6% of our 2026 forecast, driven by strong US electrification demand.
- 3Q26 order intake surged 197.7% yoy to S$434.9m, lifting the orderbook to S$728.5m, with a healthy project pipeline supporting future growth.
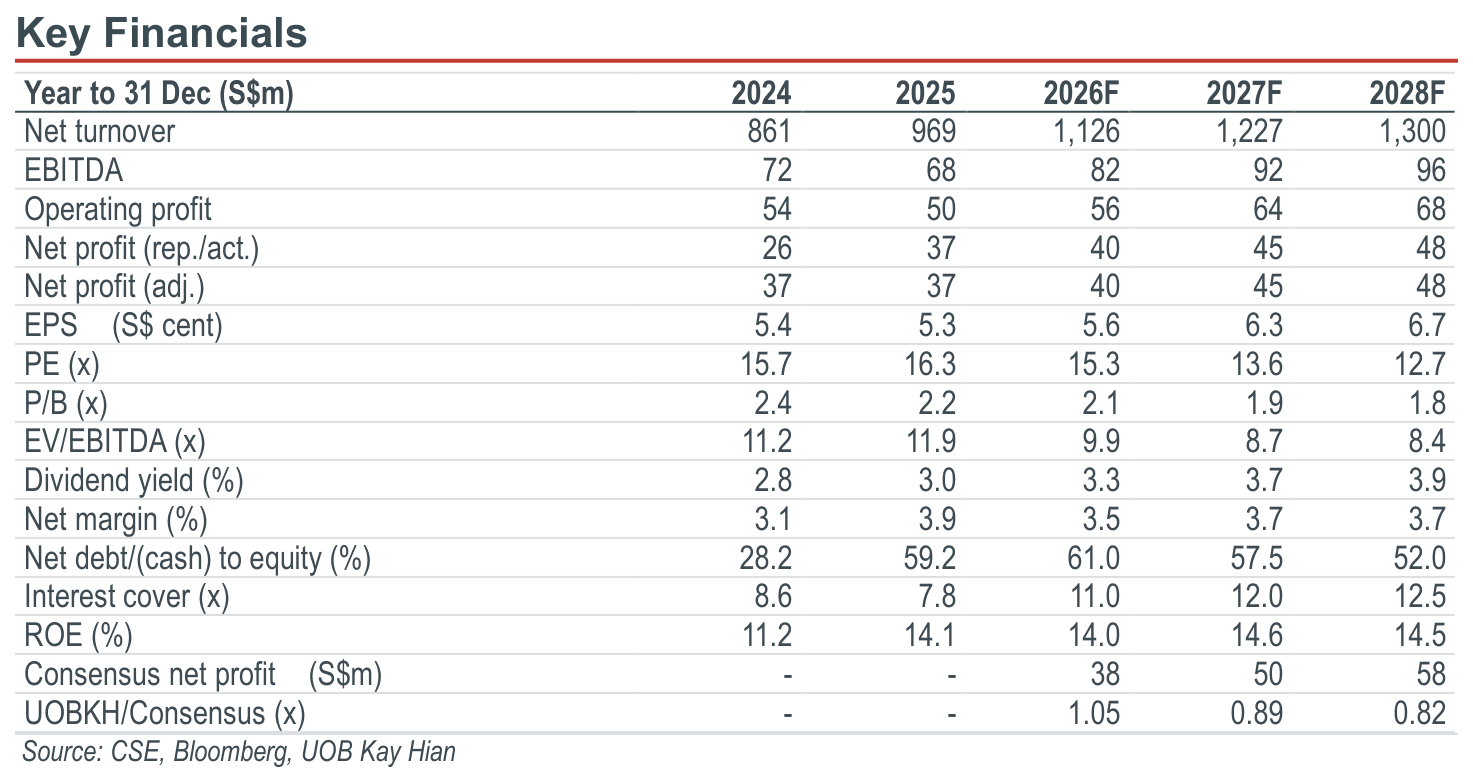
- Maintain BUY with a 27% lower target price of S$1.30, based on 21x 2027F PE (+1SD). Margin recovery is expected for 2H26 as capacity utilisation ramps up.
Analysis
- Revenue in line, driven by strong Electrification performance. CSE Global (CSE) reported 3Q26 revenue of S$323.2m (+25.4% yoy, +9.1% qoq), bringing 9M26 revenue to S$884.6m (+26.6% yoy), or 78.6% of our 2026 forecast. Electrification remained the key driver, with revenue rising 41.2% yoy to S$187.6m (58.1% of group revenue), supported by major US data centre projects. Communications revenue grew 4.5% yoy to S$64.5m on stronger Australia and New Zealand contributions, while Automation revenue rose 12.4% yoy to S$71.1m on higher Americas project revenue.
- Strong order intake drives orderbook growth. CSE's 3Q26 order intake surged 197.7% yoy and 118.4% qoq to S$434.9m, driven by strong US electrification demand. Electrification orders jumped 937.0% yoy to S$320.3m, accounting for 73.6% of new orders. Notable wins include the Cheyenne Power Hub and CP2 LNG projects, worth S$254.8m, with execution expected over 2026-28. 9M26 order intake rose 76.5% yoy to S$905.1m, while the outstanding orderbook grew 55.8% yoy to S$728.5m. Continued opportunities in hyperscale data centres, LNG and power infrastructure, supported by AWS-related projects, provide strong revenue visibility.
Highlights
- 9M26 revenue grew 26.6% yoy to S$884.6m, forming 78.6% of our 2026 forecast, driven by strong US electrification demand.
- 3Q26 order intake surged 197.7% yoy to S$434.9m, lifting the orderbook to S$728.5m, with a healthy project pipeline supporting future growth.
- Maintain BUY with a 27% lower target price of S$1.30, based on 21x 2027F PE (+1SD). Margin recovery is expected for 2H26 as capacity utilisation ramps up.
Analysis
- Revenue in line, driven by strong Electrification performance. CSE Global (CSE) reported 3Q26 revenue of S$323.2m (+25.4% yoy, +9.1% qoq), bringing 9M26 revenue to S$884.6m (+26.6% yoy), or 78.6% of our 2026 forecast. Electrification remained the key driver, with revenue rising 41.2% yoy to S$187.6m (58.1% of group revenue), supported by major US data centre projects. Communications revenue grew 4.5% yoy to S$64.5m on stronger Australia and New Zealand contributions, while Automation revenue rose 12.4% yoy to S$71.1m on higher Americas project revenue.
- Strong order intake drives orderbook growth. CSE's 3Q26 order intake surged 197.7% yoy and 118.4% qoq to S$434.9m, driven by strong US electrification demand. Electrification orders jumped 937.0% yoy to S$320.3m, accounting for 73.6% of new orders. Notable wins include the Cheyenne Power Hub and CP2 LNG projects, worth S$254.8m, with execution expected over 2026-28. 9M26 order intake rose 76.5% yoy to S$905.1m, while the outstanding orderbook grew 55.8% yoy to S$728.5m. Continued opportunities in hyperscale data centres, LNG and power infrastructure, supported by AWS-related projects, provide strong revenue visibility.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.86
S$1.30
51.0%
S$1.79
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q
Our latest research
16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q

16 Nov 2026
Singapore Technologies Engineering (STE SP): 3Q26: Revenue Broadly In Line; Expect Strong Closing For 2026 And Sustainable Healthy Growth In the Medium Term

16 Nov 2026