Company Coverage
EGP Energy Corporation (EGX SP): Investor Call Takeaways And Grid Expansion Opportunities
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.66
S$0.92
39.4%
Analyst
Analyst
Highlights
- We had a virtual call with EGP’s management, joined by 19 investor clients on 26 Oct 26 to discuss tenders, Malaysia expansion, margins and maintenance.
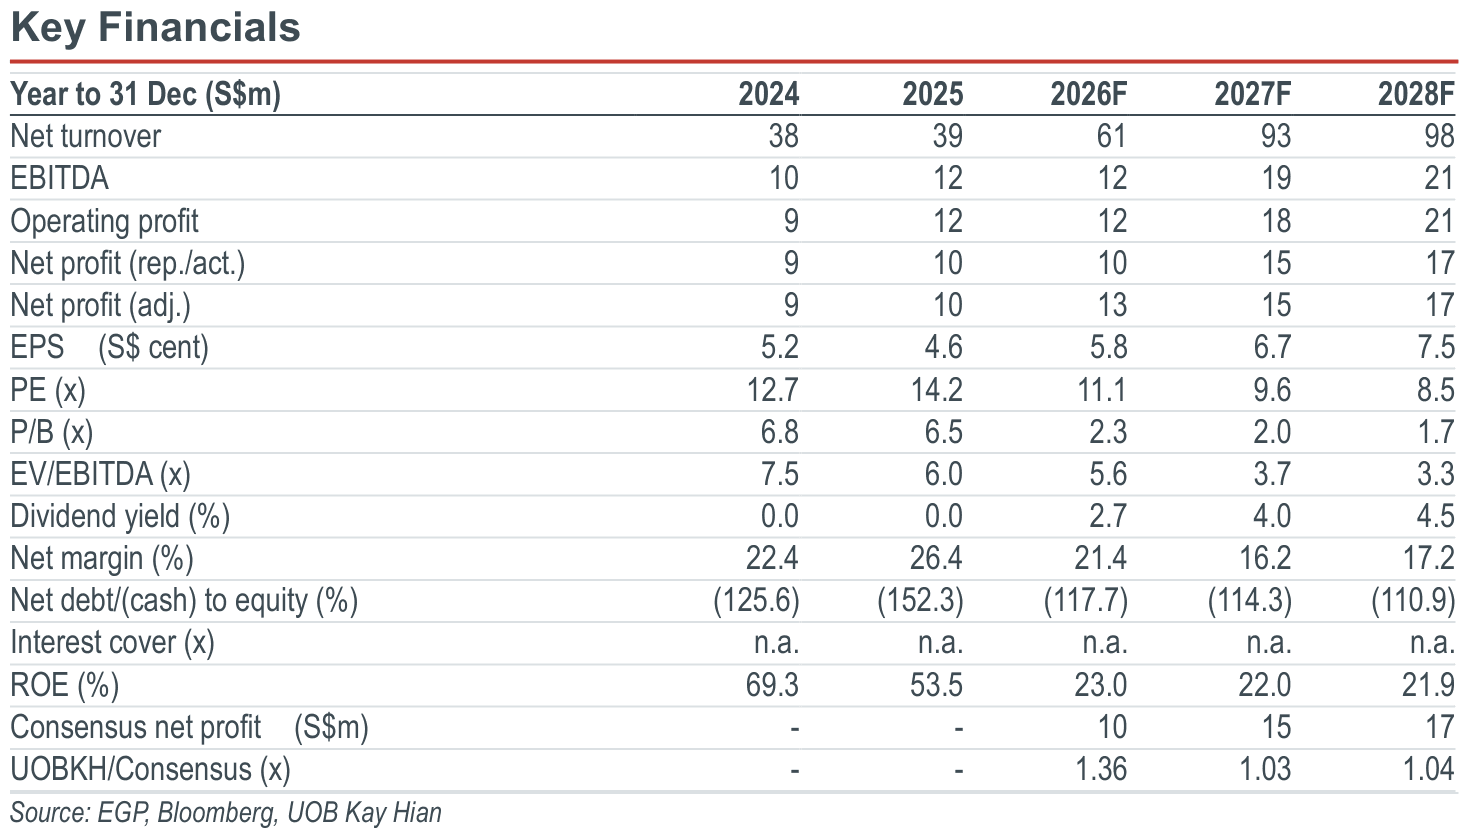
- Management reiterated its 2026 earnings guidance of S$11m-12m and 2027’s S$15m-16m, backed by an indicative S$300m Singapore orderbook.
- Maintain BUY with a target price of S$0.92, pegged to 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average.
Analysis
- Investor questions centred on earnings visibility. Clients asked about Singapore tender award dates, Malaysia’s first contract and revenue contribution, overseas margins, alongside 2026-27 guidance and the weaker implied second-half earnings. They also questioned whether maintenance income is recurring. We read these questions as a focus on clearer award timelines, sustainable margins and the conversion of backlog into earnings.
- Malaysia JV positions EGP for EHV substation work. EGP Energy Corporation (EGP) holds 60% of the JV with UUE Holdings’ subsidiary Kum Fatt Engineering, which brings a Malaysia’s Construction Industry Development Board (CIDB) G7 licence and local execution capability. The company continues to highlight that the JV would be targeting 132kV to 500kV substation projects, with Tenaga Nasional as the main focus alongside private sector work such as data centre intake substations. The first award is expected in 2027.
- Singapore orderbook provides visibility to 2031. Management indicated a current backlog of around S$300m, vs August’s S$296.2m, with contracts extending to 2031. Major substation tenders remain under negotiation, with validity to end-26 and possible 3-6-month extensions. Management attributed delays partly to changing grid priorities.
- Guidance intact. Management kept its earnings guidance unchanged, indicating NPAT of S$11m-12m for 2026 and S$15m-16m for 2027.
- M&S revenue stays stable as T&D grows faster. Discussions also centred around revenue mix and visibility. Management highlighted that maintenance and services (M&S) revenue is recurring and holds steady in absolute terms over each contract’s life. The smaller M&S share of 2026 revenue reflects faster transmission and distribution (T&D) growth, not weaker maintenance demand.
Highlights
- We had a virtual call with EGP’s management, joined by 19 investor clients on 26 Oct 26 to discuss tenders, Malaysia expansion, margins and maintenance.
- Management reiterated its 2026 earnings guidance of S$11m-12m and 2027’s S$15m-16m, backed by an indicative S$300m Singapore orderbook.
- Maintain BUY with a target price of S$0.92, pegged to 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average.
Analysis
- Investor questions centred on earnings visibility. Clients asked about Singapore tender award dates, Malaysia’s first contract and revenue contribution, overseas margins, alongside 2026-27 guidance and the weaker implied second-half earnings. They also questioned whether maintenance income is recurring. We read these questions as a focus on clearer award timelines, sustainable margins and the conversion of backlog into earnings.
- Malaysia JV positions EGP for EHV substation work. EGP Energy Corporation (EGP) holds 60% of the JV with UUE Holdings’ subsidiary Kum Fatt Engineering, which brings a Malaysia’s Construction Industry Development Board (CIDB) G7 licence and local execution capability. The company continues to highlight that the JV would be targeting 132kV to 500kV substation projects, with Tenaga Nasional as the main focus alongside private sector work such as data centre intake substations. The first award is expected in 2027.
- Singapore orderbook provides visibility to 2031. Management indicated a current backlog of around S$300m, vs August’s S$296.2m, with contracts extending to 2031. Major substation tenders remain under negotiation, with validity to end-26 and possible 3-6-month extensions. Management attributed delays partly to changing grid priorities.
- Guidance intact. Management kept its earnings guidance unchanged, indicating NPAT of S$11m-12m for 2026 and S$15m-16m for 2027.
- M&S revenue stays stable as T&D grows faster. Discussions also centred around revenue mix and visibility. Management highlighted that maintenance and services (M&S) revenue is recurring and holds steady in absolute terms over each contract’s life. The smaller M&S share of 2026 revenue reflects faster transmission and distribution (T&D) growth, not weaker maintenance demand.
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.66
S$0.92
39.4%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Oct 2026
CSE Global (CSE SP): Positive Highlights From Meeting Reinforce Growth Outlook

23 Sept 2026
Food Empire Holdings (FEH SP): Business As Usual In Russia; Share Price Weakness, Potential Market Share Gain And High Short Position Present Buying Opportunities

23 Sept 2026
LHN (LHN SP): Resilient Core Operations; Growth Pipeline Intact
Our latest research

29 Oct 2026
Mapletree Industrial Trust (MINT SP): 2QFY27: Revamp Underway

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

29 Oct 2026