Company Coverage
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$8.00
S$10.16
+27.0%
S$12.18
Analyst
Analyst
Highlights
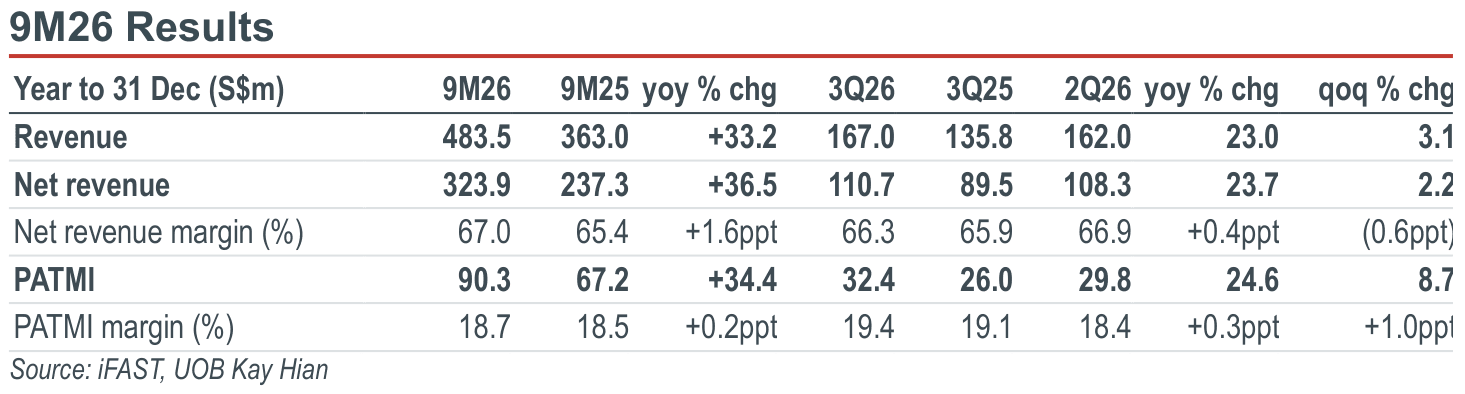
- 9M26 revenue of S$483.5m (+33% yoy) and PATMI of S$90.3m (+34% yoy) were above expectations, forming 77%/80% of our full-year forecasts.
- AUA hit a record S$36.76b (+20% yoy), with 9M26 net inflows of S$3.80b. iGB recorded 3Q26 PBT of S$3.29m (+965% yoy).
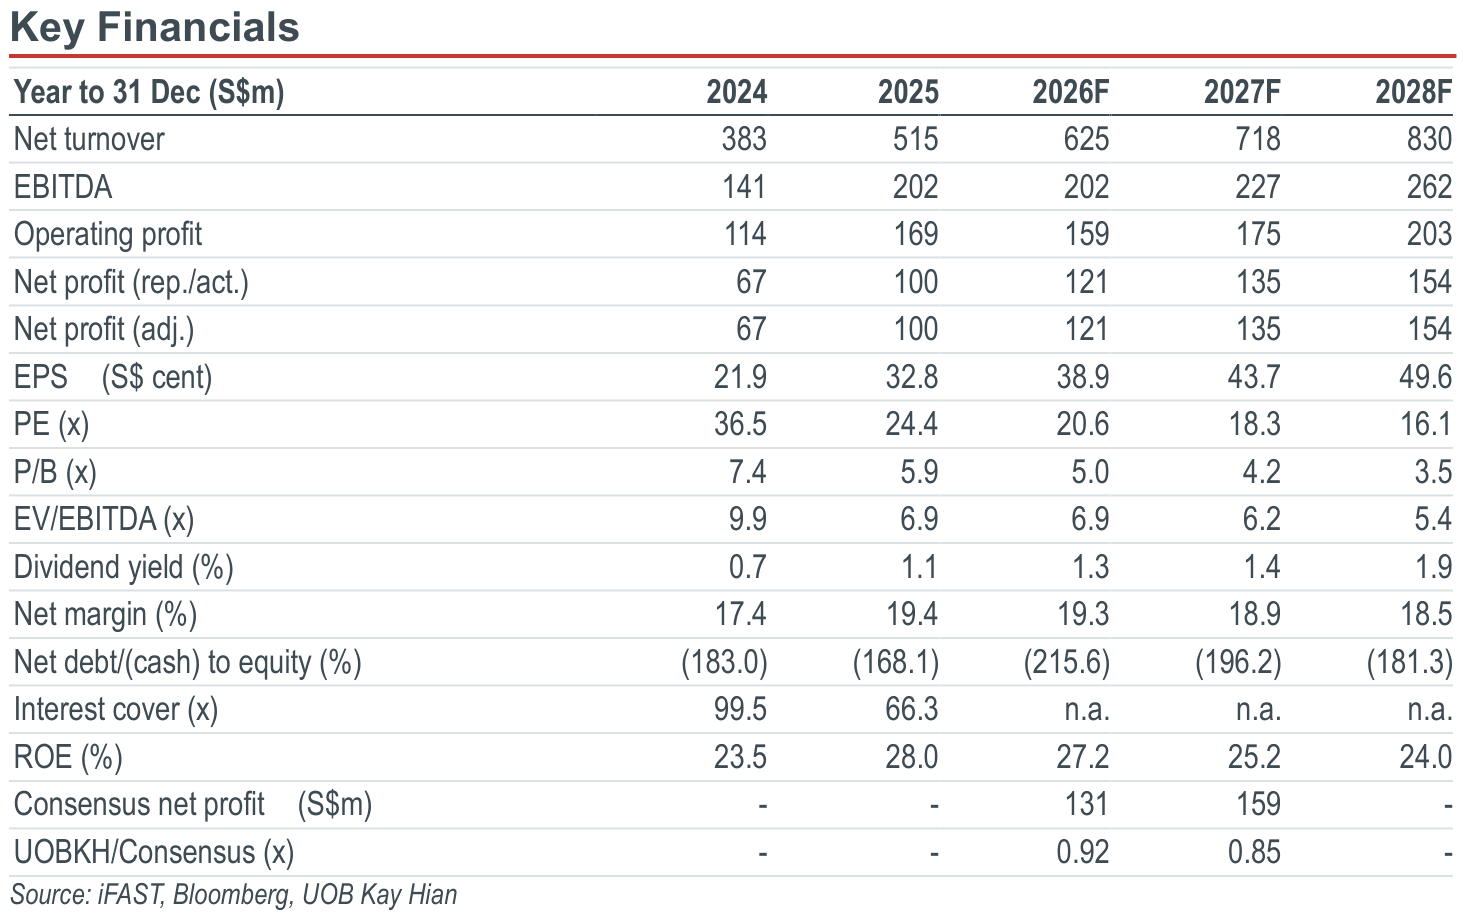
- We expect a net margin improvement for 2027 on better operating leverage. Maintain BUY with a lower target price of S$10.16, based on 23x 2027F PE.
Analysis
- 9M26 earnings slightly above expectations. iFAST Corporation (iFAST) delivered 3Q26 revenue of S$167.0m (+23.0% yoy) and PATMI of S$32.4m (+24.5% yoy), bringing 9M26 revenue to S$483.5m (+33.2% yoy) and PATMI to S$90.3m (+34.4% yoy), forming 77%/80% of our full-year forecasts respectively. Growth was driven by continued strength in the core wealth management platform and stronger contributions from iFAST Global Bank (iGB). Operating expenses rose 22.9% yoy to S$71.6m in 3Q26 (9M26: S$215.3m, +38.0% yoy), mainly due to higher staff costs, which management expects to moderate towards 2028 through fewer contract renewals and greater AI adoption to improve efficiency.
- New record-high AUA, broad-based across markets. Assets under administration (AUA) reached a new high of S$36.76b as at end-Sep 26 (+20.0% yoy, +1.7% qoq), driven by healthy net inflows of S$1.24b in 3Q26 (9M26: S$3.80b). All markets posted record AUA: Singapore +16.6% yoy, Hong Kong +22.4% yoy, Malaysia +28.7% yoy, China +52.9% yoy. By product, stocks and ETFs recorded the strongest growth at 41.0% yoy, while unit trusts and cash accounts and deposits grew 18.4% and 19.8% yoy respectively. Management reiterated its Vision 2030 target of S$100b AUA, implying a 25.6% CAGR from end-25, supported by the continued expansion of its wealth management platforms.
Highlights
- 9M26 revenue of S$483.5m (+33% yoy) and PATMI of S$90.3m (+34% yoy) were above expectations, forming 77%/80% of our full-year forecasts.
- AUA hit a record S$36.76b (+20% yoy), with 9M26 net inflows of S$3.80b. iGB recorded 3Q26 PBT of S$3.29m (+965% yoy).
- We expect a net margin improvement for 2027 on better operating leverage. Maintain BUY with a lower target price of S$10.16, based on 23x 2027F PE.
Analysis
- 9M26 earnings slightly above expectations. iFAST Corporation (iFAST) delivered 3Q26 revenue of S$167.0m (+23.0% yoy) and PATMI of S$32.4m (+24.5% yoy), bringing 9M26 revenue to S$483.5m (+33.2% yoy) and PATMI to S$90.3m (+34.4% yoy), forming 77%/80% of our full-year forecasts respectively. Growth was driven by continued strength in the core wealth management platform and stronger contributions from iFAST Global Bank (iGB). Operating expenses rose 22.9% yoy to S$71.6m in 3Q26 (9M26: S$215.3m, +38.0% yoy), mainly due to higher staff costs, which management expects to moderate towards 2028 through fewer contract renewals and greater AI adoption to improve efficiency.
- New record-high AUA, broad-based across markets. Assets under administration (AUA) reached a new high of S$36.76b as at end-Sep 26 (+20.0% yoy, +1.7% qoq), driven by healthy net inflows of S$1.24b in 3Q26 (9M26: S$3.80b). All markets posted record AUA: Singapore +16.6% yoy, Hong Kong +22.4% yoy, Malaysia +28.7% yoy, China +52.9% yoy. By product, stocks and ETFs recorded the strongest growth at 41.0% yoy, while unit trusts and cash accounts and deposits grew 18.4% and 19.8% yoy respectively. Management reiterated its Vision 2030 target of S$100b AUA, implying a 25.6% CAGR from end-25, supported by the continued expansion of its wealth management platforms.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$8.00
S$10.16
+27.0%
S$12.18
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

7 Sept 2026
Soon Hock Enterprise (SHOCK SP): 1H26: Robust Development Pipeline Supports Growth

8 Sept 2026
China Sunsine Chemical (CSSC SP): 1H26: Lacklustre Environment Offset By Decent 5% Yield

31 Aug 2026
Lum Chang Creations (LUCC SP): FY26: Strong Margin Expansion; Top-line Weakness Due To Timing
Our latest research

28 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze

26 Oct 2026