Company Coverage
Keppel REIT (KREIT SP): Refocusing On Home Base Singapore
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.785
S$1.060
35.0%
S$1.050
Analyst
Highlights
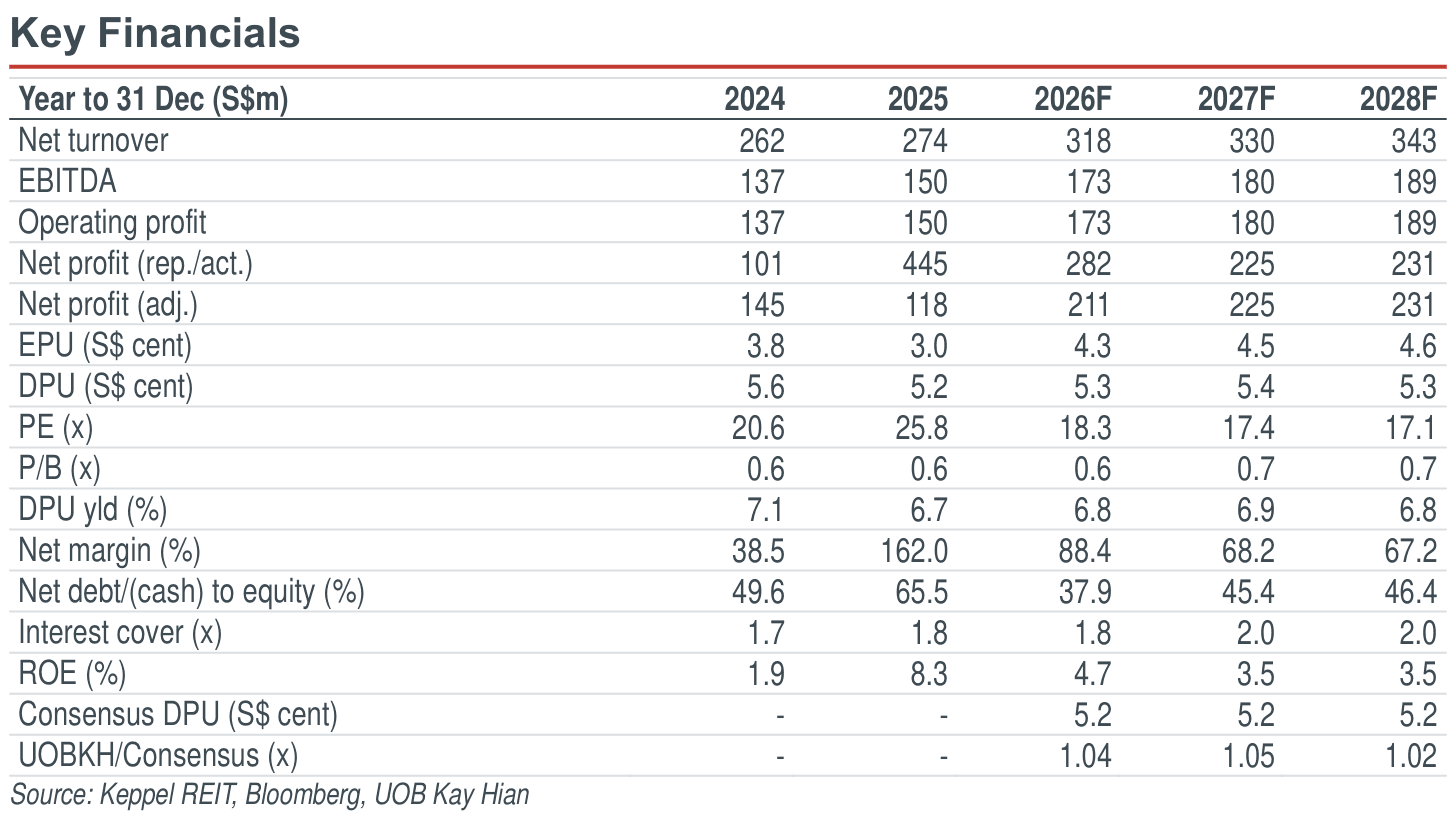
- KREIT has agreed to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd, for S$626.2m, equivalent to S$2,350psf and 3-4% below independent valuations. The acquisition provides an initial net property yield of 4.3% and is accretive to DPU by 2%.
- Sponsor Keppel Ltd will provide a guaranteed monthly income of S$2.23m for a period of five years. The guaranteed amount is based on 95% stabilised occupancy, average rent of S$11.15psf and an operating margin of 79%.
- Maintain BUY with a higher target price of S$1.06.
Analysis
- Tapping on sponsor pipeline. Keppel REIT (KREIT) has entered into a conditional agreement to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd. The transaction is based on an agreed property value of S$626.2m for the stake, equivalent to S$2,350psf and 3-4% below independent valuations that include the income support arrangement. KREIT is acquiring a 70-year leasehold interest in Keppel South Central. The proposed acquisition requires unitholder approval at an EGM expected in 4Q26, with completion targeted for 2Q27.
- Refocusing on home base in Singapore. Keppel South Central is a 33-storey Grade A commercial building in Tanjong Pagar with net lettable area of 522,500sf and was completed in Jan 25. It combines offices with retail, event and flexible workspace, alongside amenities including a gymnasium, swimming pool and sky terraces. Existing tenants include Manulife (insurance), Industrious (coworking) and the Competition & Consumer Commission of Singapore (government agency). The acquisition would expand KREIT’s portfolio to S$12.1b across 13 properties and increase Singapore’s share of portfolio valuation from 79% to 82%, assuming divestments of T Tower and KR Ginza II are already completed.
- Still ramping up occupancy. Committed occupancy was 48.8% as of Sep 26, rising to 52.7% when leases undergoing documentation were included. Committed occupancy is expected to increase to 60% by 15 Oct 26. Average rents for committed leases and those undergoing documentation were S$11.30psf per month, largely covering lower-to-mid floors. This exceeds the S$11.15 assumption underpinning the income support arrangement. The remaining mid-to-high floors are expected to fetch potentially higher rents.
Highlights
- KREIT has agreed to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd, for S$626.2m, equivalent to S$2,350psf and 3-4% below independent valuations. The acquisition provides an initial net property yield of 4.3% and is accretive to DPU by 2%.
- Sponsor Keppel Ltd will provide a guaranteed monthly income of S$2.23m for a period of five years. The guaranteed amount is based on 95% stabilised occupancy, average rent of S$11.15psf and an operating margin of 79%.
- Maintain BUY with a higher target price of S$1.06.
Analysis
- Tapping on sponsor pipeline. Keppel REIT (KREIT) has entered into a conditional agreement to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd. The transaction is based on an agreed property value of S$626.2m for the stake, equivalent to S$2,350psf and 3-4% below independent valuations that include the income support arrangement. KREIT is acquiring a 70-year leasehold interest in Keppel South Central. The proposed acquisition requires unitholder approval at an EGM expected in 4Q26, with completion targeted for 2Q27.
- Refocusing on home base in Singapore. Keppel South Central is a 33-storey Grade A commercial building in Tanjong Pagar with net lettable area of 522,500sf and was completed in Jan 25. It combines offices with retail, event and flexible workspace, alongside amenities including a gymnasium, swimming pool and sky terraces. Existing tenants include Manulife (insurance), Industrious (coworking) and the Competition & Consumer Commission of Singapore (government agency). The acquisition would expand KREIT’s portfolio to S$12.1b across 13 properties and increase Singapore’s share of portfolio valuation from 79% to 82%, assuming divestments of T Tower and KR Ginza II are already completed.
- Still ramping up occupancy. Committed occupancy was 48.8% as of Sep 26, rising to 52.7% when leases undergoing documentation were included. Committed occupancy is expected to increase to 60% by 15 Oct 26. Average rents for committed leases and those undergoing documentation were S$11.30psf per month, largely covering lower-to-mid floors. This exceeds the S$11.15 assumption underpinning the income support arrangement. The remaining mid-to-high floors are expected to fetch potentially higher rents.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.785
S$1.060
35.0%
S$1.050
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

3 Sept 2026
Keppel DC REIT (KDCREIT SP): Building Scale In Hyperscale DCs

14 Oct 2026
NTT DC REIT (NTTDCR SP): Embracing Closer Alignment With Unitholders’ Interest

24 Aug 2026
United Hampshire US REIT (UHU SP): 1H26: Resiliency From Focus On Essential Services
Our latest research

21 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): Retail Upside From Acquisition; Office Upside From Positive Reversion

19 Oct 2026
CSE Global (CSE SP): Positive Highlights From Meeting Reinforce Growth Outlook
14 Oct 2026