
Company Coverage
Singapore Airlines (SIA SP): Near-term Outlook Clouded By Elevated Jet Fuel Prices Amid Middle East Tensions
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
S$6.61
S$6.16
-6.8%
S$6.71
Analyst
Highlights
- Aug 26 operating data came in in line with our projection, with pax load and cargo load rising 1.5% and 2.8% yoy, respectively.
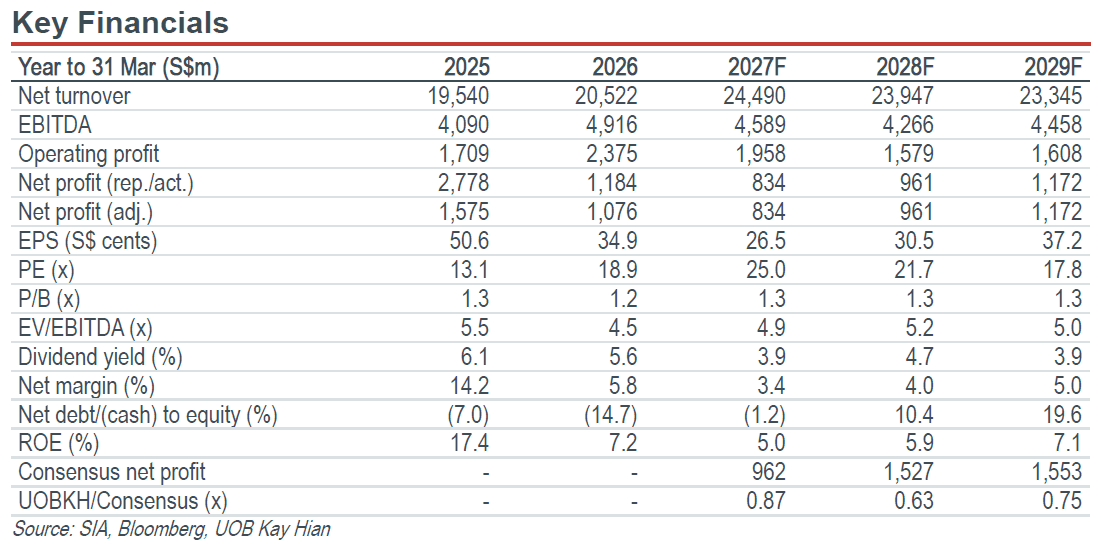
- The sharp rebound in jet fuel prices amid re-escalated Middle East tensions has led us to cut our FY27/28 earnings forecasts for SIA by 21%/5%, respectively. Our 2QFY27 net profit guidance has been reduced to S$230m-370m.
- Air India is reportedly seeking fresh capital injection from its owners including SIA. Weighing the opportunities in India and the uncertainties related to Air India’s turnaround timeline, we are largely neutral towards this deal.
- Downgrade SIA to SELL due to lack of near-term catalysts, with a lower target price of S$6.16 (pegged to 1.19x FY27F P/B).
Analysis
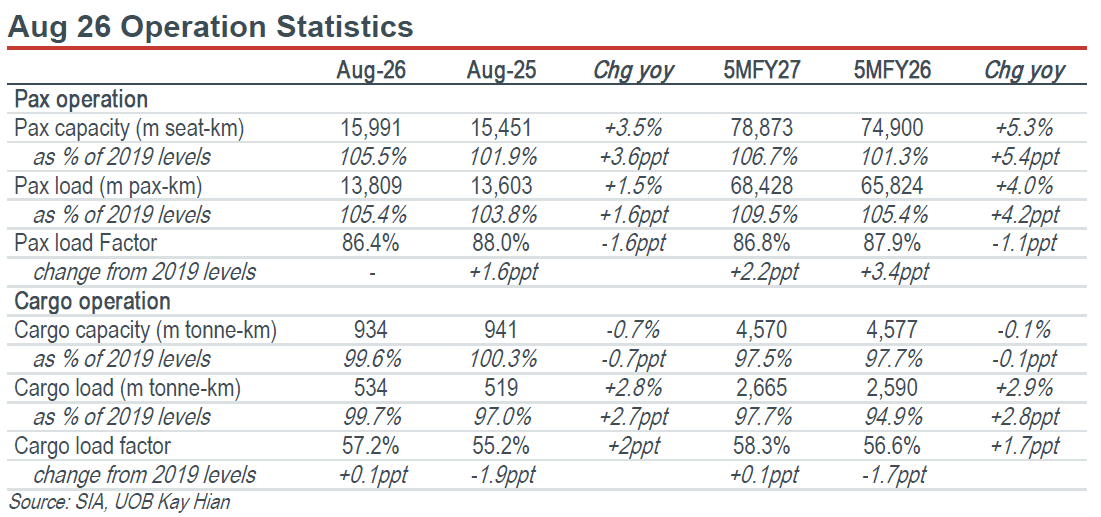
Aug 26 operating data broadly in line. Singapore Airlines’ (SIA) passenger load increased 1.5% yoy in Aug 26, supported by healthy air-travel demand, but lagged passenger capacity growth of 3.5% yoy. Consequently, passenger load factor declined 1.6ppt yoy to 86.4%, which remains healthy by historical standards. Cargo load rose 2.8% yoy, despite a 0.7% yoy drop in cargo capacity due to aircraft maintenance activity. As a result, cargo load factor improved 2.0ppt yoy to 57.2%. SIA noted that cargo demand remains strong across most markets, although e-commerce flows to Europe have softened following the EU’s introduction of a small-parcel duty and removal of the de minimis exemption from 1 Jul 26.
Highlights
- Aug 26 operating data came in in line with our projection, with pax load and cargo load rising 1.5% and 2.8% yoy, respectively.
- The sharp rebound in jet fuel prices amid re-escalated Middle East tensions has led us to cut our FY27/28 earnings forecasts for SIA by 21%/5%, respectively. Our 2QFY27 net profit guidance has been reduced to S$230m-370m.
- Air India is reportedly seeking fresh capital injection from its owners including SIA. Weighing the opportunities in India and the uncertainties related to Air India’s turnaround timeline, we are largely neutral towards this deal.
- Downgrade SIA to SELL due to lack of near-term catalysts, with a lower target price of S$6.16 (pegged to 1.19x FY27F P/B).
Analysis
Aug 26 operating data broadly in line. Singapore Airlines’ (SIA) passenger load increased 1.5% yoy in Aug 26, supported by healthy air-travel demand, but lagged passenger capacity growth of 3.5% yoy. Consequently, passenger load factor declined 1.6ppt yoy to 86.4%, which remains healthy by historical standards. Cargo load rose 2.8% yoy, despite a 0.7% yoy drop in cargo capacity due to aircraft maintenance activity. As a result, cargo load factor improved 2.0ppt yoy to 57.2%. SIA noted that cargo demand remains strong across most markets, although e-commerce flows to Europe have softened following the EU’s introduction of a small-parcel duty and removal of the de minimis exemption from 1 Jul 26.
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
S$6.61
S$6.16
-6.8%
S$6.71
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Jul 2026
Singapore Airlines (SIA SP): 1QFY27: Core Earnings Miss Expectations On Higher Fuel Costs And Air India Losses

7 Aug 2026
Singapore Exchange (SGX SP): FY26: Core Earnings Slightly Above Expectations; Outlook Remains Positive But Reflected By Rich Valuation

3 Aug 2026
Seatrium (STM SP): 1H26: Core Earnings Beat On Margins, But Orderbook On Hand Low; Focus On New Order Wins In 2H26
Our latest research

11 Sept 2026
Singapore Telecommunications (ST SP): Driving Long-Term ROIC Goals

10 Sept 2026
Centurion Accommodation REIT (CAREIT SP): Capacity Growth Largely Completed; Expanded Pipeline In Progress

9 Sept 2026