
Company Coverage
UltraGreen.ai (UGAI SP): 1H26: Robust Growth And More Positive Outlook For 2H26
BUY (Maintained)
Current price:
Target price:
Upside:
US$1.32
US$1.95
+47.7%
Analyst
Analyst
Analyst
Highlights
- 1H26 earnings of US$39m (+53% yoy) are in line with expectations, representing 48% of our 2026 forecast, with volume growing across all
geographies.
- Verdye approvals have increased from 35 to 43 countries, while IC-Flow approvals have risen from 40 to 46 countries since end-25.
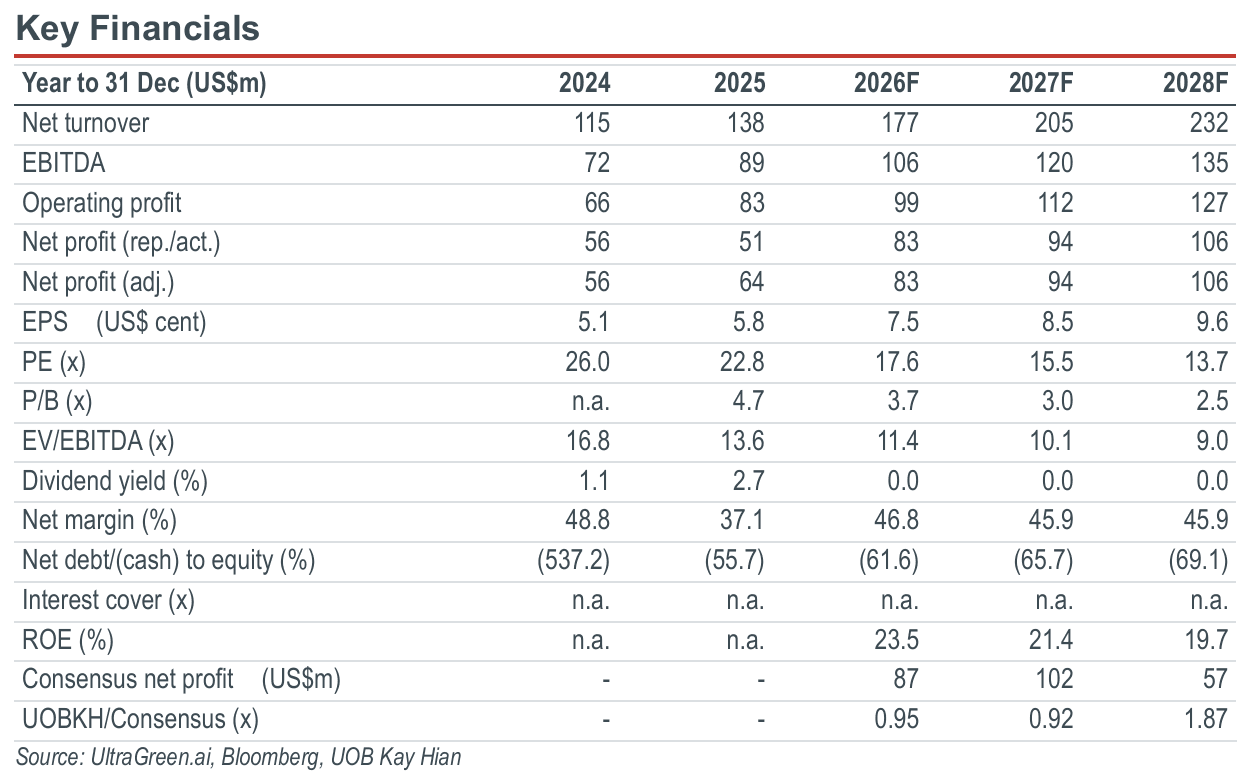
- UltraGreen has renewed its revenue guidance in anticipation of a better 2H26 revenue vs 1H26. Ultragreen is trading at an attractive PE of 16x 2027F vs
peers of 27x. Maintain BUY with an unchanged target price of US$1.95.
Analysis
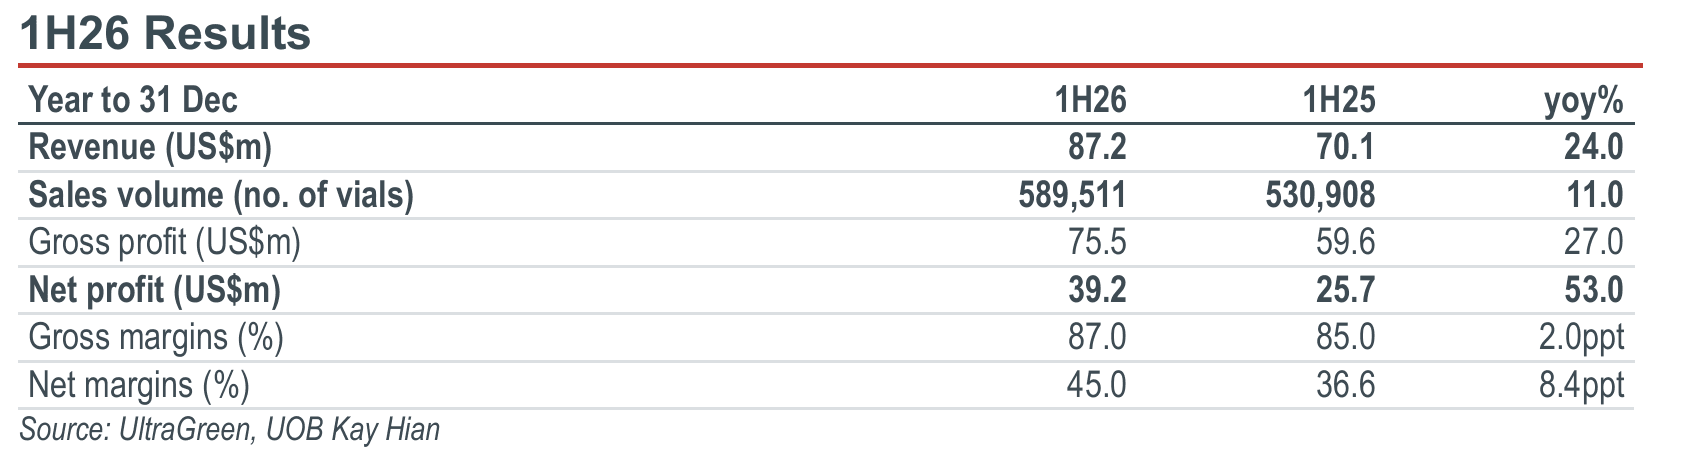
- Strong top-line growth, earnings in line. UltraGreen.ai (UltraGreen) reported 1H26 revenue of US$87.2m (+24% yoy) and PATMI of US$39.2m
(+53% yoy), forming 50% and 48% of our 2026 forecasts respectively. Growth was driven by an 11% yoy increase in Indocyanine Green (ICG) sales
volume, improved pricing in the US and continued adoption across key markets. Management also guides 2026 revenue of US$175m-185m, with
2H26 revenue expected to exceed 1H26, supporting continued growth momentum.
- Market and pipeline expansion support growth. UltraGreen continues to broaden its footprint, with Verdye approvals increasing from 35 to 43
countries and IC-Flow approvals from 40 to 46 countries since end-25. The company has also secured Denmark’s national tender through 2028. Beyond
geographical expansion, PerfusionWorks is progressing towards European regulatory approval, while expansion into new indicators such as wound care
should further broaden ICG adoption and support vial volume growth.
- Sales volumes continued to display momentum. 1H26 sales volumes rose 11% yoy to 589,511 vials, led by EMEA (+24% yoy to 196,165 vials)
and a lower-base APAC (+45% yoy to 15,730 vials), while the US grew at a more modest 4% yoy to 377,616 vials. This momentum is likely to continue
as global adoption of ICG in fluorescence-guided surgeries expands, with volumes expected to grow at a 3.1% CAGR through 2030.
- Strong balance sheet supports growth and shareholder returns. UltraGreen ended 1H26 with US$197.6m in cash and short-term liquid
investments, up 12% from end-25, while remaining debt-free. The group generated US$27.9m of operating cash flow, providing flexibility to fund
growth initiatives. It also declared a US$0.01/share interim dividend and repurchased around 1m shares, with management expecting to continue
returning capital through semi-annual dividends and share buybacks.
- Investing ahead of growth. Adjusted EBITDA rose 16% yoy to US$52.5m, although margin moderated 5ppt to 60% as operating expenses increased
66% yoy to US$28.0m. The higher cost base reflects increased investment in headcount, with employees rising to 112 from 73 in 1H25, increased
marketing expenditure, and higher listed company expenses. Management expects stronger operating leverage as revenue scales against the enlarged
cost base.
Highlights
- 1H26 earnings of US$39m (+53% yoy) are in line with expectations, representing 48% of our 2026 forecast, with volume growing across all
geographies.
- Verdye approvals have increased from 35 to 43 countries, while IC-Flow approvals have risen from 40 to 46 countries since end-25.
- UltraGreen has renewed its revenue guidance in anticipation of a better 2H26 revenue vs 1H26. Ultragreen is trading at an attractive PE of 16x 2027F vs
peers of 27x. Maintain BUY with an unchanged target price of US$1.95.
Analysis
- Strong top-line growth, earnings in line. UltraGreen.ai (UltraGreen) reported 1H26 revenue of US$87.2m (+24% yoy) and PATMI of US$39.2m
(+53% yoy), forming 50% and 48% of our 2026 forecasts respectively. Growth was driven by an 11% yoy increase in Indocyanine Green (ICG) sales
volume, improved pricing in the US and continued adoption across key markets. Management also guides 2026 revenue of US$175m-185m, with
2H26 revenue expected to exceed 1H26, supporting continued growth momentum.
- Market and pipeline expansion support growth. UltraGreen continues to broaden its footprint, with Verdye approvals increasing from 35 to 43
countries and IC-Flow approvals from 40 to 46 countries since end-25. The company has also secured Denmark’s national tender through 2028. Beyond
geographical expansion, PerfusionWorks is progressing towards European regulatory approval, while expansion into new indicators such as wound care
should further broaden ICG adoption and support vial volume growth.
- Sales volumes continued to display momentum. 1H26 sales volumes rose 11% yoy to 589,511 vials, led by EMEA (+24% yoy to 196,165 vials)
and a lower-base APAC (+45% yoy to 15,730 vials), while the US grew at a more modest 4% yoy to 377,616 vials. This momentum is likely to continue
as global adoption of ICG in fluorescence-guided surgeries expands, with volumes expected to grow at a 3.1% CAGR through 2030.
- Strong balance sheet supports growth and shareholder returns. UltraGreen ended 1H26 with US$197.6m in cash and short-term liquid
investments, up 12% from end-25, while remaining debt-free. The group generated US$27.9m of operating cash flow, providing flexibility to fund
growth initiatives. It also declared a US$0.01/share interim dividend and repurchased around 1m shares, with management expecting to continue
returning capital through semi-annual dividends and share buybacks.
- Investing ahead of growth. Adjusted EBITDA rose 16% yoy to US$52.5m, although margin moderated 5ppt to 60% as operating expenses increased
66% yoy to US$28.0m. The higher cost base reflects increased investment in headcount, with employees rising to 112 from 73 in 1H25, increased
marketing expenditure, and higher listed company expenses. Management expects stronger operating leverage as revenue scales against the enlarged
cost base.
BUY (Maintained)
Current price:
Target price:
Upside:
US$1.32
US$1.95
+47.7%
Analyst
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Aug 2026
UMS Integration (UMSH SP): 1H26: Earnings Above Expectation; Optimistic About Continued Robust Growth

17 Aug 2026
CSE Global (CSE SP) 1H26: Earnings Impacted by One-Offs; 2H26 Earnings To Be Stronger

12 Aug 2026
SEA (SE US): 1H26: Solid Delivery Across All Segments; Outlook Raised
Our latest research

29 Sept 2026
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy

28 Sept 2026
UI Boustead REIT (UIBREIT SP) : On Track To Meet Forecast; Expect Higher Reversions In 2HFY27

28 Sept 2026