
Periodic/Sector reports
Plantation: Firmer 2027 CPO Lifts Upstream Earnings
OVERWEIGHT (Maintained)
Analyst
Amerul Iqmal Abd Majid
ameruliqmal@uobkh.comAnalyst
Singapore Research Team
research@uobkh.comHighlights
- We raise our 2027 CPO price assumption to RM4,700/tonne from RM4,400, as El Niño-induced dryness should strain production while Indonesia’s B50 mandate would limit the country’s exportable supply.
- We increase our 2027 net profit forecasts for Bumitama (BAL) by 9.6% and 12.1% for First Resources (FR). Indonesian producers keep less of each ringgit of price upside than Malaysian peers, as the export levy rises with the reference price.
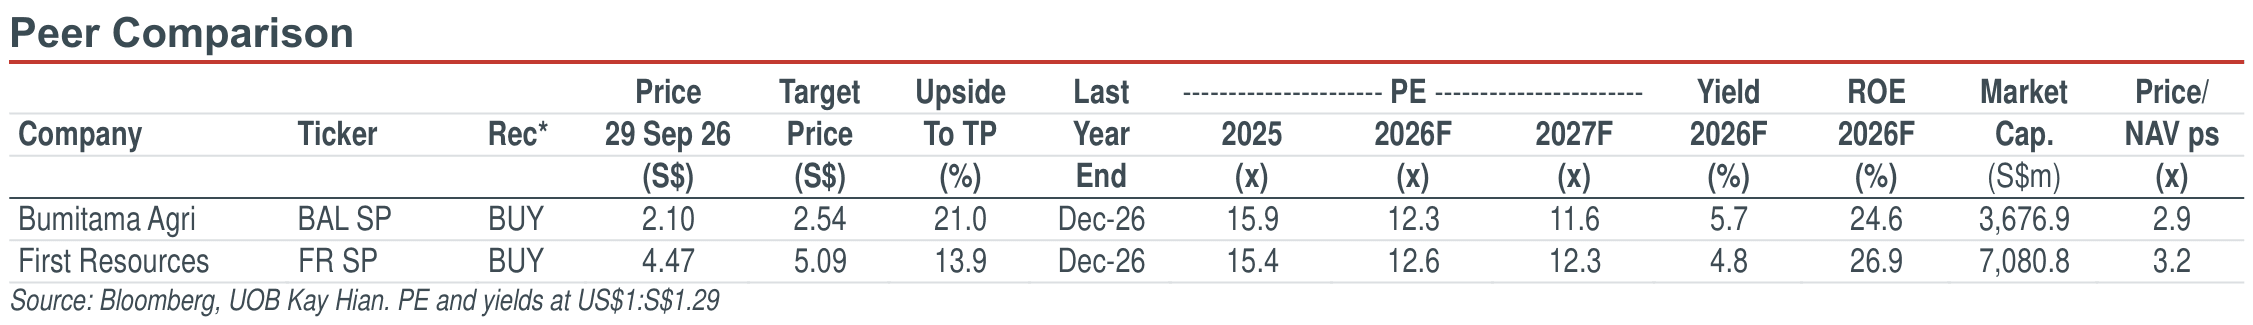
- We raise our target prices for BAL to S$2.54 (from S$2.15) and FR to S$5.09 (from S$4.57), and maintain BUY on both. BAL remains our top pick as it has the purest upstream exposure, with 21% upside to its share price.
- Maintain OVERWEIGHT on the sector.
Analysis
- Indonesian supply is holding up for now. The Indonesian Palm Oil Association's (GAPKI) July data put production at 5.37m tonnes, up 1.9% mom, taking January-July output to 35.65m tonnes, up 6.4% yoy. Ending stocks stood at 2.76m tonnes, 7.4% higher than a year earlier. The squeeze will come in 2027 - we expect Indonesian output to fall 3.0% to 52.87m tonnes as the El Niño rainfall deficit feeds through to the harvest.
- B50 to limit Indonesia’s exportable supply of CPO. Biodiesel absorbed 7.86m tonnes of palm oil in January-July, up 8.6% yoy, with July's 1.29m tonnes being the highest monthly figure this year. Total domestic consumption rose 6.4% yoy to 15.22m tonnes, well ahead of exports at +2.9%. With the 50% biodiesel mandate reaching full pump coverage on 1 October, we expect Indonesian exports to fall 10.6% to 22.99m tonnes in 2027.
- Indonesian growers keep less of the upside. Indonesia's export levy rises with the CPO reference price, so part of any price gain is deducted before it reaches growers. Our RM300/tonne upgrade is worth about US$70/tonne, and we raise our 2027 levy assumptions by 10% of that increase, to US$251/tonne for BAL and US$172/tonne for FR. The higher levy takes about 2ppt off each company's 2027 earnings upgrade.
- El Niño trims the 2027 crop. We now assume own fresh fruit bunch (FFB) output falls 1.0% yoy in 2027 for both companies, from +2.5% previously for BAL and flat for FR. For BAL, we maintain our previous forecast for bought-in fruit volumes, so its 2027 CPO output is 2.1% below our earlier estimate. Our 2028 FFB growth assumptions are unchanged, as the lower 2027 base carries into 2028.
- Earnings estimates. We raise our 2027 net profit forecasts by 9.6% for BAL and 12.1% for FR. The higher CPO price alone adds 15-20% to the companies’ 2027 earnings, before the negative impact of the higher export levy (-1.6ppt to -2.4ppt) and the smaller FFB output (-1.6ppt to -7.5ppt) are taken into account.
Highlights
- We raise our 2027 CPO price assumption to RM4,700/tonne from RM4,400, as El Niño-induced dryness should strain production while Indonesia’s B50 mandate would limit the country’s exportable supply.
- We increase our 2027 net profit forecasts for Bumitama (BAL) by 9.6% and 12.1% for First Resources (FR). Indonesian producers keep less of each ringgit of price upside than Malaysian peers, as the export levy rises with the reference price.
- We raise our target prices for BAL to S$2.54 (from S$2.15) and FR to S$5.09 (from S$4.57), and maintain BUY on both. BAL remains our top pick as it has the purest upstream exposure, with 21% upside to its share price.
- Maintain OVERWEIGHT on the sector.
Analysis
- Indonesian supply is holding up for now. The Indonesian Palm Oil Association's (GAPKI) July data put production at 5.37m tonnes, up 1.9% mom, taking January-July output to 35.65m tonnes, up 6.4% yoy. Ending stocks stood at 2.76m tonnes, 7.4% higher than a year earlier. The squeeze will come in 2027 - we expect Indonesian output to fall 3.0% to 52.87m tonnes as the El Niño rainfall deficit feeds through to the harvest.
- B50 to limit Indonesia’s exportable supply of CPO. Biodiesel absorbed 7.86m tonnes of palm oil in January-July, up 8.6% yoy, with July's 1.29m tonnes being the highest monthly figure this year. Total domestic consumption rose 6.4% yoy to 15.22m tonnes, well ahead of exports at +2.9%. With the 50% biodiesel mandate reaching full pump coverage on 1 October, we expect Indonesian exports to fall 10.6% to 22.99m tonnes in 2027.
- Indonesian growers keep less of the upside. Indonesia's export levy rises with the CPO reference price, so part of any price gain is deducted before it reaches growers. Our RM300/tonne upgrade is worth about US$70/tonne, and we raise our 2027 levy assumptions by 10% of that increase, to US$251/tonne for BAL and US$172/tonne for FR. The higher levy takes about 2ppt off each company's 2027 earnings upgrade.
- El Niño trims the 2027 crop. We now assume own fresh fruit bunch (FFB) output falls 1.0% yoy in 2027 for both companies, from +2.5% previously for BAL and flat for FR. For BAL, we maintain our previous forecast for bought-in fruit volumes, so its 2027 CPO output is 2.1% below our earlier estimate. Our 2028 FFB growth assumptions are unchanged, as the lower 2027 base carries into 2028.
- Earnings estimates. We raise our 2027 net profit forecasts by 9.6% for BAL and 12.1% for FR. The higher CPO price alone adds 15-20% to the companies’ 2027 earnings, before the negative impact of the higher export levy (-1.6ppt to -2.4ppt) and the smaller FFB output (-1.6ppt to -7.5ppt) are taken into account.
OVERWEIGHT (Maintained)
Analyst
Amerul Iqmal Abd Majid
ameruliqmal@uobkh.comAnalyst
Singapore Research Team
research@uobkh.comIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

10 Sept 2026
REITs: New Normal Of Higher Bond Yields… Elsewhere

11 Aug 2026
Banking: 2Q26 Results Round-up: Sustainable Momentum On Rising Affluence And Wealth Creation Within Asia

4 Sept 2026
REITs - 2Q26 Round-Up: Soldiering On With Resilient Yield
Our latest research

1 Oct 2026
REITs: S-REITs Monthly Update (Sep 26)

24 Sept 2026
Banking: Benefitting From Higher For Longer Bond Yields And Interest Rates

17 Sept 2026