Periodic/Sector reports
Technology: Stay Selective On Stocks With High Yields And Strong Balance Sheets
MARKET WEIGHT (Maintained)
Analyst
Analyst
Analyst
Highlights
- Semiconductor-related stocks are expected to report stronger earnings in 3Q26, while the others are expected to show decent growth.
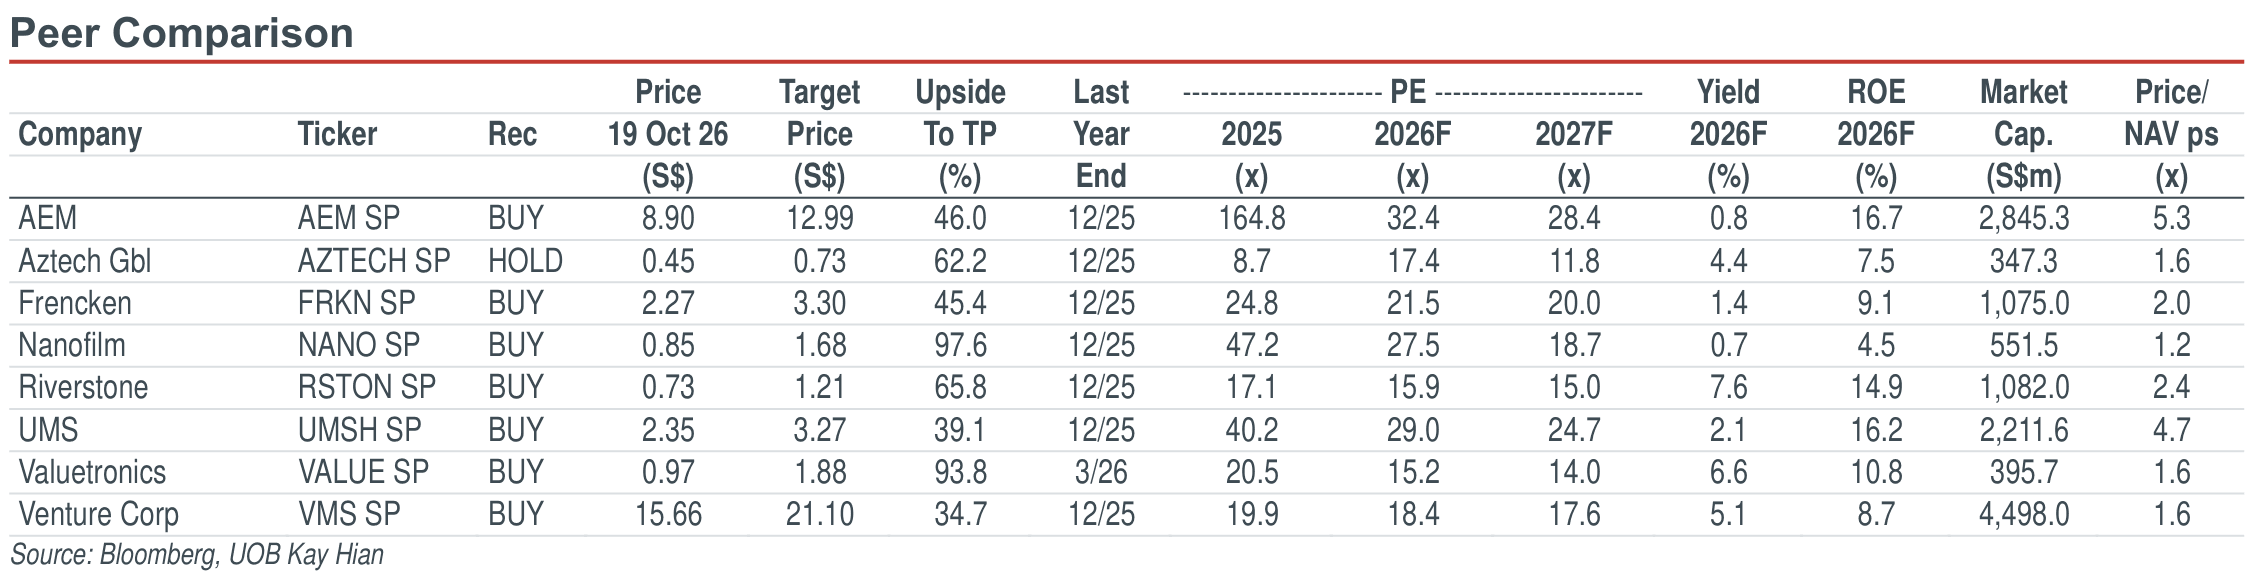
- We recommend staying selective on stocks with strong balance sheets and offer attractive yields given that valuation of the semiconductor stocks are relatively rich at above +1SD above mean PE for 2026.
- Our top picks are Valuetronics (7% yield), Riverstone (8% yield) and Venture (5% yield) given their attractive yield, valuation and growth prospects. Maintain MARKET WEIGHT.
Analysis
- Companies are scheduled to release their 3Q26 results between 27 October and 14 November. Tech companies under our coverage will be releasing their 3Q26 results starting from next week with Aztech scheduled to report on 27 October, Nanofilm on 29 October and Valuetronics on 11 November. We categorise the stocks into two groups: a) semiconductor-related names (AEM, UMS, Frencken), and b) other manufacturing stocks (Valuetronics, Riverstone, Venture Corp, Aztech and Nanofilm).
- Semiconductor-related stocks to report strong yoy growth for 3Q26. We believe the semiconductor-related stocks will report stronger results for 3Q26 given the positive industry tailwinds and strong indications from their key customers. We expect UMS and Frencken to report earnings of S$19m and S$12m for 3Q26, respectively, indicating a strong yoy growth of 81% and 21% yoy as well as qoq growth of 0% and 6%. The key drivers are increased orders from key semiconductor customers including AMAT, Lam Research and ASML. On the other hand, AEM is expected to report 3Q26 earnings of S$29m, indicating a 77% qoq growth, driven by the production ramp-up of its fabless AI/HPC customer and the PC/foundry customer’s adoption of the AMPS (Asynchronous Modular Parallel Smart) platform for future test requirements. To recap, AEM’s earnings for 3Q25 were a marginal loss due to weak operating leverage, and a yoy comparison will not be accurate.
- Other manufacturing stocks to report decent growth. Except for Aztech, the other manufacturing stocks are expected to report decent yoy and qoq growth. Three of our top picks, Valuetronics, Riverstone and Venture Corp, are expected to record yoy earnings growth in 3Q26, driven by better customers’ orders. Valuetronics is expected to deliver 2% yoy and 70% qoq earnings growth for 1HFY26 as customers from the network access solution and entertainment-focused customers increase their orders. Riverstone is expected to deliver a 27% yoy and 1% qoq earnings growth for 3Q26 driven by higher volume, ASP and better net margin, especially for the cleanroom glove segment. Venture is expected to record 13% yoy earnings growth for 3Q26, as demand strengthens in its networking & communications and semiconductor-related equipment domains.
Highlights
- Semiconductor-related stocks are expected to report stronger earnings in 3Q26, while the others are expected to show decent growth.
- We recommend staying selective on stocks with strong balance sheets and offer attractive yields given that valuation of the semiconductor stocks are relatively rich at above +1SD above mean PE for 2026.
- Our top picks are Valuetronics (7% yield), Riverstone (8% yield) and Venture (5% yield) given their attractive yield, valuation and growth prospects. Maintain MARKET WEIGHT.
Analysis
- Companies are scheduled to release their 3Q26 results between 27 October and 14 November. Tech companies under our coverage will be releasing their 3Q26 results starting from next week with Aztech scheduled to report on 27 October, Nanofilm on 29 October and Valuetronics on 11 November. We categorise the stocks into two groups: a) semiconductor-related names (AEM, UMS, Frencken), and b) other manufacturing stocks (Valuetronics, Riverstone, Venture Corp, Aztech and Nanofilm).
- Semiconductor-related stocks to report strong yoy growth for 3Q26. We believe the semiconductor-related stocks will report stronger results for 3Q26 given the positive industry tailwinds and strong indications from their key customers. We expect UMS and Frencken to report earnings of S$19m and S$12m for 3Q26, respectively, indicating a strong yoy growth of 81% and 21% yoy as well as qoq growth of 0% and 6%. The key drivers are increased orders from key semiconductor customers including AMAT, Lam Research and ASML. On the other hand, AEM is expected to report 3Q26 earnings of S$29m, indicating a 77% qoq growth, driven by the production ramp-up of its fabless AI/HPC customer and the PC/foundry customer’s adoption of the AMPS (Asynchronous Modular Parallel Smart) platform for future test requirements. To recap, AEM’s earnings for 3Q25 were a marginal loss due to weak operating leverage, and a yoy comparison will not be accurate.
- Other manufacturing stocks to report decent growth. Except for Aztech, the other manufacturing stocks are expected to report decent yoy and qoq growth. Three of our top picks, Valuetronics, Riverstone and Venture Corp, are expected to record yoy earnings growth in 3Q26, driven by better customers’ orders. Valuetronics is expected to deliver 2% yoy and 70% qoq earnings growth for 1HFY26 as customers from the network access solution and entertainment-focused customers increase their orders. Riverstone is expected to deliver a 27% yoy and 1% qoq earnings growth for 3Q26 driven by higher volume, ASP and better net margin, especially for the cleanroom glove segment. Venture is expected to record 13% yoy earnings growth for 3Q26, as demand strengthens in its networking & communications and semiconductor-related equipment domains.
MARKET WEIGHT (Maintained)
Analyst
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships

10 Sept 2026
REITs: New Normal Of Higher Bond Yields… Elsewhere

17 Sept 2026
Property: August Home Sales Dragged By Lack Of New Launches
Our latest research

16 Oct 2026
Property: New-home Sales Improve In September

15 Oct 2026
Banking: 3Q26 Results Preview: NIM Bottoming, While Net Interest Income Turns Around
12 Oct 2026