
Key Indices
Top Stories
Company Results | Beng Kuang Marine (BKM SP/BUY/S$0.380/Target: S$0.70)
- BKM's 3Q26 revenue rose 10.1% yoy to S$28.6m, while PATMI surged 174.6% to S$4.2m. 9M26 revenue and PATMI met 77.3% and 76.6% of our 2026 forecasts respectively. Maintain BUY with a S$0.70 target price, implying 84.2% upside. Our 13.1x 2027F PE peg is 1.0 SD above the historical mean, supported by stronger offshore execution and full ownership of ASOM's earnings.
Company Results | CapitaLand Investment (CLI SP/BUY/S$2.38/Target: S$3.80)
- CLI’s 9M26 business update showed momentum in its fee business, delivering a 15% yoy FRB revenue growth. With S$4.3b of equity raised by its listed and private funds and S$9.6b of capital deployed for 11M26, we anticipate strong visibility for its fee income outlook. CLI established FeeCo and AssetCo to build scale for recurring fee income and drive monetisation of assets through various capital recycling platforms, particularly for its China assets. Maintain BUY with a lower target price of S$3.80.
Company Results | SIA Engineering (SIE SP/BUY/S$2.92/Target: S$3.60)
- SIAEC’s 1HFY27 net profit of S$81.9m (-1.7% yoy) is in line with our expectations. Underlying earnings growth was masked by SAESL-related gestation costs, excluding which SIAEC’s earnings would have risen by close to 20% yoy. SIAEC continues to push capacity and regional expansion, which comes with near-term gestation pains. That said, gestation costs are expected to peak in FY27 and taper from FY28 onwards, driving a medium-term earnings growth. Maintain BUY with a lower target price of S$3.60.
Company Results | United Overseas Bank (UOB SP/NOT RATED/S$38.44)
- UOB’s 3Q26 net profit fell 15% qoq to S$1,250m, below consensus estimate of S$1,376m, as margin compression and weaker trading income weighed on earnings. Asset quality improved, with new NPL formation declining to S$500m, NPL ratio easing to 1.5% and credit costs falling to 24bp in 3Q26.
Market Spotlight
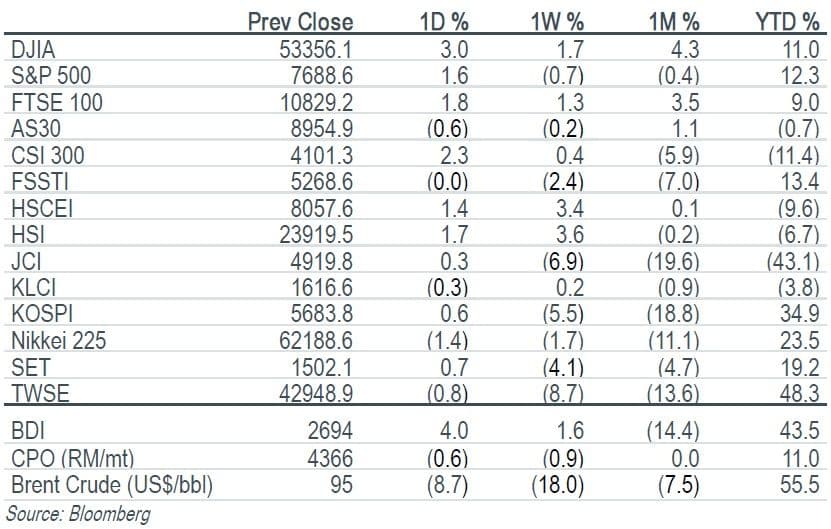
- US stocks were higher on Wednesday. All indices rose as the consumer discretionary, financials and real estate sectors fell. There were more advancers than decliners on both NYSE and NASDAQ.
- The FSSTI fell 0.66 points to 5,268.63, on the back of weakness in DBS and OCBC Bank, with both mid- and small-cap indices rising with a broad market decline on a S$2.88b turnover.
Technical Analysis
Venture Corp | VMS SP
Trading Buy Range: S$14.87-14.88
Riverstone Holdings | RSTON SP
Trading Buy Range: S$0.730-0.735
Top Stories
Company Results | Beng Kuang Marine (BKM SP/BUY/S$0.380/Target: S$0.70)
- BKM's 3Q26 revenue rose 10.1% yoy to S$28.6m, while PATMI surged 174.6% to S$4.2m. 9M26 revenue and PATMI met 77.3% and 76.6% of our 2026 forecasts respectively. Maintain BUY with a S$0.70 target price, implying 84.2% upside. Our 13.1x 2027F PE peg is 1.0 SD above the historical mean, supported by stronger offshore execution and full ownership of ASOM's earnings.
Company Results | CapitaLand Investment (CLI SP/BUY/S$2.38/Target: S$3.80)
- CLI’s 9M26 business update showed momentum in its fee business, delivering a 15% yoy FRB revenue growth. With S$4.3b of equity raised by its listed and private funds and S$9.6b of capital deployed for 11M26, we anticipate strong visibility for its fee income outlook. CLI established FeeCo and AssetCo to build scale for recurring fee income and drive monetisation of assets through various capital recycling platforms, particularly for its China assets. Maintain BUY with a lower target price of S$3.80.
Company Results | SIA Engineering (SIE SP/BUY/S$2.92/Target: S$3.60)
- SIAEC’s 1HFY27 net profit of S$81.9m (-1.7% yoy) is in line with our expectations. Underlying earnings growth was masked by SAESL-related gestation costs, excluding which SIAEC’s earnings would have risen by close to 20% yoy. SIAEC continues to push capacity and regional expansion, which comes with near-term gestation pains. That said, gestation costs are expected to peak in FY27 and taper from FY28 onwards, driving a medium-term earnings growth. Maintain BUY with a lower target price of S$3.60.
Company Results | United Overseas Bank (UOB SP/NOT RATED/S$38.44)
- UOB’s 3Q26 net profit fell 15% qoq to S$1,250m, below consensus estimate of S$1,376m, as margin compression and weaker trading income weighed on earnings. Asset quality improved, with new NPL formation declining to S$500m, NPL ratio easing to 1.5% and credit costs falling to 24bp in 3Q26.
Market Spotlight
- US stocks were higher on Wednesday. All indices rose as the consumer discretionary, financials and real estate sectors fell. There were more advancers than decliners on both NYSE and NASDAQ.
- The FSSTI fell 0.66 points to 5,268.63, on the back of weakness in DBS and OCBC Bank, with both mid- and small-cap indices rising with a broad market decline on a S$2.88b turnover.
Technical Analysis
Venture Corp | VMS SP
Trading Buy Range: S$14.87-14.88
Riverstone Holdings | RSTON SP
Trading Buy Range: S$0.730-0.735
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


