Strategy
Strategy – SMID-Cap Outlook: SMID-Cap Retail Webinar Takeaway: Identifying Opportunities Amid Market Weakness
Analyst
Analyst
Analyst
Highlights
- We hosted a SMID-cap retail webinar on 8 Oct 26, attracting more than 100 retail investors.
- Key questions focused on buying opportunities amid the recent weakness in Singapore banks, preferred large cap names, SMID-cap stocks, sector rotation and the impact of rising interest rates.
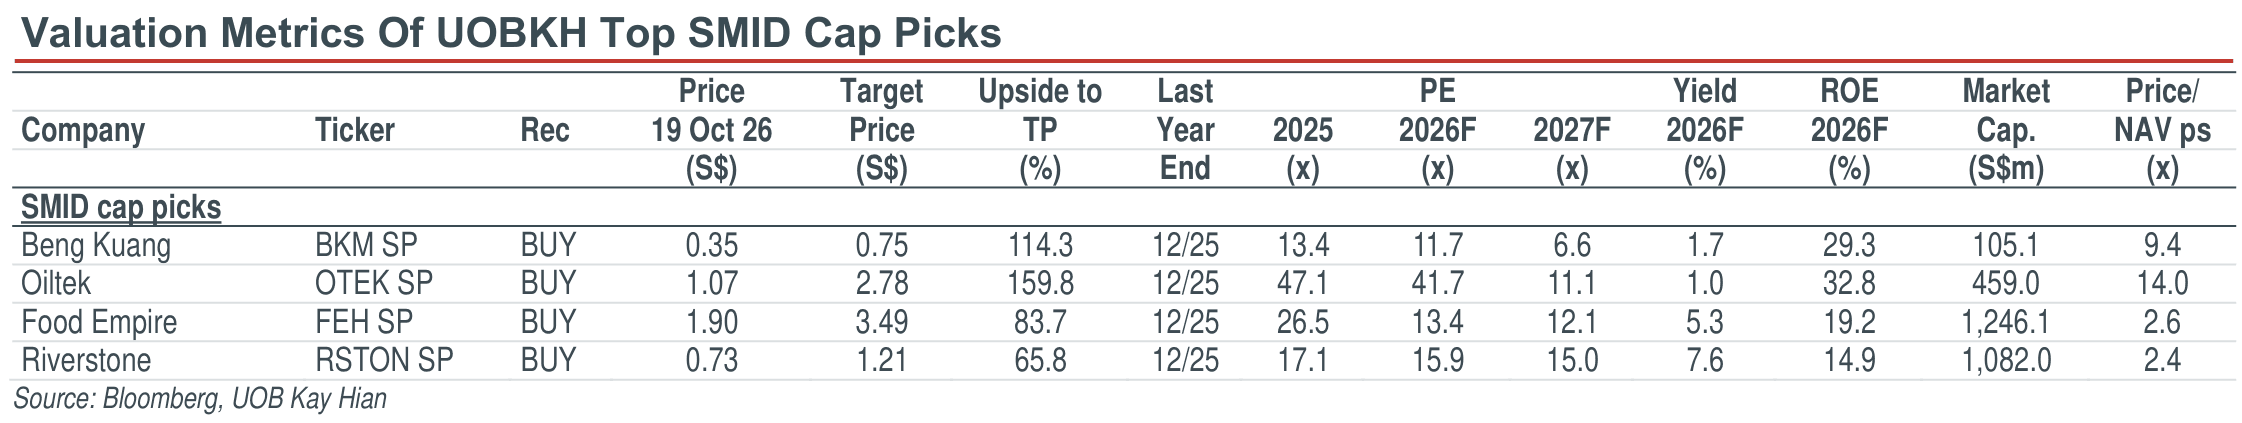
- We highlighted BKM, OTEK, FEH & RSTON as our top SMID-cap picks.
Analysis
- We hosted a SMID cap retail webinar on 8 Oct 26, attracting more than 100 retail investors. We reiterated our positive stance on four key SMID-cap picks, namely BKM, OTEK, FEH & RSTON, while addressing recent market weaknesses, sector rotation and stock-specific outlooks.
- BKM: We like Beng Kuang Marine (BKM) for its improving earnings visibility, driven by growing FPSO exposure and its highly recurring, asset-light business model. Strong 1H26 contract wins of S$85.2m brought its orderbook to S$70.7m as at end-Jun 26, providing solid revenue visibility. Full consolidation of ASOM should also drive a significant earnings uplift in 2H26. The stock trades at an attractive 8.9x 2027F PE versus peers at around 11.2x. Our target price is S$0.75, pegged to 14x 2027F PE.
- OTEK: We like Oiltek for its strong earnings outlook, supported by the RM1.4b Heads of Agreement (HOA) with Bioseaga, healthy net cash position and favourable industry tailwinds. Growing demand for sustainable aviation fuel (SAF), alongside a strong project pipeline and expansion into recurring income streams, should continue to drive contract wins and earnings growth. Following the recent pullback, we see scope for valuation re-rating, with the stock trading at an attractive 17x 2027F PE. Our target price is S$2.78, pegged to 28x 2027F PE.
- FEH: We like Food Empire (FEH) for its consistent earnings growth, strong pricing power and expanding production footprint. Upcoming capacity expansions in India and Vietnam, alongside its new Kazakhstan facility, should support long-term growth, while continued share buybacks enhance shareholder returns. We believe the recent share price correction is overdone, with its Russian operations remaining unaffected and potential market share gains presenting further upside. The stock trades at an attractive 12.5x 2027F PE versus peers at around 20x. Our target price is S$3.49, pegged to 25x 2026F PE.
- RSTON: We like Riverstone (RSTON) for its resilient cash generation, strong balance sheet and attractive dividend yield. Its debt-free, net cash position and ongoing shift towards higher-value gloves, supported by AI-driven cleanroom demand and improving healthcare pricing, should drive sustainable earnings growth. Following its strong 2Q26 results, the stock trades at an attractive 16x 2027F PE versus peers at around 22x, while offering a dividend yield of above 6%. Our target price is S$1.21, pegged to 24x 2027F PE.
Highlights
- We hosted a SMID-cap retail webinar on 8 Oct 26, attracting more than 100 retail investors.
- Key questions focused on buying opportunities amid the recent weakness in Singapore banks, preferred large cap names, SMID-cap stocks, sector rotation and the impact of rising interest rates.
- We highlighted BKM, OTEK, FEH & RSTON as our top SMID-cap picks.
Analysis
- We hosted a SMID cap retail webinar on 8 Oct 26, attracting more than 100 retail investors. We reiterated our positive stance on four key SMID-cap picks, namely BKM, OTEK, FEH & RSTON, while addressing recent market weaknesses, sector rotation and stock-specific outlooks.
- BKM: We like Beng Kuang Marine (BKM) for its improving earnings visibility, driven by growing FPSO exposure and its highly recurring, asset-light business model. Strong 1H26 contract wins of S$85.2m brought its orderbook to S$70.7m as at end-Jun 26, providing solid revenue visibility. Full consolidation of ASOM should also drive a significant earnings uplift in 2H26. The stock trades at an attractive 8.9x 2027F PE versus peers at around 11.2x. Our target price is S$0.75, pegged to 14x 2027F PE.
- OTEK: We like Oiltek for its strong earnings outlook, supported by the RM1.4b Heads of Agreement (HOA) with Bioseaga, healthy net cash position and favourable industry tailwinds. Growing demand for sustainable aviation fuel (SAF), alongside a strong project pipeline and expansion into recurring income streams, should continue to drive contract wins and earnings growth. Following the recent pullback, we see scope for valuation re-rating, with the stock trading at an attractive 17x 2027F PE. Our target price is S$2.78, pegged to 28x 2027F PE.
- FEH: We like Food Empire (FEH) for its consistent earnings growth, strong pricing power and expanding production footprint. Upcoming capacity expansions in India and Vietnam, alongside its new Kazakhstan facility, should support long-term growth, while continued share buybacks enhance shareholder returns. We believe the recent share price correction is overdone, with its Russian operations remaining unaffected and potential market share gains presenting further upside. The stock trades at an attractive 12.5x 2027F PE versus peers at around 20x. Our target price is S$3.49, pegged to 25x 2026F PE.
- RSTON: We like Riverstone (RSTON) for its resilient cash generation, strong balance sheet and attractive dividend yield. Its debt-free, net cash position and ongoing shift towards higher-value gloves, supported by AI-driven cleanroom demand and improving healthcare pricing, should drive sustainable earnings growth. Following its strong 2Q26 results, the stock trades at an attractive 16x 2027F PE versus peers at around 22x, while offering a dividend yield of above 6%. Our target price is S$1.21, pegged to 24x 2027F PE.
Analyst
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


