

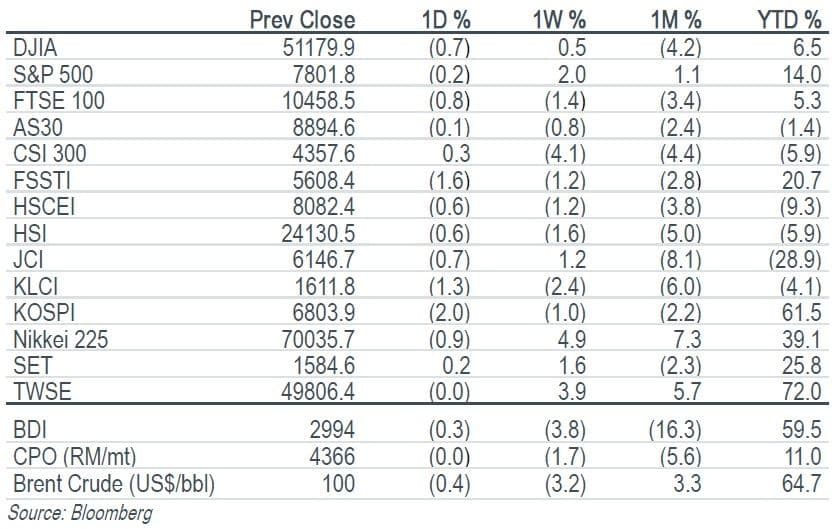
Key Indices
Top Stories
Company Results | Aeon Thana Sinsap (Thailand) (AEONTS TB/HOLD/Bt90.25/Target: Bt98.00)
- AEONTS posted a 2QFY27 net profit of Bt642m, down 19% yoy and 19% qoq, missing our and consensus expectations by 8% and 18%, respectively. Although there was a gain from the sale of bad debts, the higher provisioning dragged the bottom line. The shrinking in the hire-purchase portfolio was in line after experiencing the deterioration in asset quality. NPL ratio and credit cost jumped qoq. Downgrade to HOLD with a lower target price of Bt98.00.
Company Update | PTT Exploration and Production (PTTEP TB/BUY/Bt145.00/Target: Bt170.00)
- We expect PTTEP’s 3Q26 net profit at Bt20.4b, down 25% qoq, mainly due to lower sales volume and a significant oil hedging loss. Meanwhile, we project that 4Q26 core profit will remain broadly flat qoq, as higher sales volume should be sufficient to offset lower gas selling prices and raise unit costs. Nevertheless, persistently high crude oil prices should continue to support yoy growth in 2H26 core profit. Maintain BUY. Target price: Bt170.00.
Company Update | Supalai (SPALI TB/BUY/Bt15.90/Target: Bt17.50)
- SPALI’s 3Q26 outlook is neutral as Bangkok flooding delayed transfers and led to some project launch postponements. If the impact is in line with our expectations, there could be slight downside risk to our earnings forecasts. We expect 3Q26 net profit to come in at Bt6.084b, while 4Q26 should mark the earnings peak as delayed transfers are recognised. We maintain a neutral sector view and maintain SPALI as our top pick, supported by its strong balance sheet, low leverage, financial flexibility and Australian earnings contribution.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


