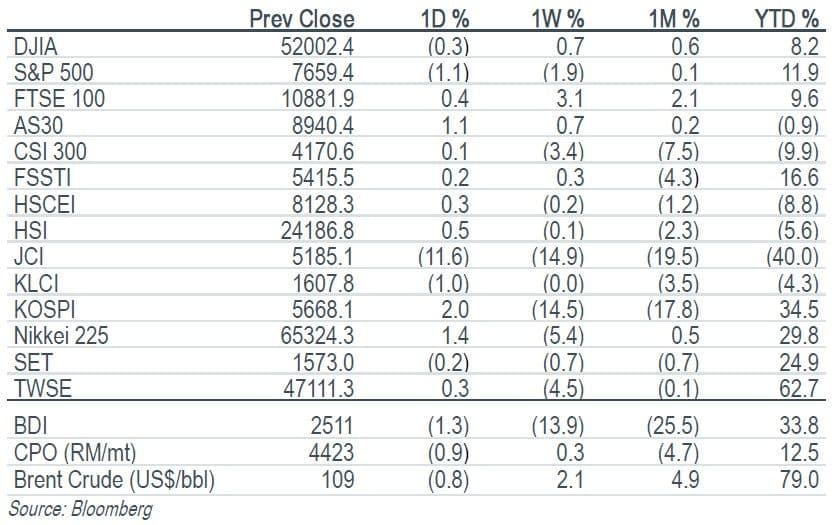
Key Indices
Top Stories
Company Update | Bangkok Dusit Medical Services (BDMS TB/BUY/Bt19.10/Target: Bt27.00)
- BDMS is expected to report a net profit of Bt4.66b in 3Q26 (+7.8% yoy, +43.4% qoq), driven by strong Thai patient revenue growth, recovering foreign patient demand, and improving operating leverage. Middle Eastern patient arrivals continue to recover, while the Bangkok floods resulted in only temporary appointment delays, with treatments expected to be rescheduled in 4Q26. We foresee strong 4Q26 earnings as patient inflow continues to be strong. Maintain BUY with a target price of Bt27.00.
Company Update | Bumrungrad Hospital (BH TB/BUY/Bt189.00/Target: Bt240.00)
- BH is expected to deliver a strong 3Q26 net profit of Bt2.1b (+3.5% yoy, +11.5% qoq) on revenue of Bt6.8b (+4.2% yoy, +8.5% qoq), driven by strong Middle Eastern patient arrivals which will lead to margin expansion on top of strict cost control. Middle Eastern patient inflows remain resilient despite regional conflict, with momentum expected to continue into 4Q26. Bangladeshi patient arrivals are recovering, while Iraq offers new growth potential. Maintain BUY with a target price of Bt240.
Company Update | COM7 (COM7 TB/BUY/Bt32.00/Target: Bt35.20)
- We expect COM7 to report a 49% yoy increase in its 3Q26 net profit, driven by growth in both retail and other businesses. 4Q26 earnings are expected to grow yoy, supported by higher iPhone ASPs and continued growth in UFund and iCare. Maintain BUY with a higher SOTP-based target price of Bt35.20. We revise up our 2026-27 earnings forecasts, reflecting stronger earnings contributions from UFund and iCare.
Company Update | KCE (Thailand) (KCE TB/HOLD/Bt74.75/Target: Bt80.00)
- We expect KCE to post strong earnings of Bt507m (+71% yoy, +84% qoq), driven by strong sales volume and higher PCB prices. Humanoid robot projects offer long-term diversification potential, but are unlikely to contribute meaningfully to earnings over the next several years. Downgrade to HOLD with a target price of Bt80.00, as the automotive PCB earnings cycle with a 35% CAGR in 2026-28 appears largely priced in. Further valuation re-rating requires new earnings catalysts that could deliver incremental earnings upside.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


