
Wealth Daily
Crypto Setback Jolts Stocks as Oil Rises
Today’s Must-Know News
Overnight Markets
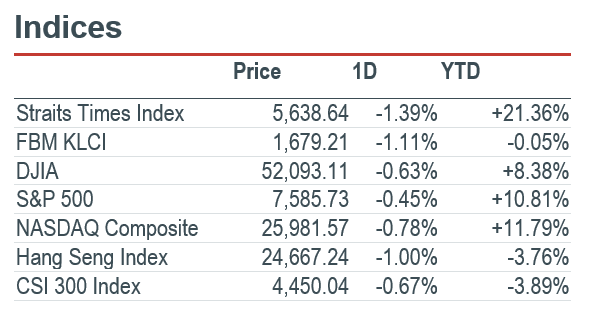
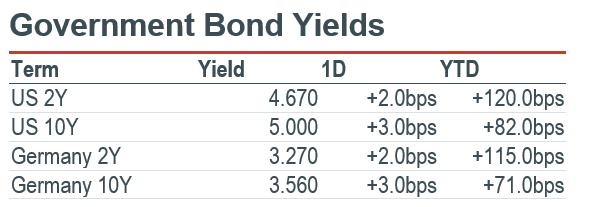
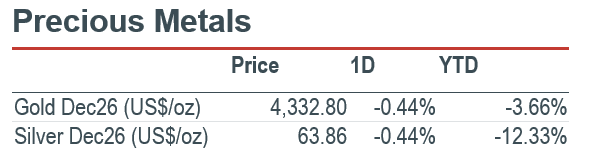
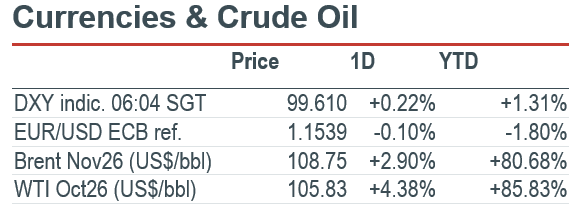
Market Movers: Coinbase Global (COIN US) fell about 10.1% in Tuesday’s US session after the Senate failed to advance the Clarity Act, leaving a durable federal framework for digital assets unresolved. Enova International (ENVA US) lost about 23.4% in its first full session after Monday’s bank-deal application withdrawal, despite unchanged earnings guidance. The two moves show how shifts in regulation can outweigh near-term operating targets. OpenAI separately disclosed on Tuesday that it was working with Anthropic and Google DeepMind on AI safety. Talks had been under way for weeks; the fresh disclosure does not establish a binding pause or lower spending plans. Cooperation offers a possible route to shared safeguards, while its effect on the pace and cost of frontier development remains uncertain. (Reuters / Company / Bloomberg)
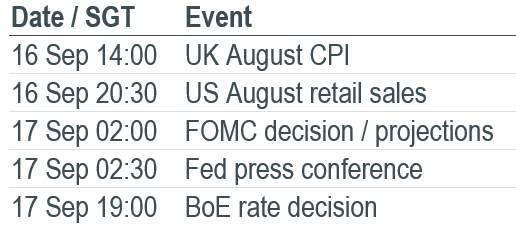
Macro: China’s August data showed a split recovery: factory output rose 5.2% year on year, but retail sales grew just 0.4% and January–August investment fell 7.2%. The gap points to stronger industrial supply than household demand, limiting the case for a broad recovery. Attention now turns to US retail sales at 20:30 SGT today and the Fed decision at 02:00 SGT on 17 September. The new projections will help frame the policy outlook as investors weigh growth against renewed energy costs. (Reuters / Census / Fed)
FICC: Tuesday’s oil settlements rose as shipping sources reported suspended Yanbu loadings and cancelled late-September cargoes. November Brent gained 2.90% to US$108.75/bbl and October WTI 4.38% to US$105.83/bbl, with US crude benefiting as refiners sought alternatives. The supply disruption raises input-cost risks even where demand remains soft. Tuesday’s US Treasury daily 10-year par yield rose 3.0bps from Monday’s 4.970% to 5.000%, lifting the discount rate facing long-duration assets. The combination keeps energy supply and the Fed’s inflation assessment central to the next session. (Reuters / US Treasury)
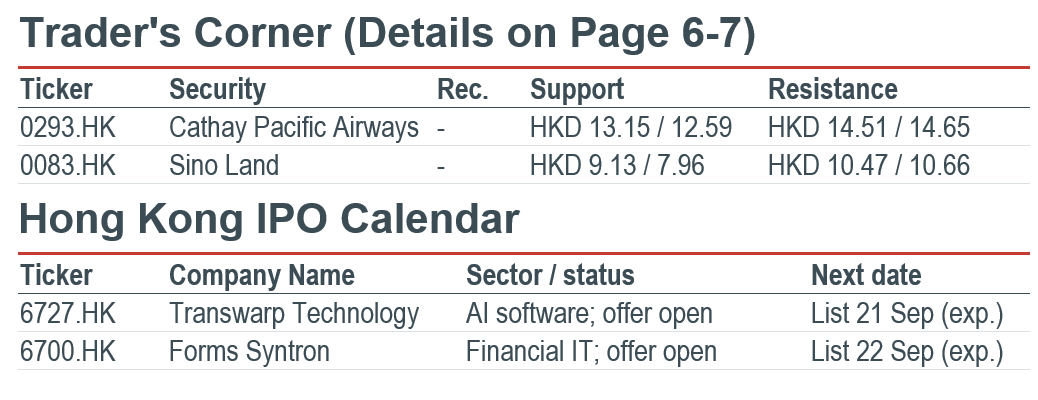
AI
Frontier labs disclose safety coordination. OpenAI said Tuesday it was working with Anthropic and Google DeepMind on AI safety. Executive Chris Lehane said talks had run for several weeks without requiring an antitrust waiver. The disclosure signals voluntary cooperation, establishing neither an agreed pause nor binding development limits. Its effect on model progress and computing expenditure remains uncertain. (Bloomberg)
Meta expands paid AI access across its social applications. Meta Platforms (META US) launched Meta One across Facebook, Instagram, WhatsApp and Meta AI on Tuesday. It reported over 50 features and 15 million subscriptions and trials. Paid bundles expand compute-intensive image and video tools while basic services stay free. This tests direct AI monetisation; subscriptions plus trials do not equal paying customers. (Company) Meta Platforms (META US) is our Core Recommendation.
Salesforce brings enterprise agents into everyday workflows. Salesforce (CRM US) unveiled AIforce at Dreamforce, connecting AI interfaces to CRM workflows within existing controls. Adecco announced Agentforce Coworker across over 40 countries and 27,000 employees, following British and French pilots. Earlier recruitment agents served ten countries representing half its revenue. Expansion tests whether adoption delivers productivity and recurring software demand. (Salesforce / Adecco)
Americas
Crypto legislation setback hits Coinbase. Coinbase Global (COIN US) fell 10.10% to US$172.11 in Tuesday’s US session after the Senate failed to advance the Clarity Act, which needed 60 votes. Without a federal digital-asset framework, exchanges remain more exposed to agency rulemaking and political or court challenges. The decline from Monday’s US$191.45 reflects regulatory repricing. (Reuters / Market data)
Enova reprices after its bank-acquisition route closes. Enova International (ENVA US) fell 23.43% to US$173.61 on Tuesday, reacting to Monday’s bank-acquisition application withdrawal. It reaffirmed 2026 revenue growth of 20–25% and adjusted EPS growth of 30–35%, and plans faster buybacks. The fall from US$226.72 shows unchanged guidance failed to offset the loss of the proposed Grasshopper banking structure. (Company / Market data)
Axon’s convertible financing weighs on shares. Axon Enterprise (AXON US) fell 9.81% to US$442.08 on Tuesday as it proposed US$1bn of zero-coupon September 2031 convertible notes, with a US$150mn option. Proceeds would fund capped calls and general corporate purposes, potentially acquisitions; conversion terms await pricing. Avoiding cash interest still introduces potential dilution and hedging effects despite planned mitigation. (Company / Market data)
Schwab records strong asset gathering in August. Charles Schwab (SCHW US) reported Tuesday that August core net new assets rose 46% annually to a record-for-August US$64.8bn. Client assets reached US$13.41trn, up 19% annually and 3% monthly; new accounts increased 11% to 424,000. Acquisition and engagement support fee and financing opportunities, although market appreciation differs from organic inflows. (Company)
Dave & Buster’s earnings reaction exposes margin pressure. Dave & Buster’s (PLAY US) fell 19.01% to US$6.86 on Tuesday after Monday’s results. Revenue declined 2.4% to US$544.1mn, comparable sales fell 2.9%, and adjusted EBITDA dropped to US$98.9mn from US$129.8mn. An adjusted loss of US$0.27 per share replaced a US$0.40 profit. Recent sales improvement has yet to restore profitability, explaining the concern behind the decline from US$8.47. (Company / Market data)
Vera Bradley’s turnaround gains traction, with a refund caveat. Vera Bradley (VRA US) rose 34.54% to US$4.09 on Tuesday after quarterly revenue increased 1.1% to US$71.6mn and direct-channel comparable sales grew 9.2%. Adjusted EPS was US$0.11. Gross margin reached 59.8%, materially helped by US$7.7mn in tariff refunds. The rally from US$3.04 accompanies operating progress, but the refund benefit should be separated from recurring improvement. (Company / Market data)
Waystar sale review raises consolidation possibilities. Waystar Holding (WAY US) is exploring options including a sale, Reuters reported Tuesday, citing seven people. Evercore and Barclays are advising, but the preliminary process may produce no transaction. EQT holds about 13%, according to LSEG data cited by Reuters. The review could test private buyers’ willingness to fund healthcare software after pressure on public-market valuations. (Reuters)
Vera’s kidney trial supports a full-approval filing. Vera Therapeutics (VERA US) said Trutakna met all prespecified endpoints in the 428-patient ORIGIN 3 final analysis. Over 104 weeks, annual kidney-function decline was 0.6 versus 5.6 mL/min/1.73m² with placebo; composite disease-progression hazard fell 76%. A supplemental US filing for full approval is planned in the fourth quarter. The results strengthen its regulatory case; full approval is still pending. (Vera filing)
Greater China
Trip.com (9961.HK) reports a loss after a regulatory charge. Results released at 06:00 SGT on 16 September showed quarterly revenue of RMB15.7bn, up 6%, but a RMB2.4bn net loss after a RMB5.2bn anti-monopoly penalty. Adjusted EBITDA slipped to RMB4.6bn from RMB4.9bn, while international-platform revenue grew more than 50%. International expansion supports growth, but compliance costs and softer transportation ticketing constrain the conversion of travel demand into earnings. (Trip.com) Trip.com (9961.HK) is our Core Recommendation.
CATL (300750.SZ) expands its venture investments. Tuesday filings disclosed RMB1.12bn committed by Ningbo Wending to a RMB5.77bn fund and RMB500mn from an affiliated enterprise to a RMB4.90bn fund. The respective interests are 19.4% and 10.2%, targeting new energy, AI and embodied intelligence. Internal funding broadens technology access, although registration remains outstanding and long holding periods and low liquidity constrain capital flexibility. (National Business Daily) CATL (300750.SZ) is our Core Recommendation.
Geely (0175.HK) and Renault deepen their Brazil partnership. Their joint operation announced another €319mn investment Tuesday, taking the total to €899mn. Geely EX2 production is planned for December 2026; its GEA platform will support a Renault electrified model in 2027. Existing factories and distribution accelerate Brazilian expansion and improve Renault’s capacity use amid intense European competition. (Reuters / Reuters) Geely Automobile (0175.HK) is our Core Recommendation.
Xingyun Technology (300209.SZ) lifts its server procurement ceiling. The board raised its 2026 server and component budget from RMB7bn to RMB20bn, subject to shareholder approval, using internal and external funds including leases. First-half revenue was only RMB254mn and attributable profit RMB12.0mn. The RMB13bn increase supports AI computing, but its scale relative to current operations heightens funding, borrowing-cost and execution risks. (National Business Daily)
Midea (0300.HK) prioritises robotics and overseas localisation. At Tuesday’s briefing, management reaffirmed second-half investment in robotics, new energy and overseas localisation. Own brands now exceed 50% of overseas smart-home revenue, with nearly 50,000 overseas staff at June-end. Previously reported first-half revenue rose 3.5% to RMB261.05bn and attributable profit 1.7% to RMB26.45bn. Diversification supports growth, but modest profit expansion highlights raw-material, currency and trade pressures. (Yicai) Midea (0300.HK) is our Core Recommendation.
China’s factory recovery outpaces household demand. August factory output rose 5.2% year on year, above July’s 4.5% and the 4.8% consensus. Retail sales increased just 0.4%, below July’s 0.6% and the 0.8% forecast. January–August investment fell 7.2%, including a 19.9% property decline. Tuesday’s data show stronger manufacturing supply than household demand, limiting the breadth of recovery. (Reuters)
Asia ex. China
SoftBank (9984 JP) rebounds as investors reassess AI spending. Shares rose about 7.5% in Tuesday’s completed Tokyo session after Monday’s approximately 10.7% fall. Reuters linked the rebound to reassessment of whether AI leaders’ warnings implied slower hyperscaler spending. Advantest and Tokyo Electron reversed early gains as oil and yields pressured the wider market. The selective recovery highlights infrastructure valuations’ sensitivity to changing capital-spending expectations. (Reuters / StockAnalysis)
Alphabet’s Google (GOOGL US) opens its Singapore Engineering Center. Tuesday’s new product hub is co-located with Southeast Asia’s first Google DeepMind research lab. Three workstreams cover agentic cloud infrastructure, enterprise frontier-model deployment and developer automation. Collaborations include multilingual AI with Grab and financial workflows with DBS. Building alongside customers may shorten deployment cycles and support Singapore’s enterprise-AI exports; no investment amount or headcount was disclosed. (Google Cloud) Alphabet (GOOGL US) is our Trading Buy.
Eco World leads bidding for a Singapore residential site. The Malaysian developer offered S$208.1mn, nearly S$1,612 per square foot per plot ratio, when Tuesday’s Lorong Puntong/Sin Ming Avenue tender closed. Seven bids were submitted; the leader was about 11% above the runner-up. The 99-year site allows about 140 homes. Small project size limits inventory exposure, but elevated land cost raises pressure on selling prices. (The Business Times)
India introduces fees on selected UPI merchant payments. Tuesday’s framework sets a 0.4% merchant fee above INR2,000, capped at INR300, from 15 October. Person-to-person transfers stay free; about 96% of merchant transactions are unaffected. Small merchants retain exemptions and designated sectors pay INR5. The fees fund infrastructure and security, with 5% earmarked for small-merchant adoption. Merchants cannot pass them to consumers. (Akashvani News / Upstox)
EMEA and Others
Trustpilot (TRST LN) falls as investors seek an upgrade. Shares closed Tuesday down 18.64% at 213.0p as unchanged guidance disappointed. First-half revenue rose 23% to US$151.4mn, but adjusted core profit of US$26.3mn missed the US$27mn estimate. Management retained high-teens constant-currency growth and a two-to-three percentage-point adjusted EBITDA-margin improvement target. A US$1.1mn statutory loss included one-off charges; strong sales failed to satisfy earnings expectations. (Reuters / StockAnalysis)
Santander (SAN SM) wins an appeal over legacy insurance costs. A London appeals court overturned a ruling requiring roughly £677mn including interest to be paid to AXA. The indemnity covered acts after 1 December 2000; Santander had said about 85% related to earlier policies. It expects repayment of a substantial majority. The ruling improves potential recovery, although Genworth is considering further appeal options, leaving litigation risk. (Reuters)
Acciona Energia (ANE SM) attracts a reported joint approach. EQT and Norges are pursuing a bid, competing with Ardian, according to Expansion’s Tuesday report cited by Reuters. The consortium would be roughly 75% EQT and 25% Norges. LSEG’s €11.9bn enterprise value includes debt and is not an agreed offer price. Reported management meetings suggest progress, but no transaction is agreed and the structure remains uncertain. (Reuters)
Deutz (DEZ GR) completes a €179mn equity raise. Tuesday’s announcement confirmed 15,263,810 shares placed at €11.70, raising about €179mn and expanding capital 10% to 167,901,915 shares. Pre-emption rights were excluded. The engine maker aims to strengthen capital and fund growth, with a six-month lock-up subject to exceptions. Additional cash improves flexibility, but the enlarged share count dilutes holders until investment contributes to earnings. (Deutz)
Airbus (AIR FP) sees resilient aircraft demand. At Tuesday’s Hong Kong briefing, management said geopolitical and supply-chain pressures had not softened demand; year-to-date deliveries rose 9%. Its 20-year forecast assigns roughly 45% of 42,000 new aircraft to Asia-Pacific, including 8,830 to China and 3,480 to India. Domestic traffic-growth assumptions of 4.7% and 9.3%, respectively, indicate resilient but uneven regional demand. (Reuters)
Traders’ corner
Our Technical View
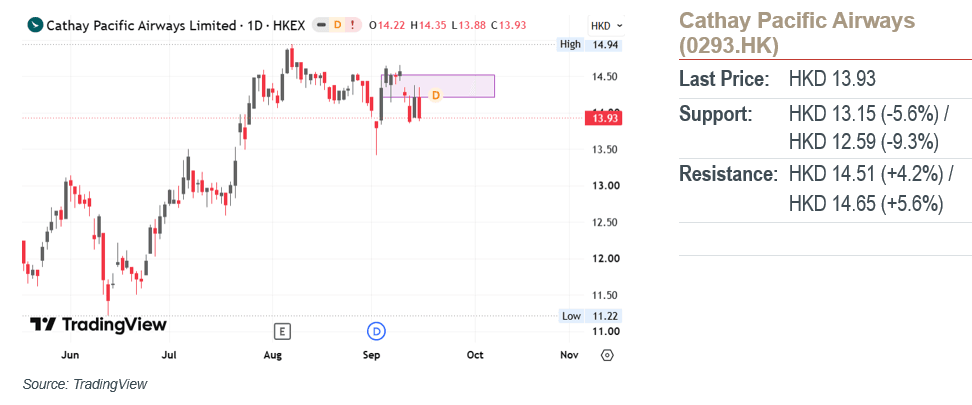
Price was capped by its gap resistance zone, establishing the lower boundary of the price void as a fortified supply ceiling.
The RSI continues to slope downward below its neutral 50-midline, accelerating trend velocity.
- As long as counter-trend rallies remain capped beneath this overhead gap resistance, we could expect a sustained downward trajectory toward lower support targets.
Our Technical View
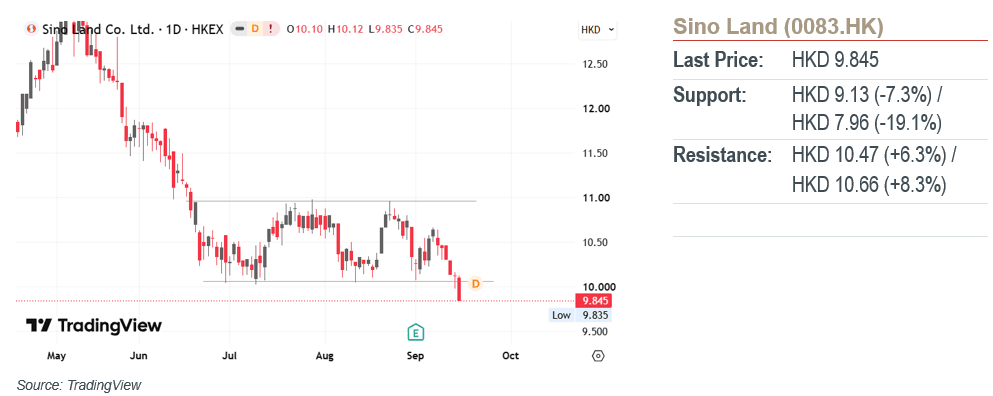
Price executed a decisive structural breakdown, penetrating a well-defined sideway consolidation zone that had constrained price discovery for nearly three months.
The RSI has turned bearish and is accelerating downward toward the oversold boundary.
As long as counter-trend rallies remain capped beneath this newly converted consolidation support-turned-resistance zone, path-of-least-resistance dynamics favours a sustained downward impulse wave toward deeper support targets.
Market Movers: Coinbase Global (COIN US) fell about 10.1% in Tuesday’s US session after the Senate failed to advance the Clarity Act, leaving a durable federal framework for digital assets unresolved. Enova International (ENVA US) lost about 23.4% in its first full session after Monday’s bank-deal application withdrawal, despite unchanged earnings guidance. The two moves show how shifts in regulation can outweigh near-term operating targets. OpenAI separately disclosed on Tuesday that it was working with Anthropic and Google DeepMind on AI safety. Talks had been under way for weeks; the fresh disclosure does not establish a binding pause or lower spending plans. Cooperation offers a possible route to shared safeguards, while its effect on the pace and cost of frontier development remains uncertain. (Reuters / Company / Bloomberg)
Macro: China’s August data showed a split recovery: factory output rose 5.2% year on year, but retail sales grew just 0.4% and January–August investment fell 7.2%. The gap points to stronger industrial supply than household demand, limiting the case for a broad recovery. Attention now turns to US retail sales at 20:30 SGT today and the Fed decision at 02:00 SGT on 17 September. The new projections will help frame the policy outlook as investors weigh growth against renewed energy costs. (Reuters / Census / Fed)
FICC: Tuesday’s oil settlements rose as shipping sources reported suspended Yanbu loadings and cancelled late-September cargoes. November Brent gained 2.90% to US$108.75/bbl and October WTI 4.38% to US$105.83/bbl, with US crude benefiting as refiners sought alternatives. The supply disruption raises input-cost risks even where demand remains soft. Tuesday’s US Treasury daily 10-year par yield rose 3.0bps from Monday’s 4.970% to 5.000%, lifting the discount rate facing long-duration assets. The combination keeps energy supply and the Fed’s inflation assessment central to the next session. (Reuters / US Treasury)
AI
Frontier labs disclose safety coordination. OpenAI said Tuesday it was working with Anthropic and Google DeepMind on AI safety. Executive Chris Lehane said talks had run for several weeks without requiring an antitrust waiver. The disclosure signals voluntary cooperation, establishing neither an agreed pause nor binding development limits. Its effect on model progress and computing expenditure remains uncertain. (Bloomberg)
Meta expands paid AI access across its social applications. Meta Platforms (META US) launched Meta One across Facebook, Instagram, WhatsApp and Meta AI on Tuesday. It reported over 50 features and 15 million subscriptions and trials. Paid bundles expand compute-intensive image and video tools while basic services stay free. This tests direct AI monetisation; subscriptions plus trials do not equal paying customers. (Company) Meta Platforms (META US) is our Core Recommendation.
Salesforce brings enterprise agents into everyday workflows. Salesforce (CRM US) unveiled AIforce at Dreamforce, connecting AI interfaces to CRM workflows within existing controls. Adecco announced Agentforce Coworker across over 40 countries and 27,000 employees, following British and French pilots. Earlier recruitment agents served ten countries representing half its revenue. Expansion tests whether adoption delivers productivity and recurring software demand. (Salesforce / Adecco)
Americas
Crypto legislation setback hits Coinbase. Coinbase Global (COIN US) fell 10.10% to US$172.11 in Tuesday’s US session after the Senate failed to advance the Clarity Act, which needed 60 votes. Without a federal digital-asset framework, exchanges remain more exposed to agency rulemaking and political or court challenges. The decline from Monday’s US$191.45 reflects regulatory repricing. (Reuters / Market data)
Enova reprices after its bank-acquisition route closes. Enova International (ENVA US) fell 23.43% to US$173.61 on Tuesday, reacting to Monday’s bank-acquisition application withdrawal. It reaffirmed 2026 revenue growth of 20–25% and adjusted EPS growth of 30–35%, and plans faster buybacks. The fall from US$226.72 shows unchanged guidance failed to offset the loss of the proposed Grasshopper banking structure. (Company / Market data)
Axon’s convertible financing weighs on shares. Axon Enterprise (AXON US) fell 9.81% to US$442.08 on Tuesday as it proposed US$1bn of zero-coupon September 2031 convertible notes, with a US$150mn option. Proceeds would fund capped calls and general corporate purposes, potentially acquisitions; conversion terms await pricing. Avoiding cash interest still introduces potential dilution and hedging effects despite planned mitigation. (Company / Market data)
Schwab records strong asset gathering in August. Charles Schwab (SCHW US) reported Tuesday that August core net new assets rose 46% annually to a record-for-August US$64.8bn. Client assets reached US$13.41trn, up 19% annually and 3% monthly; new accounts increased 11% to 424,000. Acquisition and engagement support fee and financing opportunities, although market appreciation differs from organic inflows. (Company)
Dave & Buster’s earnings reaction exposes margin pressure. Dave & Buster’s (PLAY US) fell 19.01% to US$6.86 on Tuesday after Monday’s results. Revenue declined 2.4% to US$544.1mn, comparable sales fell 2.9%, and adjusted EBITDA dropped to US$98.9mn from US$129.8mn. An adjusted loss of US$0.27 per share replaced a US$0.40 profit. Recent sales improvement has yet to restore profitability, explaining the concern behind the decline from US$8.47. (Company / Market data)
Vera Bradley’s turnaround gains traction, with a refund caveat. Vera Bradley (VRA US) rose 34.54% to US$4.09 on Tuesday after quarterly revenue increased 1.1% to US$71.6mn and direct-channel comparable sales grew 9.2%. Adjusted EPS was US$0.11. Gross margin reached 59.8%, materially helped by US$7.7mn in tariff refunds. The rally from US$3.04 accompanies operating progress, but the refund benefit should be separated from recurring improvement. (Company / Market data)
Waystar sale review raises consolidation possibilities. Waystar Holding (WAY US) is exploring options including a sale, Reuters reported Tuesday, citing seven people. Evercore and Barclays are advising, but the preliminary process may produce no transaction. EQT holds about 13%, according to LSEG data cited by Reuters. The review could test private buyers’ willingness to fund healthcare software after pressure on public-market valuations. (Reuters)
Vera’s kidney trial supports a full-approval filing. Vera Therapeutics (VERA US) said Trutakna met all prespecified endpoints in the 428-patient ORIGIN 3 final analysis. Over 104 weeks, annual kidney-function decline was 0.6 versus 5.6 mL/min/1.73m² with placebo; composite disease-progression hazard fell 76%. A supplemental US filing for full approval is planned in the fourth quarter. The results strengthen its regulatory case; full approval is still pending. (Vera filing)
Greater China
Trip.com (9961.HK) reports a loss after a regulatory charge. Results released at 06:00 SGT on 16 September showed quarterly revenue of RMB15.7bn, up 6%, but a RMB2.4bn net loss after a RMB5.2bn anti-monopoly penalty. Adjusted EBITDA slipped to RMB4.6bn from RMB4.9bn, while international-platform revenue grew more than 50%. International expansion supports growth, but compliance costs and softer transportation ticketing constrain the conversion of travel demand into earnings. (Trip.com) Trip.com (9961.HK) is our Core Recommendation.
CATL (300750.SZ) expands its venture investments. Tuesday filings disclosed RMB1.12bn committed by Ningbo Wending to a RMB5.77bn fund and RMB500mn from an affiliated enterprise to a RMB4.90bn fund. The respective interests are 19.4% and 10.2%, targeting new energy, AI and embodied intelligence. Internal funding broadens technology access, although registration remains outstanding and long holding periods and low liquidity constrain capital flexibility. (National Business Daily) CATL (300750.SZ) is our Core Recommendation.
Geely (0175.HK) and Renault deepen their Brazil partnership. Their joint operation announced another €319mn investment Tuesday, taking the total to €899mn. Geely EX2 production is planned for December 2026; its GEA platform will support a Renault electrified model in 2027. Existing factories and distribution accelerate Brazilian expansion and improve Renault’s capacity use amid intense European competition. (Reuters / Reuters) Geely Automobile (0175.HK) is our Core Recommendation.
Xingyun Technology (300209.SZ) lifts its server procurement ceiling. The board raised its 2026 server and component budget from RMB7bn to RMB20bn, subject to shareholder approval, using internal and external funds including leases. First-half revenue was only RMB254mn and attributable profit RMB12.0mn. The RMB13bn increase supports AI computing, but its scale relative to current operations heightens funding, borrowing-cost and execution risks. (National Business Daily)
Midea (0300.HK) prioritises robotics and overseas localisation. At Tuesday’s briefing, management reaffirmed second-half investment in robotics, new energy and overseas localisation. Own brands now exceed 50% of overseas smart-home revenue, with nearly 50,000 overseas staff at June-end. Previously reported first-half revenue rose 3.5% to RMB261.05bn and attributable profit 1.7% to RMB26.45bn. Diversification supports growth, but modest profit expansion highlights raw-material, currency and trade pressures. (Yicai) Midea (0300.HK) is our Core Recommendation.
China’s factory recovery outpaces household demand. August factory output rose 5.2% year on year, above July’s 4.5% and the 4.8% consensus. Retail sales increased just 0.4%, below July’s 0.6% and the 0.8% forecast. January–August investment fell 7.2%, including a 19.9% property decline. Tuesday’s data show stronger manufacturing supply than household demand, limiting the breadth of recovery. (Reuters)
Asia ex. China
SoftBank (9984 JP) rebounds as investors reassess AI spending. Shares rose about 7.5% in Tuesday’s completed Tokyo session after Monday’s approximately 10.7% fall. Reuters linked the rebound to reassessment of whether AI leaders’ warnings implied slower hyperscaler spending. Advantest and Tokyo Electron reversed early gains as oil and yields pressured the wider market. The selective recovery highlights infrastructure valuations’ sensitivity to changing capital-spending expectations. (Reuters / StockAnalysis)
Alphabet’s Google (GOOGL US) opens its Singapore Engineering Center. Tuesday’s new product hub is co-located with Southeast Asia’s first Google DeepMind research lab. Three workstreams cover agentic cloud infrastructure, enterprise frontier-model deployment and developer automation. Collaborations include multilingual AI with Grab and financial workflows with DBS. Building alongside customers may shorten deployment cycles and support Singapore’s enterprise-AI exports; no investment amount or headcount was disclosed. (Google Cloud) Alphabet (GOOGL US) is our Trading Buy.
Eco World leads bidding for a Singapore residential site. The Malaysian developer offered S$208.1mn, nearly S$1,612 per square foot per plot ratio, when Tuesday’s Lorong Puntong/Sin Ming Avenue tender closed. Seven bids were submitted; the leader was about 11% above the runner-up. The 99-year site allows about 140 homes. Small project size limits inventory exposure, but elevated land cost raises pressure on selling prices. (The Business Times)
India introduces fees on selected UPI merchant payments. Tuesday’s framework sets a 0.4% merchant fee above INR2,000, capped at INR300, from 15 October. Person-to-person transfers stay free; about 96% of merchant transactions are unaffected. Small merchants retain exemptions and designated sectors pay INR5. The fees fund infrastructure and security, with 5% earmarked for small-merchant adoption. Merchants cannot pass them to consumers. (Akashvani News / Upstox)
EMEA and Others
Trustpilot (TRST LN) falls as investors seek an upgrade. Shares closed Tuesday down 18.64% at 213.0p as unchanged guidance disappointed. First-half revenue rose 23% to US$151.4mn, but adjusted core profit of US$26.3mn missed the US$27mn estimate. Management retained high-teens constant-currency growth and a two-to-three percentage-point adjusted EBITDA-margin improvement target. A US$1.1mn statutory loss included one-off charges; strong sales failed to satisfy earnings expectations. (Reuters / StockAnalysis)
Santander (SAN SM) wins an appeal over legacy insurance costs. A London appeals court overturned a ruling requiring roughly £677mn including interest to be paid to AXA. The indemnity covered acts after 1 December 2000; Santander had said about 85% related to earlier policies. It expects repayment of a substantial majority. The ruling improves potential recovery, although Genworth is considering further appeal options, leaving litigation risk. (Reuters)
Acciona Energia (ANE SM) attracts a reported joint approach. EQT and Norges are pursuing a bid, competing with Ardian, according to Expansion’s Tuesday report cited by Reuters. The consortium would be roughly 75% EQT and 25% Norges. LSEG’s €11.9bn enterprise value includes debt and is not an agreed offer price. Reported management meetings suggest progress, but no transaction is agreed and the structure remains uncertain. (Reuters)
Deutz (DEZ GR) completes a €179mn equity raise. Tuesday’s announcement confirmed 15,263,810 shares placed at €11.70, raising about €179mn and expanding capital 10% to 167,901,915 shares. Pre-emption rights were excluded. The engine maker aims to strengthen capital and fund growth, with a six-month lock-up subject to exceptions. Additional cash improves flexibility, but the enlarged share count dilutes holders until investment contributes to earnings. (Deutz)
Airbus (AIR FP) sees resilient aircraft demand. At Tuesday’s Hong Kong briefing, management said geopolitical and supply-chain pressures had not softened demand; year-to-date deliveries rose 9%. Its 20-year forecast assigns roughly 45% of 42,000 new aircraft to Asia-Pacific, including 8,830 to China and 3,480 to India. Domestic traffic-growth assumptions of 4.7% and 9.3%, respectively, indicate resilient but uneven regional demand. (Reuters)
Traders’ corner
Our Technical View
Price was capped by its gap resistance zone, establishing the lower boundary of the price void as a fortified supply ceiling.
The RSI continues to slope downward below its neutral 50-midline, accelerating trend velocity.
- As long as counter-trend rallies remain capped beneath this overhead gap resistance, we could expect a sustained downward trajectory toward lower support targets.
Our Technical View
Price executed a decisive structural breakdown, penetrating a well-defined sideway consolidation zone that had constrained price discovery for nearly three months.
The RSI has turned bearish and is accelerating downward toward the oversold boundary.
As long as counter-trend rallies remain capped beneath this newly converted consolidation support-turned-resistance zone, path-of-least-resistance dynamics favours a sustained downward impulse wave toward deeper support targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


