Wealth Daily
AI Funding Strains Mount Amid Power Delays
Today’s Must-Know News
Overnight Markets
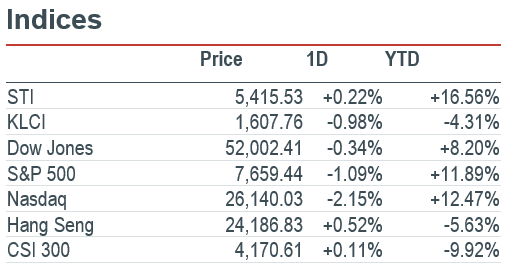
Market Movers: The S&P 500 fell 1.09% in Friday’s 16 October US session. CoreWeave (CRWV US) sank 11.91% amid AI financing concerns. A subsequent Saturday report said Anthropic offered Blackstone a yield above 10% on proposed chip financing. Indonesia’s benchmark plunged 11.57% after MSCI proposed removing its emerging-market status; reclassification remains subject to consultation. UBS estimated potential outflows of US$4bn from passive funds and US$15bn from active investors. A Sunday report said Microsoft (MSFT US) had withdrawn from Nscale’s Loughton data-centre project amid power-supply delays. Power availability was reportedly delayed until the 2030s; Nscale, with over US$103bn in contracted value, said other contracts were unaffected. Funding costs and electricity access are separate constraints on AI capacity delivery. (Reuters / Reuters / Reuters / Reuters / Market data / Market data) Microsoft (MSFT US) is our Core Recommendation.
Macro: US September import prices rose 1.1% month on month, versus 0.8% expected, and 8.1% YoY. The import index excludes tariffs and followed a revised 0.5% August rise. Industrial production increased 0.7% month on month and 2.2% YoY. Manufacturing output rose 0.3% month on month and 1.1% YoY, while total capacity utilisation reached 76.9%. Persistent imported inflation complicates the policy outlook despite firmer output. (Reuters / Federal Reserve)
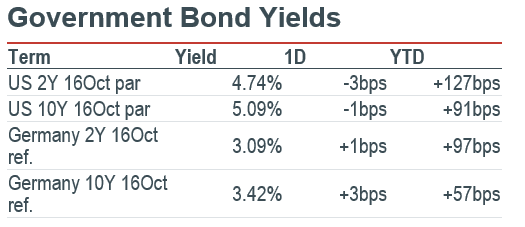
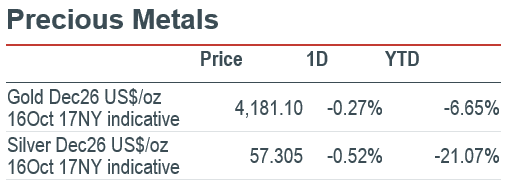
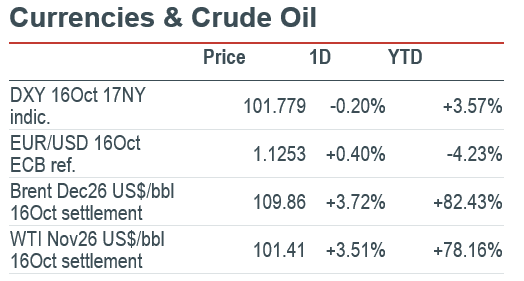
FICC: December Brent settled 3.72% higher at US$109.86/bbl and November WTI gained 3.51% to US$101.41 on 16 October, as Middle East and Russian supply concerns intensified. The US 10-year par yield eased 1bp to 5.09%. December gold slipped 0.27% at matched 17:00 New York indicative snapshots. Higher energy costs keep inflation risks elevated. (Reuters / US Treasury / Yahoo Finance)
AI
- Microsoft (MSFT US) highlights electricity constraints on AI expansion. Reuters reported on 18 October that Microsoft had withdrawn from Nscale’s Loughton agreement, where grid power was reportedly unavailable until the 2030s. Nscale said other Microsoft contracts were unaffected and it was exploring alternative power. The development underlines why contracted computing capacity still depends on sites becoming operational. (Reuters) Microsoft (MSFT US) is our Core Recommendation.
- AI financing costs sharpen the profitability test. Reuters reported on 17 October that Anthropic offered Blackstone yields above 10%, with US$9bn backed by five-year chip leases, citing the FT; the proposal was unconfirmed. Separately, CoreWeave (CRWV US) fell 11.91% on 16 October amid financing concerns. Expensive debt raises the cash-flow hurdle before infrastructure earnings mature. (Reuters / Reuters / Market data)
- China extends technology-export oversight. China proposed adding 40 technologies to its export-control catalogue on Friday, including 23 AI technologies covering models, agents and compute clusters. Interim registration applies immediately, while public-domain open-source technology is excluded. The proposal also covers biomedical and solar technology. Overseas licensing and technology transfers could face additional friction, although the proposed permanent restrictions remain subject to consultation. (MOFCOM / MOST / Reuters)
Americas
- Tesla (TSLA US) stretches the Roadster’s commercial timetable. The redesigned sports car, unveiled late on 15 October US time, targets production in 2028, versus the original 2020 ambition. Reservations require US$50,000 or US$250,000 deposits depending on variant. Shares closed 16 October down 2.13%. The engineering showcase renews attention, but execution and eventual delivery economics remain the more consequential tests. (Reuters / Market data)
- Apple (AAPL US) faces a supply test after foldable preorders. The US$1,999 iPhone Duo opened for orders on 16 October, with availability from 23 October. The Apple Post reported Apple’s description of extraordinary demand as delivery estimates extended into 2027. Premium pricing supports revenue potential, but waiting times alone cannot distinguish strong unit demand from constrained launch supply. (Apple / Apple / The Apple Post)
- Eli Lilly (LLY US) advances its oral obesity franchise in Europe. On 16 October EMA published its 15 October positive opinion for Foundayo in obesity and type 2 diabetes; European Commission authorisation remains outstanding. The drug generated US$98m in second-quarter sales following its April US launch. Oral dosing could broaden access, but reimbursement and uptake will determine commercial value. (EMA / Reuters) Eli Lilly (LLY US) is our Core Recommendation.
- Strategy (MSTR US) reprices the risk of losing index demand. Shares fell 9.56% on 16 October after MSCI’s 15 October rule change expanded exclusions for non-operating companies. Strategy faces potential removal, with the final list due on 11 November and implementation after 30 November’s close. A deletion could force benchmark-tracking sales, but inclusion on the preliminary list does not establish the final outcome. (MSCI / Reuters / Market data)
- Truist Financial (TFC US) shows why earnings adjustments need scrutiny. Third-quarter reported EPS fell to US$0.56 from US$1.04 a year earlier, while adjusted EPS rose 12% to US$1.16. The 16 October release included US$1.447bn of securities losses and loan-sale effects. These balance-sheet changes distort headline comparisons; improved adjusted earnings should be assessed alongside the economic cost of repositioning. (Truist / MarketReview)
Greater China
- Lenovo rebounds with Hong Kong equities. Lenovo (0992.HK) gained 8.01% to HK$28.06 at Friday's close, leading Hang Seng constituents as the benchmark rose 0.52%. The advance came during a broader recovery in technology shares. No independently verified company-specific operating announcement explains the move; investors should distinguish this sharp market repricing from evidence of stronger earnings, orders or customer spending commitments. (NewTimeSpace / Market data)
- Temu accepts tighter data controls. PDD Holdings' (PDD US) Temu agreed to pay Texas US$3m and restrict handling of shoppers' personal data in a settlement disclosed Friday. It must keep personal data on US servers and conduct annual independent product-safety testing. Temu admitted no wrongdoing. Compliance obligations and potential US$8m annual penalties for specified data-rule violations could raise the cost of US expansion. (Texas Attorney General / Reuters)
- China Resources Pharma secures onshore funding. China Resources Pharmaceutical (3320.HK) completed a RMB900m, three-year bond issue through its wholly owned holding subsidiary on Friday, according to NewTimeSpace's report of the company announcement. The coupon is 1.48%, with proceeds available for debt repayment, working capital and development. The financing supports liquidity, although the allocation between refinancing and investment will determine its effect on leverage. (NewTimeSpace)
Asia ex. China
- SoftBank explores a large security acquisition. SoftBank Group (9984.T) is considering buying Allied Universal in a transaction valued at about US$18bn, Reuters reported Friday. Discussions remain preliminary, with no final decision or agreed price. The security-services group could provide a setting for deploying robots to perform some tasks. The potential transaction extends SoftBank's automation ambitions, but financing terms and execution economics remain undisclosed. (Reuters)
- Indonesia faces a benchmark-access shock. Indonesia's Jakarta Composite fell 11.57% on Friday after MSCI proposed moving the market from Emerging to Standalone status, citing ownership transparency and trading concerns. The proposal remains under consultation, with a final decision expected by June 2027. Potential benchmark-linked selling raises funding and liquidity risks, while remediation of market-access concerns remains central to avoiding the proposed reclassification. (MSCI / Reuters)
- Haze scrutiny raises disclosure risks for plantations. First Resources (EB5.SI) fell 6.86% to S$3.80 on Friday as haze concerns pressured Singapore-listed plantations. SGX RegCo sought information on operational impacts, possible contributions and mitigation measures, warning of action over disclosure failures. First Resources was not among the seven companies receiving NEA preventive notices. The episode increases monitoring and disclosure demands without establishing responsibility for the fires. (The Business Times / The Edge Singapore / Market data)
EMEA and Others
- Franco-German proposal eases automaker compliance pressures. France and Germany agreed Friday to seek a 90% reduction in car emissions by 2035 versus 2021, without compensatory measures for the remaining 10%. The proposal opens a route for Britain to qualify under European local-content rules. Approval by other EU members and Parliament remains necessary. Reduced compliance costs could support automaker margins, while regulatory uncertainty still constrains investment planning. (Reuters)
Traders' Corner
Our Technical View
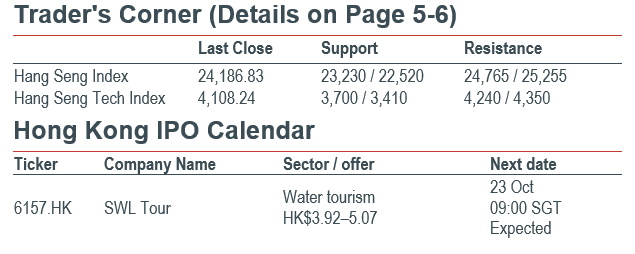
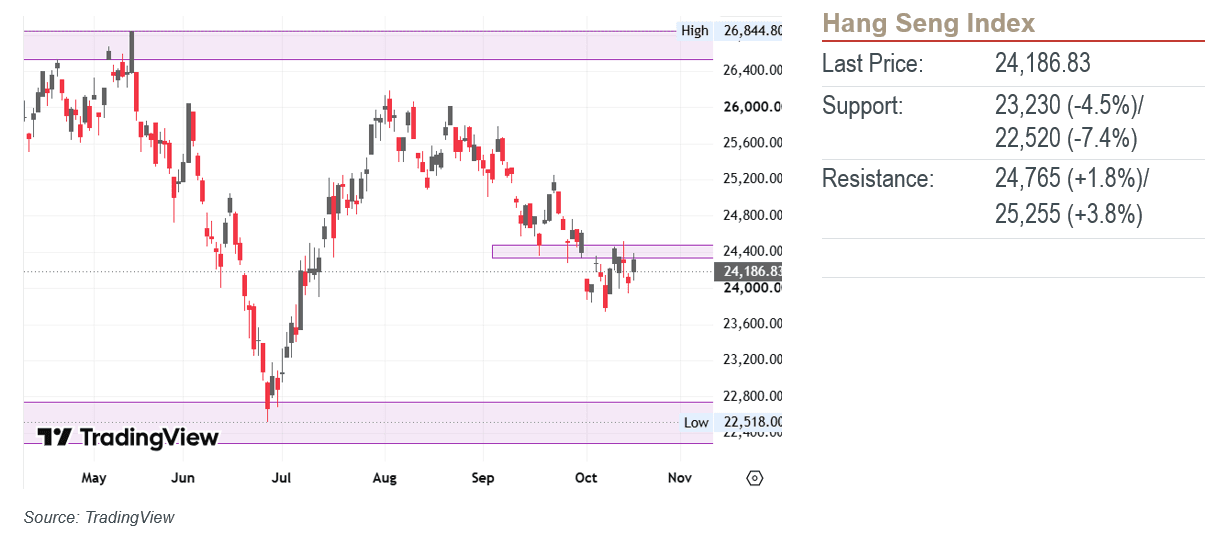
Weekly Chart: Price was rejected at the support-turned-resistance zone, reinforcing the lower-high and lower-low swing hierarchy. The RSI remains in bearish territory and continues to slope downward with negative velocity, signaling expanding sell-side momentum. As long as price strictly remains capped beneath this supply ceiling, we see continued downward expansion toward the primary support target zone at 22,520.
Daily Chart: Price was resisted at the support-turned-resistance zone, confirming the validity of the horizontal polarity flip. The failure of buyers to reclaim this converted supply ceiling validates persistent sell-side capping, sealing the former accumulation floor as an active overhead barrier. The RSI remains in bearish territory and continues to slope downward with negative velocity. As long as price remains capped beneath this supply ceiling, we could expect continued downward expansion toward the next support zone.
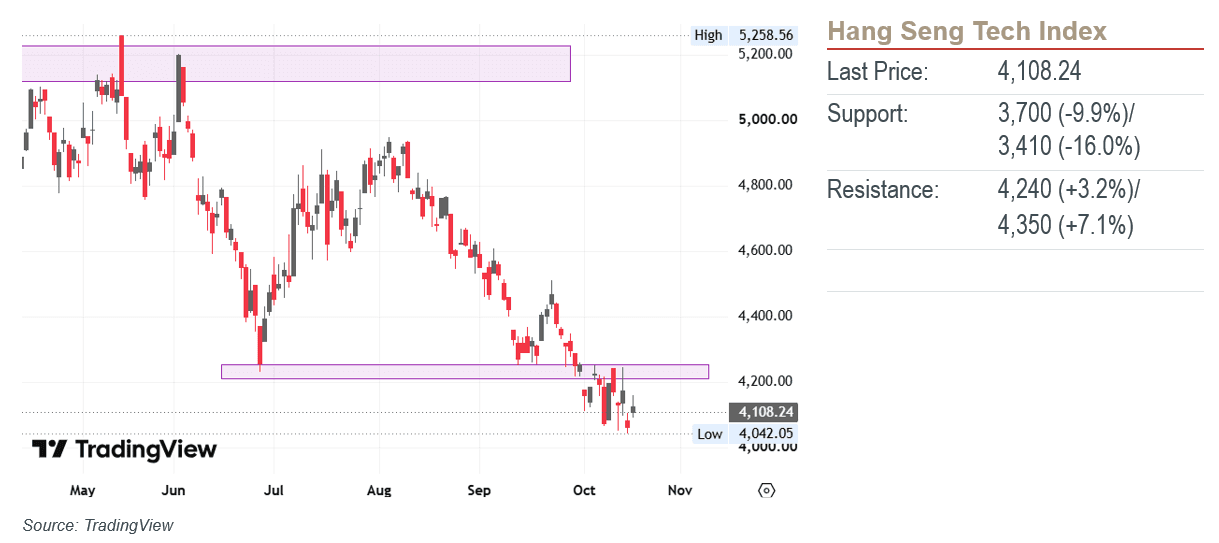
Our Technical View
Weekly Chart: Price was capped by its support-turned-resistance zone. The RSI remains in bearish territory and continues to slope downward with negative velocity, signaling expanding downside momentum. As long as price remains capped underneath this newly converted resistance ceiling, we see continued downward expansion toward deeper demand targets.
Daily Chart: Price was capped by its support-turned-resistance zone, confirming the structural validity of the horizontal polarity flip. Although the RSI shows a modest upward slope, it remains in bearish territory below its neutral 50-midline. As long as price remains capped underneath this newly converted resistance, we see continued downward expansion toward deeper demand targets.
Market Movers: The S&P 500 fell 1.09% in Friday’s 16 October US session. CoreWeave (CRWV US) sank 11.91% amid AI financing concerns. A subsequent Saturday report said Anthropic offered Blackstone a yield above 10% on proposed chip financing. Indonesia’s benchmark plunged 11.57% after MSCI proposed removing its emerging-market status; reclassification remains subject to consultation. UBS estimated potential outflows of US$4bn from passive funds and US$15bn from active investors. A Sunday report said Microsoft (MSFT US) had withdrawn from Nscale’s Loughton data-centre project amid power-supply delays. Power availability was reportedly delayed until the 2030s; Nscale, with over US$103bn in contracted value, said other contracts were unaffected. Funding costs and electricity access are separate constraints on AI capacity delivery. (Reuters / Reuters / Reuters / Reuters / Market data / Market data) Microsoft (MSFT US) is our Core Recommendation.
Macro: US September import prices rose 1.1% month on month, versus 0.8% expected, and 8.1% YoY. The import index excludes tariffs and followed a revised 0.5% August rise. Industrial production increased 0.7% month on month and 2.2% YoY. Manufacturing output rose 0.3% month on month and 1.1% YoY, while total capacity utilisation reached 76.9%. Persistent imported inflation complicates the policy outlook despite firmer output. (Reuters / Federal Reserve)
FICC: December Brent settled 3.72% higher at US$109.86/bbl and November WTI gained 3.51% to US$101.41 on 16 October, as Middle East and Russian supply concerns intensified. The US 10-year par yield eased 1bp to 5.09%. December gold slipped 0.27% at matched 17:00 New York indicative snapshots. Higher energy costs keep inflation risks elevated. (Reuters / US Treasury / Yahoo Finance)
AI
- Microsoft (MSFT US) highlights electricity constraints on AI expansion. Reuters reported on 18 October that Microsoft had withdrawn from Nscale’s Loughton agreement, where grid power was reportedly unavailable until the 2030s. Nscale said other Microsoft contracts were unaffected and it was exploring alternative power. The development underlines why contracted computing capacity still depends on sites becoming operational. (Reuters) Microsoft (MSFT US) is our Core Recommendation.
- AI financing costs sharpen the profitability test. Reuters reported on 17 October that Anthropic offered Blackstone yields above 10%, with US$9bn backed by five-year chip leases, citing the FT; the proposal was unconfirmed. Separately, CoreWeave (CRWV US) fell 11.91% on 16 October amid financing concerns. Expensive debt raises the cash-flow hurdle before infrastructure earnings mature. (Reuters / Reuters / Market data)
- China extends technology-export oversight. China proposed adding 40 technologies to its export-control catalogue on Friday, including 23 AI technologies covering models, agents and compute clusters. Interim registration applies immediately, while public-domain open-source technology is excluded. The proposal also covers biomedical and solar technology. Overseas licensing and technology transfers could face additional friction, although the proposed permanent restrictions remain subject to consultation. (MOFCOM / MOST / Reuters)
Americas
- Tesla (TSLA US) stretches the Roadster’s commercial timetable. The redesigned sports car, unveiled late on 15 October US time, targets production in 2028, versus the original 2020 ambition. Reservations require US$50,000 or US$250,000 deposits depending on variant. Shares closed 16 October down 2.13%. The engineering showcase renews attention, but execution and eventual delivery economics remain the more consequential tests. (Reuters / Market data)
- Apple (AAPL US) faces a supply test after foldable preorders. The US$1,999 iPhone Duo opened for orders on 16 October, with availability from 23 October. The Apple Post reported Apple’s description of extraordinary demand as delivery estimates extended into 2027. Premium pricing supports revenue potential, but waiting times alone cannot distinguish strong unit demand from constrained launch supply. (Apple / Apple / The Apple Post)
- Eli Lilly (LLY US) advances its oral obesity franchise in Europe. On 16 October EMA published its 15 October positive opinion for Foundayo in obesity and type 2 diabetes; European Commission authorisation remains outstanding. The drug generated US$98m in second-quarter sales following its April US launch. Oral dosing could broaden access, but reimbursement and uptake will determine commercial value. (EMA / Reuters) Eli Lilly (LLY US) is our Core Recommendation.
- Strategy (MSTR US) reprices the risk of losing index demand. Shares fell 9.56% on 16 October after MSCI’s 15 October rule change expanded exclusions for non-operating companies. Strategy faces potential removal, with the final list due on 11 November and implementation after 30 November’s close. A deletion could force benchmark-tracking sales, but inclusion on the preliminary list does not establish the final outcome. (MSCI / Reuters / Market data)
- Truist Financial (TFC US) shows why earnings adjustments need scrutiny. Third-quarter reported EPS fell to US$0.56 from US$1.04 a year earlier, while adjusted EPS rose 12% to US$1.16. The 16 October release included US$1.447bn of securities losses and loan-sale effects. These balance-sheet changes distort headline comparisons; improved adjusted earnings should be assessed alongside the economic cost of repositioning. (Truist / MarketReview)
Greater China
- Lenovo rebounds with Hong Kong equities. Lenovo (0992.HK) gained 8.01% to HK$28.06 at Friday's close, leading Hang Seng constituents as the benchmark rose 0.52%. The advance came during a broader recovery in technology shares. No independently verified company-specific operating announcement explains the move; investors should distinguish this sharp market repricing from evidence of stronger earnings, orders or customer spending commitments. (NewTimeSpace / Market data)
- Temu accepts tighter data controls. PDD Holdings' (PDD US) Temu agreed to pay Texas US$3m and restrict handling of shoppers' personal data in a settlement disclosed Friday. It must keep personal data on US servers and conduct annual independent product-safety testing. Temu admitted no wrongdoing. Compliance obligations and potential US$8m annual penalties for specified data-rule violations could raise the cost of US expansion. (Texas Attorney General / Reuters)
- China Resources Pharma secures onshore funding. China Resources Pharmaceutical (3320.HK) completed a RMB900m, three-year bond issue through its wholly owned holding subsidiary on Friday, according to NewTimeSpace's report of the company announcement. The coupon is 1.48%, with proceeds available for debt repayment, working capital and development. The financing supports liquidity, although the allocation between refinancing and investment will determine its effect on leverage. (NewTimeSpace)
Asia ex. China
- SoftBank explores a large security acquisition. SoftBank Group (9984.T) is considering buying Allied Universal in a transaction valued at about US$18bn, Reuters reported Friday. Discussions remain preliminary, with no final decision or agreed price. The security-services group could provide a setting for deploying robots to perform some tasks. The potential transaction extends SoftBank's automation ambitions, but financing terms and execution economics remain undisclosed. (Reuters)
- Indonesia faces a benchmark-access shock. Indonesia's Jakarta Composite fell 11.57% on Friday after MSCI proposed moving the market from Emerging to Standalone status, citing ownership transparency and trading concerns. The proposal remains under consultation, with a final decision expected by June 2027. Potential benchmark-linked selling raises funding and liquidity risks, while remediation of market-access concerns remains central to avoiding the proposed reclassification. (MSCI / Reuters)
- Haze scrutiny raises disclosure risks for plantations. First Resources (EB5.SI) fell 6.86% to S$3.80 on Friday as haze concerns pressured Singapore-listed plantations. SGX RegCo sought information on operational impacts, possible contributions and mitigation measures, warning of action over disclosure failures. First Resources was not among the seven companies receiving NEA preventive notices. The episode increases monitoring and disclosure demands without establishing responsibility for the fires. (The Business Times / The Edge Singapore / Market data)
EMEA and Others
- Franco-German proposal eases automaker compliance pressures. France and Germany agreed Friday to seek a 90% reduction in car emissions by 2035 versus 2021, without compensatory measures for the remaining 10%. The proposal opens a route for Britain to qualify under European local-content rules. Approval by other EU members and Parliament remains necessary. Reduced compliance costs could support automaker margins, while regulatory uncertainty still constrains investment planning. (Reuters)
Traders' Corner
Our Technical View
Weekly Chart: Price was rejected at the support-turned-resistance zone, reinforcing the lower-high and lower-low swing hierarchy. The RSI remains in bearish territory and continues to slope downward with negative velocity, signaling expanding sell-side momentum. As long as price strictly remains capped beneath this supply ceiling, we see continued downward expansion toward the primary support target zone at 22,520.
Daily Chart: Price was resisted at the support-turned-resistance zone, confirming the validity of the horizontal polarity flip. The failure of buyers to reclaim this converted supply ceiling validates persistent sell-side capping, sealing the former accumulation floor as an active overhead barrier. The RSI remains in bearish territory and continues to slope downward with negative velocity. As long as price remains capped beneath this supply ceiling, we could expect continued downward expansion toward the next support zone.
Our Technical View
Weekly Chart: Price was capped by its support-turned-resistance zone. The RSI remains in bearish territory and continues to slope downward with negative velocity, signaling expanding downside momentum. As long as price remains capped underneath this newly converted resistance ceiling, we see continued downward expansion toward deeper demand targets.
Daily Chart: Price was capped by its support-turned-resistance zone, confirming the structural validity of the horizontal polarity flip. Although the RSI shows a modest upward slope, it remains in bearish territory below its neutral 50-midline. As long as price remains capped underneath this newly converted resistance, we see continued downward expansion toward deeper demand targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


