Overnight Markets
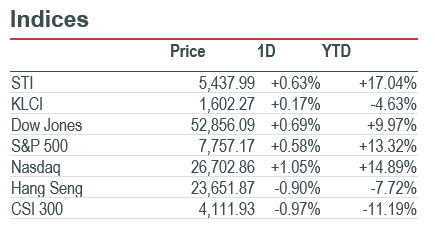
Market Movers: The S&P 500 rose 0.58% last night, driven by a broad rally in megacap growth stocks led by Nvidia (NVDA US) ahead of highly anticipated corporate earnings reports. SpaceX (SPCX US) gained 7.79% in its first cash-session reaction to 3Q revenue of US$14.6bn, up 161% YoY, and its first profit as a public company; merger discussions with Tesla (TSLA US) remain exploratory. SpaceX's AI revenue reached US$7.6bn, up 830% YoY, while quarterly capital spending of US$19.6bn exceeded group revenue. That spending burden keeps funding needs material despite the move into profit. Nvidia advanced 2.54% as it introduced modular AI factories designed to cut installation at prepared sites from six months to as little as 14 days. Seventeen infrastructure partners target deployment from early 2027; site power and financing remain execution constraints. CATL (300750.SZ) fell 12.03%, the first session after its 20 October earnings release showed 3Q net profit rising 14.5% YoY. The contrast keeps execution and earnings delivery central to technology valuations. (Reuters / SpaceX / Nvidia / CATL / Market data) Nvidia (NVDA US) and CATL (300750.SZ) are our Core Recommendations.
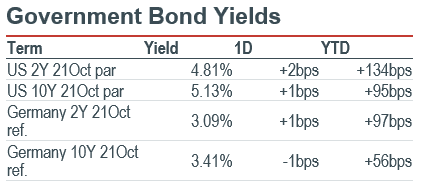
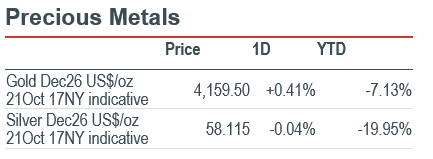
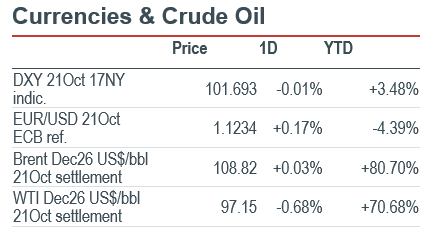
FICC: December Brent edged up 0.03% to US$108.82/bbl, while December WTI fell 0.68% to US$97.15/bbl. For the week to 16 October, US commercial crude stocks fell 3.1m barrels to 412.5m, but distillates rose 1.7m barrels, moderating the inventory signal. The U.S. Treasury 10-year par yield rose 1bp from the previous day's 5.12% to 5.13%, leaving financing costs elevated. (EIA / Hammerstone / U.S. Treasury)
AI
• SpaceX (SPCX US) rallies as AI revenue scales. Shares closed 7.8% higher after the prior evening’s results and merger comments. 3Q26 revenue rose 161% YoY to US$14.6bn, including AI revenue up 830% to US$7.6bn. Talks with Tesla remain preliminary. Quarterly capex of US$19.6bn underscores funding demands and makes any merger’s valuation and governance consequential. (SpaceX / Reuters / Reuters)
• Meta Platforms (META US) balances growth with heavier investment. 3Q26 revenue rose 26% YoY to US$64.6bn; operating profit fell 37% to US$13.0bn, including a US$9.89bn legal charge. FY26 capex narrowed to US$135–145bn from US$130–145bn. Conditional non-voting Class C stock adds funding options, while negative US$2.12bn quarterly free cash flow highlights investment demands. (Meta) Meta Platforms (META US) is our Core Recommendation.
• Nvidia (NVDA US) targets faster AI site deployment. DSX POD puts Vera Rubin computing, networks, power and cooling in factory-tested modules. Nvidia says installation at a prepared site can take just 14 days, versus six months. Seventeen partners plan deliveries from early 2027. Faster setup could cut delays, but sites still need grid power and other supporting infrastructure. (Nvidia) Nvidia (NVDA US) is our Core Recommendation.
• OpenAI helps contain critical PHP flaws. PHP maintainers fixed two flaws that could let attackers run code without logging in. OpenAI said Calif found one with its model; Wiz independently found both. Maintainers, cloud providers and government agencies coordinated the response. AI’s use by defenders and attackers makes prompt patching a growing operational priority. (OpenAI / PHP)
Americas
• Tesla (TSLA US) reports resilient sales but weaker profit. 3Q26 revenue was broadly flat YoY at US$28.05bn, while GAAP net income fell 43% to US$787m and adjusted EPS declined 4% to US$0.48. Deliveries fell 2% to 486,532. Capex more than doubled to US$4.73bn; free cash flow fell 62% to US$1.53bn. Autonomy investment must translate into durable earnings. (Tesla / Reuters)
• IBM (IBM US) lifts its cash-flow outlook. 3Q26 revenue rose 5% YoY to US$17.1bn and operating EPS increased 11% to US$2.95. Software grew 8%, including 11% at Red Hat, while consulting was flat. IBM maintained 4–5% constant-currency revenue growth guidance and now expects FY26 free cash flow to increase by more than US$1bn YoY. Growth remains uneven across divisions. (IBM)
• Lam Research (LRCX US) projects further equipment growth. September-quarter revenue rose 54% YoY to US$8.22bn, with adjusted EPS of US$2.20 and an adjusted operating margin of 40.2%. December revenue guidance was US$8.6bn, plus or minus US$400m, with adjusted EPS of US$2.33, plus or minus US$0.15. China represented 35% of revenue, leaving export-policy risk despite strong chip-equipment demand. (Lam Research)
• Netflix (NFLX US) falls on weaker ad expectations. Shares closed about 5.3% lower after the prior evening’s earnings. 3Q26 revenue rose 11.8% YoY to US$12.87bn, but FY26 ad revenue expectations fell to US$2.7bn from US$3bn as new tools rolled out slowly. 4Q26 EPS guidance was US$0.67, with a 26% operating margin. Monetisation remains the key growth challenge. (Netflix / Reuters)
• Texas Instruments (TXN US) sees broad demand recovery. 3Q26 revenue rose 28% YoY to US$6.06bn and EPS grew 77% to US$2.62, with gains across industrial, auto and data-centre markets. 4Q26 guidance was US$5.8–6.3bn revenue and US$2.45–2.79 EPS. Twelve-month operating cash flow rose 43% to US$9.90bn. Better demand supports plant use, though the sales outlook still allows a quarterly decline. (Texas Instruments)
• AT&T (T US) faces pressure from fibre discounts. Shares closed about 6.4% lower. Fibre revenue per user fell 4% YoY, with similar fourth-quarter pressure expected from discounts and customer mix. FY26 adjusted EPS guidance rose to about US$2.40 from US$2.25–2.35, mainly through lower depreciation on the Mexico business held for sale. Customer growth must improve unit economics. (Reuters / AT&T)
• Super Micro (SMCI US) raises its revenue estimate. Shares closed about 9.5% higher after the prior evening’s update. September-quarter sales were estimated at US$18.5–19.5bn versus US$15.23bn consensus; gross margin was 12–12.5%, versus prior 10.4–10.8% guidance. Stronger sales and margins support AI demand, but figures remain preliminary and customers must fund their new sites. (Reuters / Reuters / Supermicro filing)
• Philip Morris (PM US) flags cost pressure. FY26 adjusted EPS is now expected in the middle to lower half of US$8.29–8.44 guidance, due to conflict-related costs and higher US investment. Energy costs and Ukraine disruption weigh on earnings, while US Zyn shipments grew 4.2% YoY. Pouch competition and marketing costs temper cigarette-pricing gains, raising the importance of cost control. (Reuters / Philip Morris)
• Danaher (DHR US) raises its earnings forecast. 3Q26 revenue rose 8.5% YoY to US$6.6bn and adjusted EPS increased 11.5% to US$2.11. Core revenue grew 3%, or 5.5% excluding respiratory products. FY26 adjusted EPS guidance increased to US$8.57–8.62 from US$8.45–8.60. Respiratory products are expected to subtract 150bp from 4Q26 core growth, tempering an otherwise improving underlying demand picture. (Danaher)
Greater China
• CATL (300750.SZ) reprices on weaker profit growth. Shares fell 12.03% to RMB227.90 after the previous evening’s results. Q3 revenue rose 58.58% YoY to RMB165.22bn, but profit grew 14.54% to RMB21.25bn, below the 41.2% growth expected by LSEG SmartEstimate. Sales expansion must translate into stronger margins to rebuild confidence in the battery maker’s earnings. (HKEX / Reuters / Financial News / Market data) CATL (300750.SZ) is our Core Recommendation.
• China Mobile (0941.HK) faces an earnings reset. Shares fell 3.66% to HK$77.55 after the prior evening’s results. Nine-month revenue declined 1.8% YoY to RMB780.3bn and profit fell 7.9% to RMB106.2bn. Principal-business revenue dropped 3.7%; EBITDA fell 6.7%. Computing and AI services need to improve returns while the company stabilises its core communications business. (HKEX / Newsquawk / Market data) China Mobile (0941.HK) is our Core Recommendation.
• Montage Technology (6809.HK) profits from AI demand. Shares gained 8.97% after preliminary results. Expected 3Q revenue of RMB2.079bn rose 46.0% YoY; attributable profit of RMB1.2–1.3bn rose 153.6–174.7%. Management cited server-CPU demand from AI inference and agents, plus a richer DDR5 chip mix. The earnings outlook supports memory-connectivity exposure, although these remain unaudited estimates. (HKEX / NewTimeSpace / Market data) Montage Technology (6809.HK) is our Investment Opportunity.
Asia ex. China
• Samsung Electronics (005930.KS) upgrades Chinese NAND production. Samsung and SK Hynix (000660.KS; SKHY US) rose 5.67% and 5.81% after Reuters disclosed factory upgrades. Sources said Samsung targets 286-layer NAND. Both confirmed equipment work in consultation with Washington; Samsung denied capacity expansion. Greater density can reduce storage costs, but Reuters could not establish the full scope of US licences. (Reuters / Market data / Market data) SKHY is our Investment Opportunity.
EMEA and Others
• SAP (SAP.DE) sustains cloud expansion. Its results showed current cloud backlog of €24.1bn, up 28% YoY as reported and 26% at constant currencies. Cloud revenue grew 26%, total revenue 13%, and both IFRS and non-IFRS operating profit 18%. Cloud and AI migration support growth, but backlog must still convert into revenue and sustained cash generation. (SAP)
• EssilorLuxottica (EL.PA) rallies on core-business resilience. Shares jumped 15.48% after 3Q revenue reached €7.49bn, up 7.2% YoY at constant currencies and above €7.36bn consensus. Smart glasses growth slowed to 20% from nearly 100% in 2Q, but eyecare, eyewear and medtech grew over 6%. Traditional operations provide support as investors reassess expectations for smart glasses. (Reuters / Reuters / Market data)
• Randstad (RAND.AS) signals a hiring recovery. Shares surged 20.16% after 3Q organic revenue growth of 3.9% beat 2.9% consensus. Underlying EBITA reached €211m, up 10% organically YoY and above the €200m forecast. North American revenue grew 9%, while France fell 3%. Staffing demand signals cyclical improvement, but the uneven recovery limits extrapolation of profit growth. (Randstad / Reuters / Market data)
Traders' Corner
Our Technical View
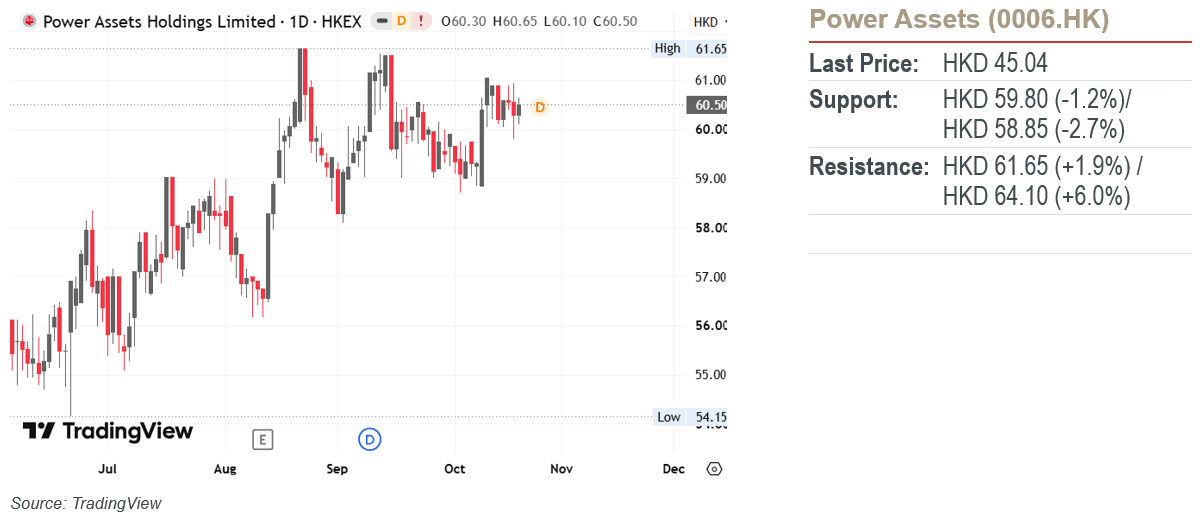
Price is currently bounded within a triangle consolidation, forming a localized bullish flag pattern that marks a high-tight volatility contraction following an initial primary mark-up impulse.
The RSI remains in bullish territory and is curling upward.
A decisive breakout above the triangle upper trendline will complete the continuation pattern, unlocking high-velocity upward movement toward overhead supply.
Our Technical View
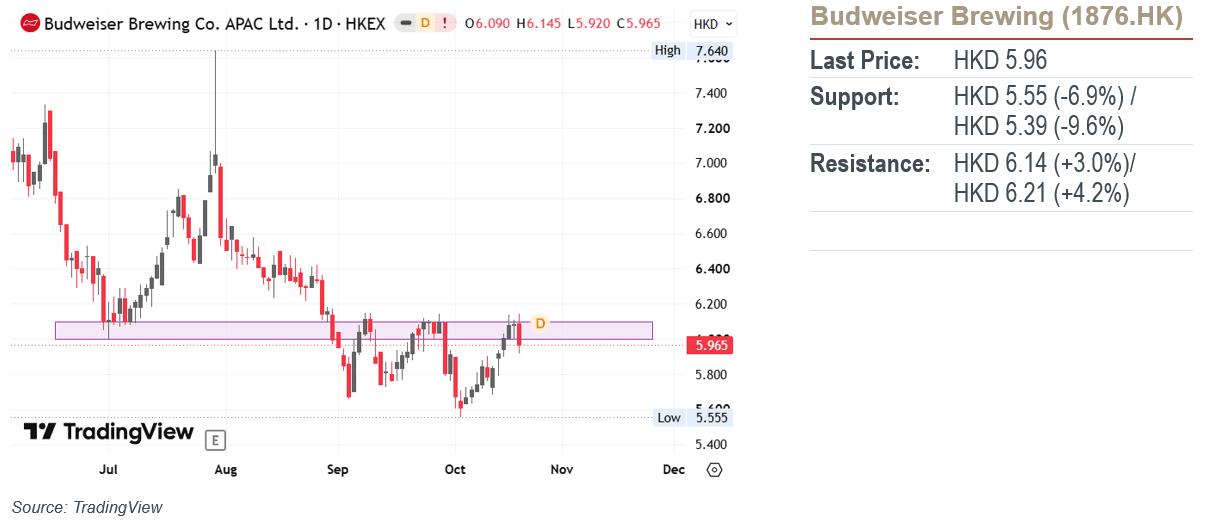
Price executed a secondary rejection at its prior resistance.
The RSI remains in bullish territory, its sharp downward hook from elevated levels signals an active momentum divergence and a rapid decay in buy-side velocity.
As long as price remains capped beneath this defended resistance ceiling on transient upward retests, we see a deeper downward retracement targeting lower downside.
Market Movers: The S&P 500 rose 0.58% last night, driven by a broad rally in megacap growth stocks led by Nvidia (NVDA US) ahead of highly anticipated corporate earnings reports. SpaceX (SPCX US) gained 7.79% in its first cash-session reaction to 3Q revenue of US$14.6bn, up 161% YoY, and its first profit as a public company; merger discussions with Tesla (TSLA US) remain exploratory. SpaceX's AI revenue reached US$7.6bn, up 830% YoY, while quarterly capital spending of US$19.6bn exceeded group revenue. That spending burden keeps funding needs material despite the move into profit. Nvidia advanced 2.54% as it introduced modular AI factories designed to cut installation at prepared sites from six months to as little as 14 days. Seventeen infrastructure partners target deployment from early 2027; site power and financing remain execution constraints. CATL (300750.SZ) fell 12.03%, the first session after its 20 October earnings release showed 3Q net profit rising 14.5% YoY. The contrast keeps execution and earnings delivery central to technology valuations. (Reuters / SpaceX / Nvidia / CATL / Market data) Nvidia (NVDA US) and CATL (300750.SZ) are our Core Recommendations.
FICC: December Brent edged up 0.03% to US$108.82/bbl, while December WTI fell 0.68% to US$97.15/bbl. For the week to 16 October, US commercial crude stocks fell 3.1m barrels to 412.5m, but distillates rose 1.7m barrels, moderating the inventory signal. The U.S. Treasury 10-year par yield rose 1bp from the previous day's 5.12% to 5.13%, leaving financing costs elevated. (EIA / Hammerstone / U.S. Treasury)
AI
• SpaceX (SPCX US) rallies as AI revenue scales. Shares closed 7.8% higher after the prior evening’s results and merger comments. 3Q26 revenue rose 161% YoY to US$14.6bn, including AI revenue up 830% to US$7.6bn. Talks with Tesla remain preliminary. Quarterly capex of US$19.6bn underscores funding demands and makes any merger’s valuation and governance consequential. (SpaceX / Reuters / Reuters)
• Meta Platforms (META US) balances growth with heavier investment. 3Q26 revenue rose 26% YoY to US$64.6bn; operating profit fell 37% to US$13.0bn, including a US$9.89bn legal charge. FY26 capex narrowed to US$135–145bn from US$130–145bn. Conditional non-voting Class C stock adds funding options, while negative US$2.12bn quarterly free cash flow highlights investment demands. (Meta) Meta Platforms (META US) is our Core Recommendation.
• Nvidia (NVDA US) targets faster AI site deployment. DSX POD puts Vera Rubin computing, networks, power and cooling in factory-tested modules. Nvidia says installation at a prepared site can take just 14 days, versus six months. Seventeen partners plan deliveries from early 2027. Faster setup could cut delays, but sites still need grid power and other supporting infrastructure. (Nvidia) Nvidia (NVDA US) is our Core Recommendation.
• OpenAI helps contain critical PHP flaws. PHP maintainers fixed two flaws that could let attackers run code without logging in. OpenAI said Calif found one with its model; Wiz independently found both. Maintainers, cloud providers and government agencies coordinated the response. AI’s use by defenders and attackers makes prompt patching a growing operational priority. (OpenAI / PHP)
Americas
• Tesla (TSLA US) reports resilient sales but weaker profit. 3Q26 revenue was broadly flat YoY at US$28.05bn, while GAAP net income fell 43% to US$787m and adjusted EPS declined 4% to US$0.48. Deliveries fell 2% to 486,532. Capex more than doubled to US$4.73bn; free cash flow fell 62% to US$1.53bn. Autonomy investment must translate into durable earnings. (Tesla / Reuters)
• IBM (IBM US) lifts its cash-flow outlook. 3Q26 revenue rose 5% YoY to US$17.1bn and operating EPS increased 11% to US$2.95. Software grew 8%, including 11% at Red Hat, while consulting was flat. IBM maintained 4–5% constant-currency revenue growth guidance and now expects FY26 free cash flow to increase by more than US$1bn YoY. Growth remains uneven across divisions. (IBM)
• Lam Research (LRCX US) projects further equipment growth. September-quarter revenue rose 54% YoY to US$8.22bn, with adjusted EPS of US$2.20 and an adjusted operating margin of 40.2%. December revenue guidance was US$8.6bn, plus or minus US$400m, with adjusted EPS of US$2.33, plus or minus US$0.15. China represented 35% of revenue, leaving export-policy risk despite strong chip-equipment demand. (Lam Research)
• Netflix (NFLX US) falls on weaker ad expectations. Shares closed about 5.3% lower after the prior evening’s earnings. 3Q26 revenue rose 11.8% YoY to US$12.87bn, but FY26 ad revenue expectations fell to US$2.7bn from US$3bn as new tools rolled out slowly. 4Q26 EPS guidance was US$0.67, with a 26% operating margin. Monetisation remains the key growth challenge. (Netflix / Reuters)
• Texas Instruments (TXN US) sees broad demand recovery. 3Q26 revenue rose 28% YoY to US$6.06bn and EPS grew 77% to US$2.62, with gains across industrial, auto and data-centre markets. 4Q26 guidance was US$5.8–6.3bn revenue and US$2.45–2.79 EPS. Twelve-month operating cash flow rose 43% to US$9.90bn. Better demand supports plant use, though the sales outlook still allows a quarterly decline. (Texas Instruments)
• AT&T (T US) faces pressure from fibre discounts. Shares closed about 6.4% lower. Fibre revenue per user fell 4% YoY, with similar fourth-quarter pressure expected from discounts and customer mix. FY26 adjusted EPS guidance rose to about US$2.40 from US$2.25–2.35, mainly through lower depreciation on the Mexico business held for sale. Customer growth must improve unit economics. (Reuters / AT&T)
• Super Micro (SMCI US) raises its revenue estimate. Shares closed about 9.5% higher after the prior evening’s update. September-quarter sales were estimated at US$18.5–19.5bn versus US$15.23bn consensus; gross margin was 12–12.5%, versus prior 10.4–10.8% guidance. Stronger sales and margins support AI demand, but figures remain preliminary and customers must fund their new sites. (Reuters / Reuters / Supermicro filing)
• Philip Morris (PM US) flags cost pressure. FY26 adjusted EPS is now expected in the middle to lower half of US$8.29–8.44 guidance, due to conflict-related costs and higher US investment. Energy costs and Ukraine disruption weigh on earnings, while US Zyn shipments grew 4.2% YoY. Pouch competition and marketing costs temper cigarette-pricing gains, raising the importance of cost control. (Reuters / Philip Morris)
• Danaher (DHR US) raises its earnings forecast. 3Q26 revenue rose 8.5% YoY to US$6.6bn and adjusted EPS increased 11.5% to US$2.11. Core revenue grew 3%, or 5.5% excluding respiratory products. FY26 adjusted EPS guidance increased to US$8.57–8.62 from US$8.45–8.60. Respiratory products are expected to subtract 150bp from 4Q26 core growth, tempering an otherwise improving underlying demand picture. (Danaher)
Greater China
• CATL (300750.SZ) reprices on weaker profit growth. Shares fell 12.03% to RMB227.90 after the previous evening’s results. Q3 revenue rose 58.58% YoY to RMB165.22bn, but profit grew 14.54% to RMB21.25bn, below the 41.2% growth expected by LSEG SmartEstimate. Sales expansion must translate into stronger margins to rebuild confidence in the battery maker’s earnings. (HKEX / Reuters / Financial News / Market data) CATL (300750.SZ) is our Core Recommendation.
• China Mobile (0941.HK) faces an earnings reset. Shares fell 3.66% to HK$77.55 after the prior evening’s results. Nine-month revenue declined 1.8% YoY to RMB780.3bn and profit fell 7.9% to RMB106.2bn. Principal-business revenue dropped 3.7%; EBITDA fell 6.7%. Computing and AI services need to improve returns while the company stabilises its core communications business. (HKEX / Newsquawk / Market data) China Mobile (0941.HK) is our Core Recommendation.
• Montage Technology (6809.HK) profits from AI demand. Shares gained 8.97% after preliminary results. Expected 3Q revenue of RMB2.079bn rose 46.0% YoY; attributable profit of RMB1.2–1.3bn rose 153.6–174.7%. Management cited server-CPU demand from AI inference and agents, plus a richer DDR5 chip mix. The earnings outlook supports memory-connectivity exposure, although these remain unaudited estimates. (HKEX / NewTimeSpace / Market data) Montage Technology (6809.HK) is our Investment Opportunity.
Asia ex. China
• Samsung Electronics (005930.KS) upgrades Chinese NAND production. Samsung and SK Hynix (000660.KS; SKHY US) rose 5.67% and 5.81% after Reuters disclosed factory upgrades. Sources said Samsung targets 286-layer NAND. Both confirmed equipment work in consultation with Washington; Samsung denied capacity expansion. Greater density can reduce storage costs, but Reuters could not establish the full scope of US licences. (Reuters / Market data / Market data) SKHY is our Investment Opportunity.
EMEA and Others
• SAP (SAP.DE) sustains cloud expansion. Its results showed current cloud backlog of €24.1bn, up 28% YoY as reported and 26% at constant currencies. Cloud revenue grew 26%, total revenue 13%, and both IFRS and non-IFRS operating profit 18%. Cloud and AI migration support growth, but backlog must still convert into revenue and sustained cash generation. (SAP)
• EssilorLuxottica (EL.PA) rallies on core-business resilience. Shares jumped 15.48% after 3Q revenue reached €7.49bn, up 7.2% YoY at constant currencies and above €7.36bn consensus. Smart glasses growth slowed to 20% from nearly 100% in 2Q, but eyecare, eyewear and medtech grew over 6%. Traditional operations provide support as investors reassess expectations for smart glasses. (Reuters / Reuters / Market data)
• Randstad (RAND.AS) signals a hiring recovery. Shares surged 20.16% after 3Q organic revenue growth of 3.9% beat 2.9% consensus. Underlying EBITA reached €211m, up 10% organically YoY and above the €200m forecast. North American revenue grew 9%, while France fell 3%. Staffing demand signals cyclical improvement, but the uneven recovery limits extrapolation of profit growth. (Randstad / Reuters / Market data)
Traders' Corner
Our Technical View
Price is currently bounded within a triangle consolidation, forming a localized bullish flag pattern that marks a high-tight volatility contraction following an initial primary mark-up impulse.
The RSI remains in bullish territory and is curling upward.
A decisive breakout above the triangle upper trendline will complete the continuation pattern, unlocking high-velocity upward movement toward overhead supply.
Our Technical View
Price executed a secondary rejection at its prior resistance.
The RSI remains in bullish territory, its sharp downward hook from elevated levels signals an active momentum divergence and a rapid decay in buy-side velocity.
As long as price remains capped beneath this defended resistance ceiling on transient upward retests, we see a deeper downward retracement targeting lower downside.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


