

Initiation of coverage
Dusit Thani (DUSIT TB): Strong Short- And Medium-term Outlook On Business Turnaround
BUY (Initiation)
Current price:
Target price:
Upside:
Bt10.80
Bt13.50
+25.0%
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
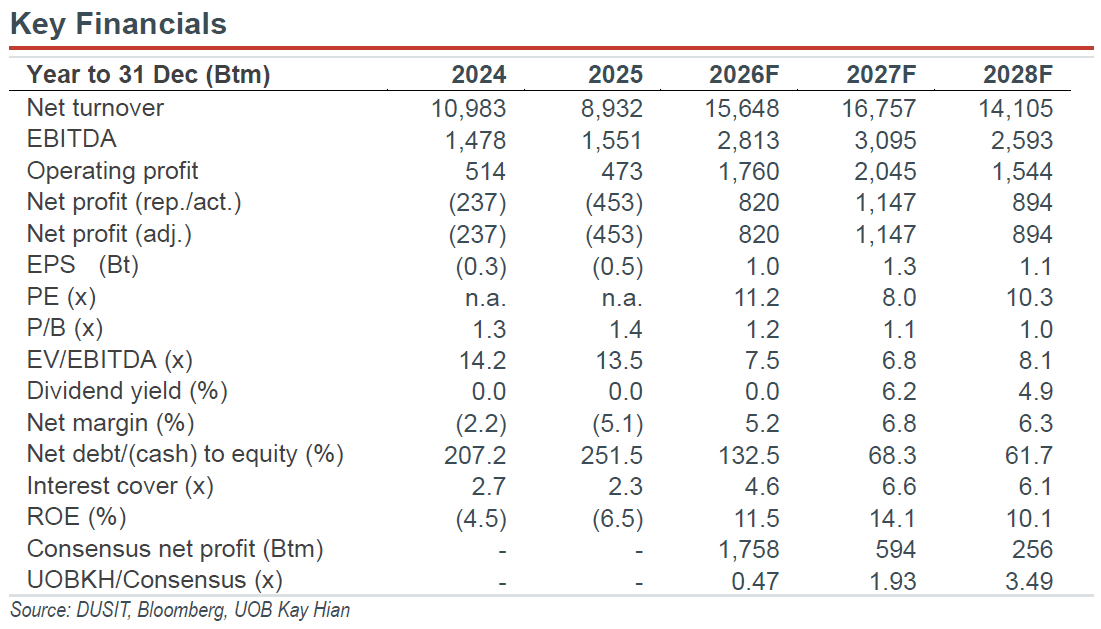
- We see strong earnings upside for DUSIT in the next three years as its hotel business has turned around after Dusit Thani Bangkok reopened in Sep 24.
- Revenue recognition from the transfer of Dusit Residences units will be a vital earnings contributor and will allow DUSIT to deleverage its project financing loans.
- Initiate coverage with a BUY recommendation and a target price of Bt13.50.
Analysis
- Stronger-than-expected performance of Dusit Thani Bangkok. Flagship hotel property Dusit Thani Bangkok’s occupancy reached 80% in Jul-Aug 26, above the 74-76% target, prompting Dusit Thani (DUSIT) to raise its RevPar growth target to 75-80% yoy from 45-50%. The strong bookings and premium positioning should bolster room revenue and margins, with average daily rate reaching Bt10,000 in Jul 26 vs Bt3,000-4,000 before renovations began 5-6 years ago. We see earnings upside from the hotel’s strong ramp-up.
- Recognition of revenue from Dusit Residences. With 97% of Dusit Residences units sold as of 2Q26, transfers are progressing, reaching 14% of the Bt17.6b project value. We expect transfer progress to reach 40% by end-26 and 80% by end-27, with full completion by 2028. The accelerated recognition of residence sales should provide a significant earnings uplift, particularly in 2027, while the high-margin nature of the project should support profitability, strengthening DUSIT’s financial position.
- Growth opportunities in bilingual school catering. Subsidiary Epicure Catering’s new international school contracts continue to drive meal volume growth, while expansion into Thailand’s more than 630 bilingual schools offers an untapped market to broaden its customer base and support recurring catering revenue.
- Valuation. We recommend BUY with a target price of Bt13.50. We roll over our valuation to 2027 and apply a 1.1x P/BV, around 1SD below the five-year historical mean. DUSIT currently trades at 0.8x P/BV, a 51% discount to peers and around -1.5SD below its five-year mean, offering an attractive entry point. We see strong earnings growth potential from the rapid ramp-up of Dusit Thani Bangkok and recognition of revenue from Dusit Residences, with 2027 expected to mark a significant earnings turnaround..
Highlights
- We see strong earnings upside for DUSIT in the next three years as its hotel business has turned around after Dusit Thani Bangkok reopened in Sep 24.
- Revenue recognition from the transfer of Dusit Residences units will be a vital earnings contributor and will allow DUSIT to deleverage its project financing loans.
- Initiate coverage with a BUY recommendation and a target price of Bt13.50.
Analysis
- Stronger-than-expected performance of Dusit Thani Bangkok. Flagship hotel property Dusit Thani Bangkok’s occupancy reached 80% in Jul-Aug 26, above the 74-76% target, prompting Dusit Thani (DUSIT) to raise its RevPar growth target to 75-80% yoy from 45-50%. The strong bookings and premium positioning should bolster room revenue and margins, with average daily rate reaching Bt10,000 in Jul 26 vs Bt3,000-4,000 before renovations began 5-6 years ago. We see earnings upside from the hotel’s strong ramp-up.
- Recognition of revenue from Dusit Residences. With 97% of Dusit Residences units sold as of 2Q26, transfers are progressing, reaching 14% of the Bt17.6b project value. We expect transfer progress to reach 40% by end-26 and 80% by end-27, with full completion by 2028. The accelerated recognition of residence sales should provide a significant earnings uplift, particularly in 2027, while the high-margin nature of the project should support profitability, strengthening DUSIT’s financial position.
- Growth opportunities in bilingual school catering. Subsidiary Epicure Catering’s new international school contracts continue to drive meal volume growth, while expansion into Thailand’s more than 630 bilingual schools offers an untapped market to broaden its customer base and support recurring catering revenue.
- Valuation. We recommend BUY with a target price of Bt13.50. We roll over our valuation to 2027 and apply a 1.1x P/BV, around 1SD below the five-year historical mean. DUSIT currently trades at 0.8x P/BV, a 51% discount to peers and around -1.5SD below its five-year mean, offering an attractive entry point. We see strong earnings growth potential from the rapid ramp-up of Dusit Thani Bangkok and recognition of revenue from Dusit Residences, with 2027 expected to mark a significant earnings turnaround..
BUY (Initiation)
Current price:
Target price:
Upside:
Bt10.80
Bt13.50
+25.0%
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
