

Company Coverage
Thai Union Group (TU TB) - 3Q26 Results Preview: Core Operation To Improve
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt12.40
Bt14.50
+16.93%
Bt13.30
Analyst
Highlights
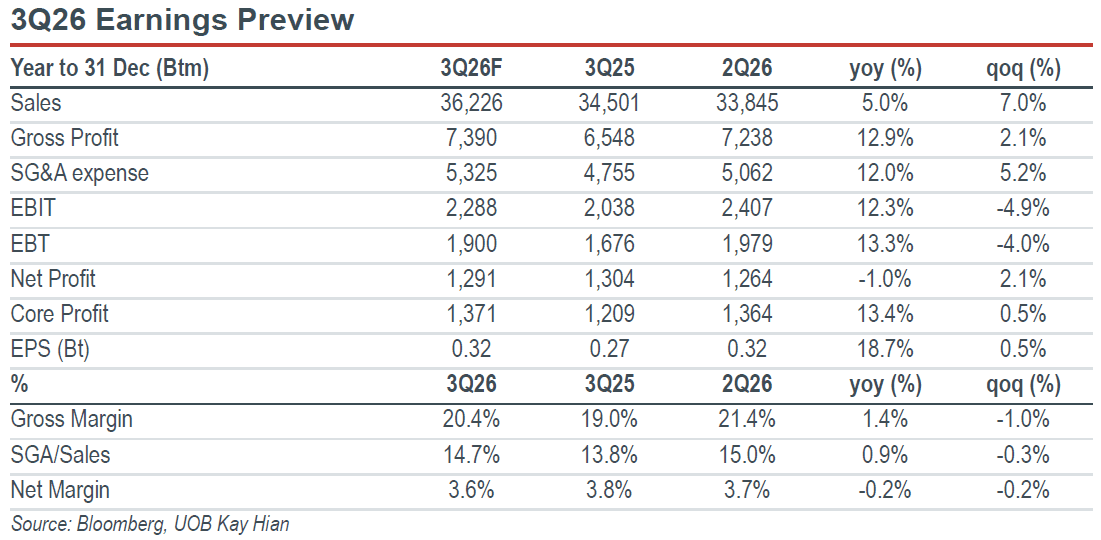
- We expect TU to report a 3Q26 core profit of Bt1.37b (+13.4% yoy, flat qoq), with core operations remaining resilient despite higher cost impact.
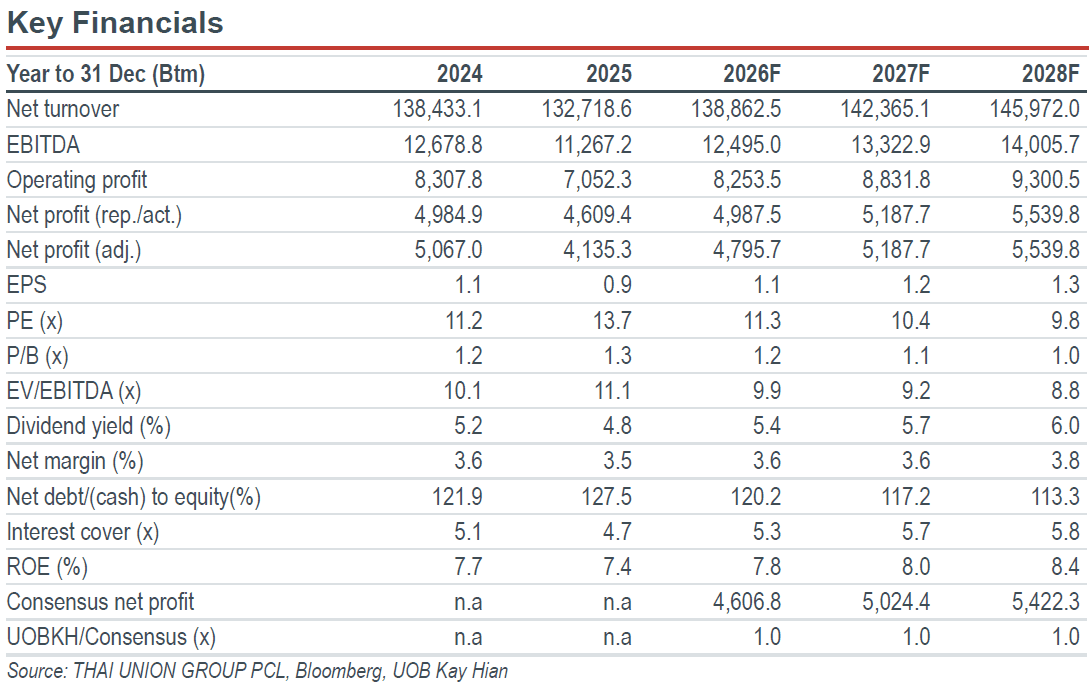
- Look ahead, we expect TU’s operations to improve in 2027F, on better operating margins following price adjustments, easing cost pressures, and Thai baht depreciation.
- Upgrade to BUY with a higher target price of Bt14.50.
Analysis
- 3Q26 earnings better than our previous projection. We expect Thai Union Group (TU) to report a net profit of Bt1.3b in 3Q26 (-1% yoy, +2% qoq). Excluding forex impact, we estimate core profit at Bt1.37b, (+13.4% yoy, flat qoq).
- Slight pressure on gross profit margin. 3Q26 gross profit margin is expected at 20.4%, (down from 21.4% in 2Q26 but up from 19.0% in 3Q25). The qoq decline was due to higher raw material costs, particularly tuna prices. However, this was partly offset by higher ASPs, from stronger sales of premium products in the ambient segment.
Highlights
- We expect TU to report a 3Q26 core profit of Bt1.37b (+13.4% yoy, flat qoq), with core operations remaining resilient despite higher cost impact.
- Look ahead, we expect TU’s operations to improve in 2027F, on better operating margins following price adjustments, easing cost pressures, and Thai baht depreciation.
- Upgrade to BUY with a higher target price of Bt14.50.
Analysis
- 3Q26 earnings better than our previous projection. We expect Thai Union Group (TU) to report a net profit of Bt1.3b in 3Q26 (-1% yoy, +2% qoq). Excluding forex impact, we estimate core profit at Bt1.37b, (+13.4% yoy, flat qoq).
- Slight pressure on gross profit margin. 3Q26 gross profit margin is expected at 20.4%, (down from 21.4% in 2Q26 but up from 19.0% in 3Q25). The qoq decline was due to higher raw material costs, particularly tuna prices. However, this was partly offset by higher ASPs, from stronger sales of premium products in the ambient segment.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt12.40
Bt14.50
+16.93%
Bt13.30
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Our latest research

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

12 Oct 2026
