
Initiation of coverage
EGP Energy Corporation (EGX SP): Singapore’s T&D EPC Champion With Strong Orderbook Visibility
BUY
Current price:
Target price:
Upside:
S$0.73
S$0.92
25.8%
Analyst
Analyst
Highlights
- EGP is Singapore’s leading independent T&D EPC specialist with over 90 completed projects, 7.5x orderbook visibility (S$296.2m) and a 30-year track record backed by seasoned leadership and a strong regulatory moat.
- We expect its robust orderbook to drive a three-year earnings CAGR of 18% over 2025-28, supported by its key customer’s capex.
- Initiate coverage with BUY and a target price of S$0.92, pegged to 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average, with re-rating potential from strong contract wins and M&S growth.
Analysis
- Market leadership with strong regulatory moat. EGP Energy Corporation (EGP) commands 37.5% of Singapore’s switchgear market and holds one of only 16 BCA SY04 L6 Unlimited certifications, the highest qualification tier required by its key utility customer. We infer this customer to be Singapore’s national grid operator and sole addressable customer for transmission & distribution (T&D) engineering, procurement and construction (EPC) services. EGP’s 30-year relationship with the customer and zero reportable incidents across over 90 projects reinforce regulatory trust and customer stickiness. The L6 qualification held by EGP also requires over 15 years to attain, creating a significant barrier to entry.
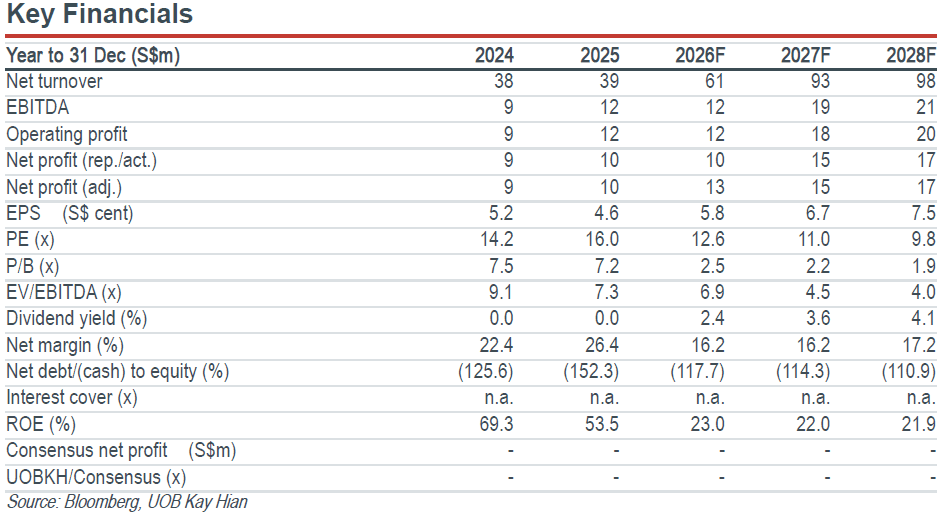
- Robust earnings visibility from S$296.2m orderbook. The contracted backlog represents 7.6x 2025 revenue and contracts up to 2031 provide EGP multi-year revenue visibility. Importantly, the key utility customer’s capex is legislatively mandated, eliminating cyclical demand risk. In our view, multi-year fixed-price contracts reduce execution risk, while project overruns of under 1% demonstrate operational excellence. Given EGP’s robust orderbook, we project a three-year earnings CAGR of 18% (2025-28).
- Superior unit economics and asset-light model. EGP’s 20.3% 2026 EBITDA margin is above the engineering, procurement, construction, and commissioning (EPCC) peer average of 15.2%, while capex is minimal at 2% of revenue. Its non-manufacturing asset-light model involves sourcing multi-OEM equipment, thus avoiding capex and working capital drag. Maintenance & servicing (M&S) contracts are recurring and generate robust 50% gross margins. We forecast margin accretion as this business segment expands.
- Initiate coverage with BUY and a target price of S$0.92, based on 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average. EGP currently trades at 11.0x 2027F PE, representing a discount to peers’ average, highlighting EGP’s undervaluation despite its strong market leadership backed by a robust orderbook.
Highlights
- EGP is Singapore’s leading independent T&D EPC specialist with over 90 completed projects, 7.5x orderbook visibility (S$296.2m) and a 30-year track record backed by seasoned leadership and a strong regulatory moat.
- We expect its robust orderbook to drive a three-year earnings CAGR of 18% over 2025-28, supported by its key customer’s capex.
- Initiate coverage with BUY and a target price of S$0.92, pegged to 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average, with re-rating potential from strong contract wins and M&S growth.
Analysis
- Market leadership with strong regulatory moat. EGP Energy Corporation (EGP) commands 37.5% of Singapore’s switchgear market and holds one of only 16 BCA SY04 L6 Unlimited certifications, the highest qualification tier required by its key utility customer. We infer this customer to be Singapore’s national grid operator and sole addressable customer for transmission & distribution (T&D) engineering, procurement and construction (EPC) services. EGP’s 30-year relationship with the customer and zero reportable incidents across over 90 projects reinforce regulatory trust and customer stickiness. The L6 qualification held by EGP also requires over 15 years to attain, creating a significant barrier to entry.
- Robust earnings visibility from S$296.2m orderbook. The contracted backlog represents 7.6x 2025 revenue and contracts up to 2031 provide EGP multi-year revenue visibility. Importantly, the key utility customer’s capex is legislatively mandated, eliminating cyclical demand risk. In our view, multi-year fixed-price contracts reduce execution risk, while project overruns of under 1% demonstrate operational excellence. Given EGP’s robust orderbook, we project a three-year earnings CAGR of 18% (2025-28).
- Superior unit economics and asset-light model. EGP’s 20.3% 2026 EBITDA margin is above the engineering, procurement, construction, and commissioning (EPCC) peer average of 15.2%, while capex is minimal at 2% of revenue. Its non-manufacturing asset-light model involves sourcing multi-OEM equipment, thus avoiding capex and working capital drag. Maintenance & servicing (M&S) contracts are recurring and generate robust 50% gross margins. We forecast margin accretion as this business segment expands.
- Initiate coverage with BUY and a target price of S$0.92, based on 13.8x 2027F PE, in line with the Southeast Asia EPCC peer average. EGP currently trades at 11.0x 2027F PE, representing a discount to peers’ average, highlighting EGP’s undervaluation despite its strong market leadership backed by a robust orderbook.
BUY
Current price:
Target price:
Upside:
S$0.73
S$0.92
25.8%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


