

Periodic/Sector reports
Property: New-home Sales Improve In September
Highlights
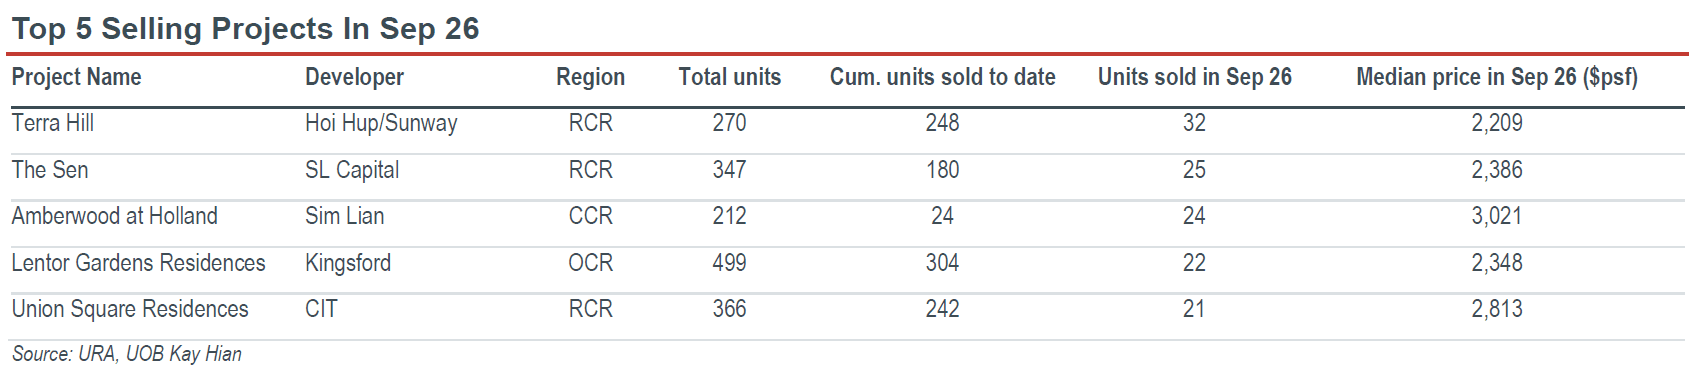
- Home sales rose yoy and mom in Sep 26. While new launch activity remained slow in the month of September, new-home sales improved yoy and mom as buyers continued to pick up units from existing projects. Excluding executive condominiums (EC), primary home sales rose 16% yoy and 93% mom to 296 units in Sep 26, according to URA data. The top selling developments during the month were Terra Hill, Lentor Garden Residences and Union Square Residences. Amberwood at Holland, which was launched during the month, saw a modest take-up rate of 34%, with 24 of the 70 units launched sold. This was likely due to its larger-format units (three bedrooms and above) and higher absolute price quantum of S$2.5m and above per unit.
- OCR accounted for bulk of monthly home sales. Take-up in the Outside Central Region (OCR) made up 44% of total ex-EC sales, including 18 landed units at Luxus Hills taken up during the month. Rest of Central Region (RCR) transactions accounted for another 42% and Core Central Region sales took up the remaining 14%.
- URA residential price index flash estimate up 1.4% qoq in 3Q26. Meanwhile, private home prices grew 1.4% qoq in 3Q26, bringing 9M26 price appreciation to 2.8%. Meanwhile, HDB resale prices retraced 0.2% qoq in 3Q26, with prices declining 0.6% since end-25. units. Maintain OVERWEIGHT.
Analysis
- Maintain our forecasts of 8,000-9,000 home sales and… Excluding ECs, primary home sales in 9M26 of 5,343 units appear to be trailing slightly behind our projection of 8,000-9,000 units for 2026. However, we think sales could pick up in early 4Q26 with the roll-out of CIT’s Lucerne Grand in early October (350 of 570 units sold during the first weekend of marketing) and the upcoming launch of 1,268-unit Thomson Reserve in the second half of Oct 26.
- …2-3% price appreciation for 2026. The 2.8% price growth in 9M26 remains within our forecast growth range of 2-3% for the year. With the 3-month SORA continuing to tick up mom in Sep/Oct 26 amid rising land cost, we think buying sentiment is likely to be shaped by developers’ pricing strategy and absolute quantum affordability, in addition to location considerations.
Highlights
- Home sales rose yoy and mom in Sep 26. While new launch activity remained slow in the month of September, new-home sales improved yoy and mom as buyers continued to pick up units from existing projects. Excluding executive condominiums (EC), primary home sales rose 16% yoy and 93% mom to 296 units in Sep 26, according to URA data. The top selling developments during the month were Terra Hill, Lentor Garden Residences and Union Square Residences. Amberwood at Holland, which was launched during the month, saw a modest take-up rate of 34%, with 24 of the 70 units launched sold. This was likely due to its larger-format units (three bedrooms and above) and higher absolute price quantum of S$2.5m and above per unit.
- OCR accounted for bulk of monthly home sales. Take-up in the Outside Central Region (OCR) made up 44% of total ex-EC sales, including 18 landed units at Luxus Hills taken up during the month. Rest of Central Region (RCR) transactions accounted for another 42% and Core Central Region sales took up the remaining 14%.
- URA residential price index flash estimate up 1.4% qoq in 3Q26. Meanwhile, private home prices grew 1.4% qoq in 3Q26, bringing 9M26 price appreciation to 2.8%. Meanwhile, HDB resale prices retraced 0.2% qoq in 3Q26, with prices declining 0.6% since end-25. units. Maintain OVERWEIGHT.
Analysis
- Maintain our forecasts of 8,000-9,000 home sales and… Excluding ECs, primary home sales in 9M26 of 5,343 units appear to be trailing slightly behind our projection of 8,000-9,000 units for 2026. However, we think sales could pick up in early 4Q26 with the roll-out of CIT’s Lucerne Grand in early October (350 of 570 units sold during the first weekend of marketing) and the upcoming launch of 1,268-unit Thomson Reserve in the second half of Oct 26.
- …2-3% price appreciation for 2026. The 2.8% price growth in 9M26 remains within our forecast growth range of 2-3% for the year. With the 3-month SORA continuing to tick up mom in Sep/Oct 26 amid rising land cost, we think buying sentiment is likely to be shaped by developers’ pricing strategy and absolute quantum affordability, in addition to location considerations.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


Our latest research

15 Oct 2026
Banking: 3Q26 Results Preview: NIM Bottoming, While Net Interest Income Turns Around

12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships

1 Oct 2026