Periodic/Sector reports
REITs: Value Emerges With Expanded Yield Spread
OVERWEIGHT (Maintained)
Analyst
Highlights
- Social unrest and street protests have erupted across many cities in France and Italy. Ironically, 10-year government bond yields across the Eurozone have eased 19bp to 3.40% in October due to tightening of monetary policies by central banks and the pullback in AI funding.
- Yield spreads for S-REITs have expanded by 29bp to 4.06%, which is 2SD above long-term mean, as unit prices and 10Y Singapore bond yield pulled back concurrently in Oct 26. We cut DPU forecast for FLT by 1.5%, CLAS by 0.7%, KDCREIT by 0.3% and LREIT by 0.3% due to weakness in the euro.
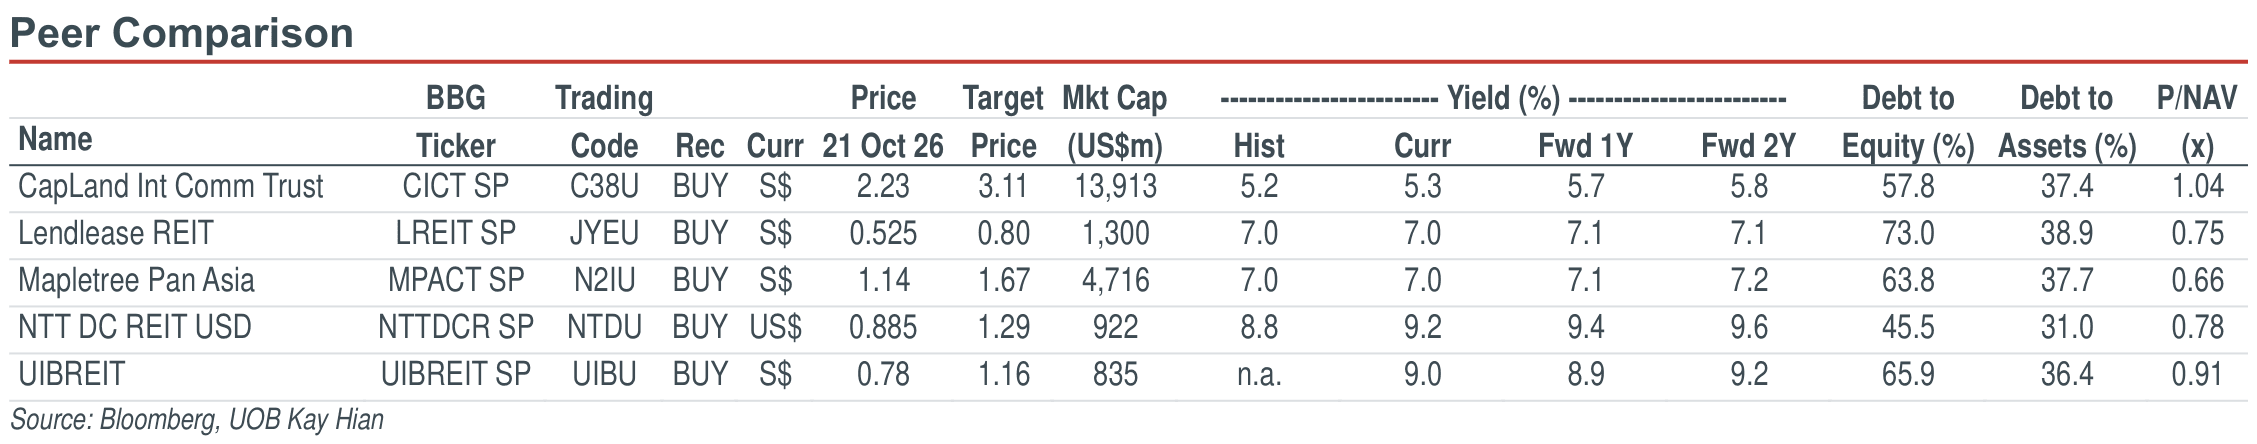
- Maintain OVERWEIGHT. S-REITs remain defensive and resilient. BUY CICT (Target: S$3.11), LREIT (Target: S$0.80), MPACT (Target: S$1.67), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16).
Analysis
- France trapped in a vicious cycle. France has been trapped in a political gridlock since the parliamentary election in mid-24 led to a split parliament. Prime Minister Sébastien Lecornu has struggled to secure parliamentary support for a 2027 budget seeking €54b in savings. France has the highest budget deficit at 5.5% of GDP in the Eurozone. Opposition to spending cuts has cast doubts on the government’s ability to deliver fiscal reforms. Thus, France’s 10-year government bond yield rose 139bp ytd to 4.95% in Oct 26, its highest level since 2002. The premium over German bonds has also widened sharply to 153bp. Student protests have erupted over underfunded schools. These pressures create a vicious cycle in which delays in deficit reduction and higher financing costs result in additional austerity, which fuels further social unrest.
- The UK has highest bond yield among G7 countries. The UK’s borrowing in the first five months of the financial year was £7b above the Office for Budget Responsibility’s forecast, including £2b in higher-than-expected debt interest. The rising government bond yields and increased debt-servicing costs have reduced room for additional spending in the budget to be unveiled in Oct 26. The government wants to help low-income households defray higher energy bills. To fund the higher expenditure, the Exchequer intends to raise the surcharge on banks’ profits, which affects the competitiveness of the financial services industry. The 10-year gilt yield rose 93bp ytd to 5.41% in Oct 26 due to higher energy prices and stretched public finances. Higher yields lead to higher mortgage and corporate borrowing costs, which weakens demand.
- The euro has weakened against the US dollar and Singapore dollar amid rising energy costs, concerns over France’s public finances and stronger demand for dollar assets. It depreciated 4.3% against the US dollar and 5.3% against the Singapore dollar on a ytd basis in Oct 26. Sentiment remains fragile due to fears of financial stress in France spreading across the Eurozone. Europe’s energy shock threatens growth and adds to inflation worries, outweighing support from the European Central Bank’s rate hikes. The weaker euro raises the cost of US dollar-denominated energy imports, complicating the ECB’s task of containing inflation and safeguarding financial stability.
Highlights
- Social unrest and street protests have erupted across many cities in France and Italy. Ironically, 10-year government bond yields across the Eurozone have eased 19bp to 3.40% in October due to tightening of monetary policies by central banks and the pullback in AI funding.
- Yield spreads for S-REITs have expanded by 29bp to 4.06%, which is 2SD above long-term mean, as unit prices and 10Y Singapore bond yield pulled back concurrently in Oct 26. We cut DPU forecast for FLT by 1.5%, CLAS by 0.7%, KDCREIT by 0.3% and LREIT by 0.3% due to weakness in the euro.
- Maintain OVERWEIGHT. S-REITs remain defensive and resilient. BUY CICT (Target: S$3.11), LREIT (Target: S$0.80), MPACT (Target: S$1.67), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16).
Analysis
- France trapped in a vicious cycle. France has been trapped in a political gridlock since the parliamentary election in mid-24 led to a split parliament. Prime Minister Sébastien Lecornu has struggled to secure parliamentary support for a 2027 budget seeking €54b in savings. France has the highest budget deficit at 5.5% of GDP in the Eurozone. Opposition to spending cuts has cast doubts on the government’s ability to deliver fiscal reforms. Thus, France’s 10-year government bond yield rose 139bp ytd to 4.95% in Oct 26, its highest level since 2002. The premium over German bonds has also widened sharply to 153bp. Student protests have erupted over underfunded schools. These pressures create a vicious cycle in which delays in deficit reduction and higher financing costs result in additional austerity, which fuels further social unrest.
- The UK has highest bond yield among G7 countries. The UK’s borrowing in the first five months of the financial year was £7b above the Office for Budget Responsibility’s forecast, including £2b in higher-than-expected debt interest. The rising government bond yields and increased debt-servicing costs have reduced room for additional spending in the budget to be unveiled in Oct 26. The government wants to help low-income households defray higher energy bills. To fund the higher expenditure, the Exchequer intends to raise the surcharge on banks’ profits, which affects the competitiveness of the financial services industry. The 10-year gilt yield rose 93bp ytd to 5.41% in Oct 26 due to higher energy prices and stretched public finances. Higher yields lead to higher mortgage and corporate borrowing costs, which weakens demand.
- The euro has weakened against the US dollar and Singapore dollar amid rising energy costs, concerns over France’s public finances and stronger demand for dollar assets. It depreciated 4.3% against the US dollar and 5.3% against the Singapore dollar on a ytd basis in Oct 26. Sentiment remains fragile due to fears of financial stress in France spreading across the Eurozone. Europe’s energy shock threatens growth and adds to inflation worries, outweighing support from the European Central Bank’s rate hikes. The weaker euro raises the cost of US dollar-denominated energy imports, complicating the ECB’s task of containing inflation and safeguarding financial stability.
OVERWEIGHT (Maintained)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

4 Sept 2026
REITs - 2Q26 Round-Up: Soldiering On With Resilient Yield

10 Sept 2026
REITs: New Normal Of Higher Bond Yields… Elsewhere

12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships
Our latest research

20 Oct 2026
Technology: Stay Selective On Stocks With High Yields And Strong Balance Sheets

16 Oct 2026
Property: New-home Sales Improve In September

15 Oct 2026