
Overnight Markets
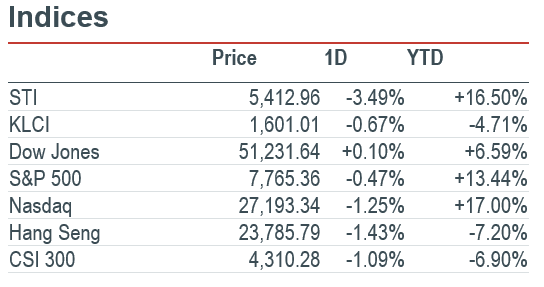
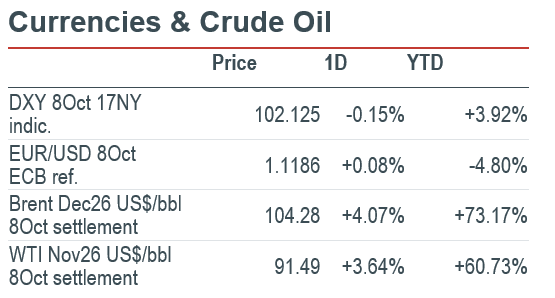
Market Movers: The S&P 500 fell 0.47% on Thursday, 8 October, as chip stocks weakened. Broadcom (AVGO US) declined 4.35% amid scrutiny of AI revenues and infrastructure financing. Wednesday’s report of US$50bn of proposed customer financing sharpened attention on how quickly AI spending converts into cash receipts. Alphabet (GOOGL US) slipped 0.63% as Google introduced a universal Gemini workplace agent spanning its software and third-party services. Google says nearly 80% of Cloud customers use its AI products, supporting enterprise monetisation. TSMC (TSM US) fell 3.01% despite September sales rising 54.6% YoY to NT$511.86bn. Third-quarter sales reached NT$1.49tn, up 50% YoY and above the NT$1.46tn consensus. Strong demand still faces demanding valuations and financing uncertainty. (Reuters / Google / TSMC / Reuters) Broadcom (AVGO US) & TSMC (TSM US) are our Core Recommendations; Alphabet (GOOGL US) is our Trading Buy.
Macro: US initial jobless claims eased to 197,000, down 2,000 from the revised prior week and 15.5% below the comparable year-earlier figure. Continuing claims rose 17,000 to 1.716mn. Low layoffs support household income, but rising continuing claims caution against inferring stronger hiring. (US Labor Department / Reuters)
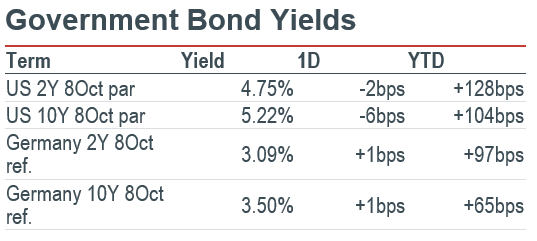
FICC: December Brent settled 4.07% higher at US$104.28/bbl; November WTI gained 3.64% to US$91.49/bbl. Middle East shipping risks and hurricane-related US Gulf shutdowns supported prices; diplomatic comments trimmed intraday gains. About 1.3mn barrels a day, or 62.9% of US Gulf output, was shut in, threatening fuel availability and transport costs. The US 10-year par yield fell 6bps to 5.22%. Dearer fuel raises cost pressures while lower yields partly ease financing conditions. (Reuters / US Treasury)
AI
Broadcom (AVGO US) fell 4.35% to US$360.14 in the 8 October US session. Reuters linked the decline to Wednesday’s report of US$50bn in planned OpenAI financing. CNBC reported during Thursday’s session that OpenAI’s September annualised revenue was about US$50bn; higher earlier figures included partners’ gross revenue. The accounting distinction complicates comparisons and sharpens scrutiny of infrastructure funding against cash generation. (Reuters / CNBC / Market data) Broadcom (AVGO US) is our Core Recommendation.
Alphabet (GOOGL US) introduced a universal Gemini work agent spanning Workspace, Microsoft 365 and Slack. Google said nearly 80% of Cloud customers use its AI; featured small and midsize customers’ AI-tool usage grew over fivefold YoY. Financial-services and legal versions are in preview. Wider workflow coverage intensifies enterprise-software competition. Alphabet’s 8 October US close was US$348.29, down 0.63%. (Google / Reuters / Market data) Alphabet (GOOGL US) is our Trading Buy.
Anthropic launched Claude Dashboards and Motion in beta, expanding into analytics and animation. Dashboards connects live business data and shows queries; Motion creates editable, code-based animations. Docs, Slides and Design became available across all plans. Anthropic said users had created over 45mn documents, decks and designs since launch. The expansion increases pressure on analytics and creative applications. (Anthropic / Reuters)
Nvidia (NVDA US) committed resources valued at US$1bn to US science over five years. The programme supports universities, quantum computing and cloud providers serving government missions. Nvidia also participates in new Genesis Mission projects covering fusion, accelerator design and microelectronics. The investment broadens its scientific-computing footprint and could extend demand beyond commercial AI models; associated customer orders or revenue were not quantified. (Nvidia) Nvidia (NVDA US) is our Core Recommendation.
Americas
Microsoft (MSFT US) faces a suspension of new and pending PERM permanent labour certifications. Reuters reported the action also covers Adobe and six IT-services companies, with no end date. Microsoft said about 80% of prior-year H-1B applications concerned existing employees’ extensions or status changes. Skilled-staff retention remains uncertain. Microsoft closed the 8 October US session at US$522.61, down 1.35%. (Reuters / Market data) Microsoft (MSFT US) is our Core Recommendation.
Palantir (PLTR US) gained 2.40% to US$198.78 in the 8 October US session. Goldman Sachs upgraded it from Neutral to Buy with a US$230 target, citing sovereign AI and specialised enterprise applications. Its thesis emphasises customer-facing engineers feeding implementation experience into product development. This could help defend differentiation as generic AI tools proliferate. (Reuters / Yahoo Finance / Market data)
Starbucks (SBUX US) has explored a Chipotle takeover. Reuters said it had worked with advisers in recent months; no agreed deal was announced. In the 8 October US session, Chipotle (CMG US) gained 6.21% to US$32.68 and Starbucks fell 0.40% to US$93.21. The reported exploration raises financing and management-capacity questions while Starbucks pursues its turnaround. (Reuters / Market data / Market data)
PepsiCo (PEP US) gained 3.73% to US$128.34 in the 8 October US session. Third-quarter revenue rose 5.6% YoY to US$25.27bn, with organic growth of 3.1%; core operating margin contracted 35bps. Full-year core constant-currency EPS growth guidance fell to 1–2% from the prior low end of 4–6%. North American beverage volumes fell 2% YoY, keeping cost reductions and margin recovery central. (PepsiCo / Reuters / Market data)
Coca-Cola (KO US) is again exploring a Costa Coffee sale, Semafor reported. Reuters said discussions followed an earlier effort that attracted unacceptable offers. Coca-Cola paid US$5.1bn for Costa in 2018; a current price was undisclosed and completion remains uncertain. A disposal could release capital, making valuation pivotal. Coca-Cola closed the 8 October US session at US$87.77, up 2.27%. (Reuters / Semafor / Market data) Coca-Cola (KO US) is our Trading Buy.
American Express (AXP US) faces a US$350mn penalty over anti-money-laundering failures. Reuters said its bank failed to identify, evaluate or report roughly US$13bn of suspicious activity over a decade. The Federal Reserve’s related release came on 8 October at 4.30pm EDT (9 October, 4.30am SGT), after the regular session. Staffing, training and control deficiencies leave remediation costs as an ongoing risk. (Federal Reserve / Reuters)
Greater China
Tencent (0700.HK) weighs US$5bn of bonds for AI expansion. Tencent is considering an offshore bond sale of up to US$5bn, potentially in US dollars and offshore renminbi, Reuters reported, citing Bloomberg. A deal could begin this month, but the company has not confirmed the plan. Additional funding would support AI investment; eventual borrowing costs and returns on computing capacity will determine the benefit for shareholders. (Reuters) Tencent (0700.HK) is our Core Recommendation.
TSMC (TSM US)’s quarterly sales jump 50%, exceeding expectations. TSMC reported third-quarter revenue of NT$1.49tn, up 50% year on year from NT$989.92bn and above the NT$1.46tn consensus. September sales reached NT$511.86bn, up 54.6% year on year despite a 0.6% monthly decline. The release reinforces AI manufacturing demand, while detailed margins and capital-spending guidance remain necessary to judge how much growth converts into shareholder returns. (Reuters / TSMC) TSMC (TSM US) is our Core Recommendation.
Biren Technology (6082.HK) drops 11.85% after a discounted placement plan. Biren closed at HK$30.36 on 8 October, versus HK$34.44 previously. Its pre-open placement announcement provides background: 130m shares at HK$31.08 would raise HK$4.02bn net and represent 4.76% of enlarged capital. Seventy percent is earmarked for procurement, production and commercialisation. The conditional financing supports expansion, while dilution and execution risk weigh on shareholders. (SCMP / HKEX / Market data)
China’s holiday border traffic shows continued recovery. Official data released on 8 October showed 15.46m cross-border trips during the seven-day National Day holiday, averaging 2.21m daily, up 6.7% year on year. Mainland outbound trips rose 9.3% to 4.44m; foreign arrivals increased 5.4% to 682,000. Stronger traffic supports airlines, airports and tourism operators, although it does not establish higher spending per traveller or margins. (State Council / Xinhua)
Asia ex. China
Samsung Electronics (005930 KS) forecasts record profit as memory pricing strengthens. Samsung forecast third-quarter operating profit of KRW107.4tn, nearly nine times the year-earlier level and above the KRW106.1tn consensus. Revenue is expected at KRW195tn, up 127% year on year. AI demand and tight DRAM and NAND supplies support pricing power. The preliminary figures highlight earnings momentum, while rising costs, Chinese competition and potential US tariffs remain risks. (Reuters / Samsung / RNS via TradingView)
Singapore banks extend their selloff as margin expectations reset. On 8 October, UOB (U11 SG) fell 5.16% to S$40.25, DBS (D05 SG) 4.70% to S$73.85 and OCBC (O39 SG) 4.29% to S$29.00. The session followed an earlier Citi downgrade of OCBC, which provides background. Citi expects OCBC’s third-quarter profit to be flat year on year after 22% second-quarter growth. Deposit costs and delayed loan repricing could constrain near-term margins. (CNA / Market data / Market data / Market data)
EMEA and Others
European industry presses for stronger China trade defences. Forty-four associations spanning metals, chemicals and automotive suppliers urged faster EU trade-defence measures, stronger enforcement and additional tools against Chinese imports. Their call came as the bloc’s bilateral deficit exceeded €1bn daily. This is an industry request, rather than adopted policy. Intervention could support exposed European producers while raising input costs and retaliation risks for businesses with Chinese operations. (Reuters)
Traders’ corner
\
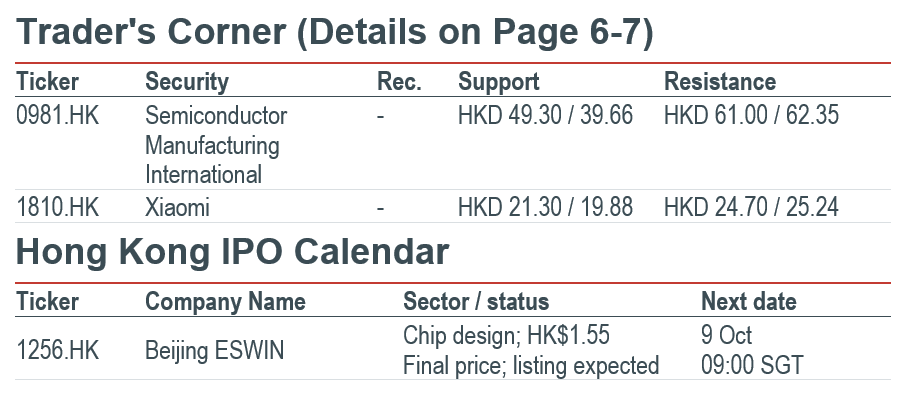
Our Technical View
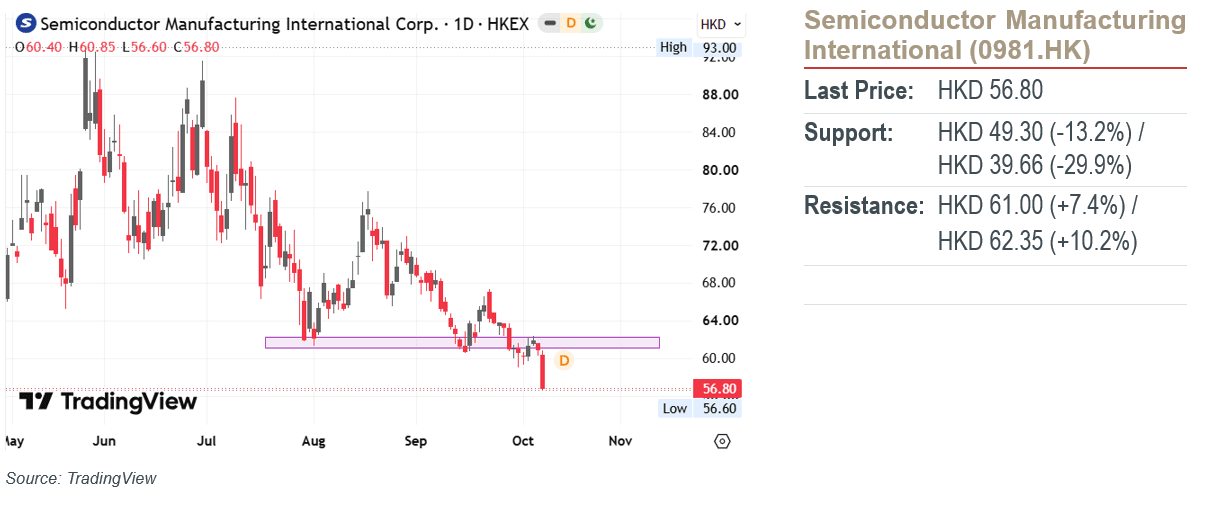
Price executed a decisive downward expansion following a successful capping by its support-turned-resistance zone.
The RSI remains established in bearish territory and continues to slope downward with negative velocity.
As long as price remains underneath this newly converted resistance, we see continued downward expansion toward lower support.
Our Technical View
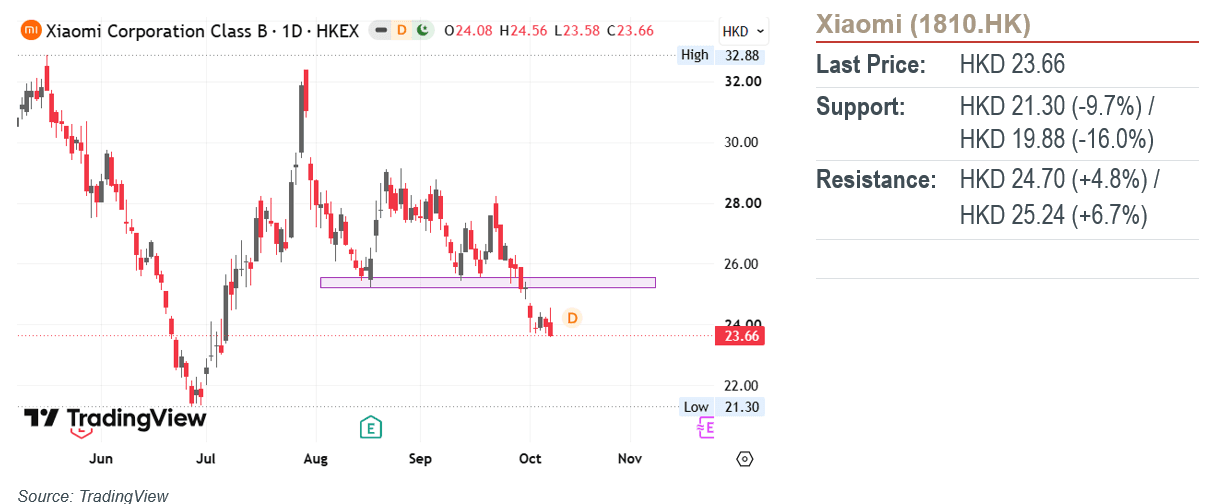
Price executed a downward expansion initiated by a gap down from its support-turned-resistance zone.
The RSI remains established in bearish territory and is descending toward oversold boundaries.
As long as price remains underneath this converted gap-resistance, we see continued downward expansion toward lower support.
Market Movers: The S&P 500 fell 0.47% on Thursday, 8 October, as chip stocks weakened. Broadcom (AVGO US) declined 4.35% amid scrutiny of AI revenues and infrastructure financing. Wednesday’s report of US$50bn of proposed customer financing sharpened attention on how quickly AI spending converts into cash receipts. Alphabet (GOOGL US) slipped 0.63% as Google introduced a universal Gemini workplace agent spanning its software and third-party services. Google says nearly 80% of Cloud customers use its AI products, supporting enterprise monetisation. TSMC (TSM US) fell 3.01% despite September sales rising 54.6% YoY to NT$511.86bn. Third-quarter sales reached NT$1.49tn, up 50% YoY and above the NT$1.46tn consensus. Strong demand still faces demanding valuations and financing uncertainty. (Reuters / Google / TSMC / Reuters) Broadcom (AVGO US) & TSMC (TSM US) are our Core Recommendations; Alphabet (GOOGL US) is our Trading Buy.
Macro: US initial jobless claims eased to 197,000, down 2,000 from the revised prior week and 15.5% below the comparable year-earlier figure. Continuing claims rose 17,000 to 1.716mn. Low layoffs support household income, but rising continuing claims caution against inferring stronger hiring. (US Labor Department / Reuters)
FICC: December Brent settled 4.07% higher at US$104.28/bbl; November WTI gained 3.64% to US$91.49/bbl. Middle East shipping risks and hurricane-related US Gulf shutdowns supported prices; diplomatic comments trimmed intraday gains. About 1.3mn barrels a day, or 62.9% of US Gulf output, was shut in, threatening fuel availability and transport costs. The US 10-year par yield fell 6bps to 5.22%. Dearer fuel raises cost pressures while lower yields partly ease financing conditions. (Reuters / US Treasury)
AI
Broadcom (AVGO US) fell 4.35% to US$360.14 in the 8 October US session. Reuters linked the decline to Wednesday’s report of US$50bn in planned OpenAI financing. CNBC reported during Thursday’s session that OpenAI’s September annualised revenue was about US$50bn; higher earlier figures included partners’ gross revenue. The accounting distinction complicates comparisons and sharpens scrutiny of infrastructure funding against cash generation. (Reuters / CNBC / Market data) Broadcom (AVGO US) is our Core Recommendation.
Alphabet (GOOGL US) introduced a universal Gemini work agent spanning Workspace, Microsoft 365 and Slack. Google said nearly 80% of Cloud customers use its AI; featured small and midsize customers’ AI-tool usage grew over fivefold YoY. Financial-services and legal versions are in preview. Wider workflow coverage intensifies enterprise-software competition. Alphabet’s 8 October US close was US$348.29, down 0.63%. (Google / Reuters / Market data) Alphabet (GOOGL US) is our Trading Buy.
Anthropic launched Claude Dashboards and Motion in beta, expanding into analytics and animation. Dashboards connects live business data and shows queries; Motion creates editable, code-based animations. Docs, Slides and Design became available across all plans. Anthropic said users had created over 45mn documents, decks and designs since launch. The expansion increases pressure on analytics and creative applications. (Anthropic / Reuters)
Nvidia (NVDA US) committed resources valued at US$1bn to US science over five years. The programme supports universities, quantum computing and cloud providers serving government missions. Nvidia also participates in new Genesis Mission projects covering fusion, accelerator design and microelectronics. The investment broadens its scientific-computing footprint and could extend demand beyond commercial AI models; associated customer orders or revenue were not quantified. (Nvidia) Nvidia (NVDA US) is our Core Recommendation.
Americas
Microsoft (MSFT US) faces a suspension of new and pending PERM permanent labour certifications. Reuters reported the action also covers Adobe and six IT-services companies, with no end date. Microsoft said about 80% of prior-year H-1B applications concerned existing employees’ extensions or status changes. Skilled-staff retention remains uncertain. Microsoft closed the 8 October US session at US$522.61, down 1.35%. (Reuters / Market data) Microsoft (MSFT US) is our Core Recommendation.
Palantir (PLTR US) gained 2.40% to US$198.78 in the 8 October US session. Goldman Sachs upgraded it from Neutral to Buy with a US$230 target, citing sovereign AI and specialised enterprise applications. Its thesis emphasises customer-facing engineers feeding implementation experience into product development. This could help defend differentiation as generic AI tools proliferate. (Reuters / Yahoo Finance / Market data)
Starbucks (SBUX US) has explored a Chipotle takeover. Reuters said it had worked with advisers in recent months; no agreed deal was announced. In the 8 October US session, Chipotle (CMG US) gained 6.21% to US$32.68 and Starbucks fell 0.40% to US$93.21. The reported exploration raises financing and management-capacity questions while Starbucks pursues its turnaround. (Reuters / Market data / Market data)
PepsiCo (PEP US) gained 3.73% to US$128.34 in the 8 October US session. Third-quarter revenue rose 5.6% YoY to US$25.27bn, with organic growth of 3.1%; core operating margin contracted 35bps. Full-year core constant-currency EPS growth guidance fell to 1–2% from the prior low end of 4–6%. North American beverage volumes fell 2% YoY, keeping cost reductions and margin recovery central. (PepsiCo / Reuters / Market data)
Coca-Cola (KO US) is again exploring a Costa Coffee sale, Semafor reported. Reuters said discussions followed an earlier effort that attracted unacceptable offers. Coca-Cola paid US$5.1bn for Costa in 2018; a current price was undisclosed and completion remains uncertain. A disposal could release capital, making valuation pivotal. Coca-Cola closed the 8 October US session at US$87.77, up 2.27%. (Reuters / Semafor / Market data) Coca-Cola (KO US) is our Trading Buy.
American Express (AXP US) faces a US$350mn penalty over anti-money-laundering failures. Reuters said its bank failed to identify, evaluate or report roughly US$13bn of suspicious activity over a decade. The Federal Reserve’s related release came on 8 October at 4.30pm EDT (9 October, 4.30am SGT), after the regular session. Staffing, training and control deficiencies leave remediation costs as an ongoing risk. (Federal Reserve / Reuters)
Greater China
Tencent (0700.HK) weighs US$5bn of bonds for AI expansion. Tencent is considering an offshore bond sale of up to US$5bn, potentially in US dollars and offshore renminbi, Reuters reported, citing Bloomberg. A deal could begin this month, but the company has not confirmed the plan. Additional funding would support AI investment; eventual borrowing costs and returns on computing capacity will determine the benefit for shareholders. (Reuters) Tencent (0700.HK) is our Core Recommendation.
TSMC (TSM US)’s quarterly sales jump 50%, exceeding expectations. TSMC reported third-quarter revenue of NT$1.49tn, up 50% year on year from NT$989.92bn and above the NT$1.46tn consensus. September sales reached NT$511.86bn, up 54.6% year on year despite a 0.6% monthly decline. The release reinforces AI manufacturing demand, while detailed margins and capital-spending guidance remain necessary to judge how much growth converts into shareholder returns. (Reuters / TSMC) TSMC (TSM US) is our Core Recommendation.
Biren Technology (6082.HK) drops 11.85% after a discounted placement plan. Biren closed at HK$30.36 on 8 October, versus HK$34.44 previously. Its pre-open placement announcement provides background: 130m shares at HK$31.08 would raise HK$4.02bn net and represent 4.76% of enlarged capital. Seventy percent is earmarked for procurement, production and commercialisation. The conditional financing supports expansion, while dilution and execution risk weigh on shareholders. (SCMP / HKEX / Market data)
China’s holiday border traffic shows continued recovery. Official data released on 8 October showed 15.46m cross-border trips during the seven-day National Day holiday, averaging 2.21m daily, up 6.7% year on year. Mainland outbound trips rose 9.3% to 4.44m; foreign arrivals increased 5.4% to 682,000. Stronger traffic supports airlines, airports and tourism operators, although it does not establish higher spending per traveller or margins. (State Council / Xinhua)
Asia ex. China
Samsung Electronics (005930 KS) forecasts record profit as memory pricing strengthens. Samsung forecast third-quarter operating profit of KRW107.4tn, nearly nine times the year-earlier level and above the KRW106.1tn consensus. Revenue is expected at KRW195tn, up 127% year on year. AI demand and tight DRAM and NAND supplies support pricing power. The preliminary figures highlight earnings momentum, while rising costs, Chinese competition and potential US tariffs remain risks. (Reuters / Samsung / RNS via TradingView)
Singapore banks extend their selloff as margin expectations reset. On 8 October, UOB (U11 SG) fell 5.16% to S$40.25, DBS (D05 SG) 4.70% to S$73.85 and OCBC (O39 SG) 4.29% to S$29.00. The session followed an earlier Citi downgrade of OCBC, which provides background. Citi expects OCBC’s third-quarter profit to be flat year on year after 22% second-quarter growth. Deposit costs and delayed loan repricing could constrain near-term margins. (CNA / Market data / Market data / Market data)
EMEA and Others
European industry presses for stronger China trade defences. Forty-four associations spanning metals, chemicals and automotive suppliers urged faster EU trade-defence measures, stronger enforcement and additional tools against Chinese imports. Their call came as the bloc’s bilateral deficit exceeded €1bn daily. This is an industry request, rather than adopted policy. Intervention could support exposed European producers while raising input costs and retaliation risks for businesses with Chinese operations. (Reuters)
Traders’ corner
\
Our Technical View
Price executed a decisive downward expansion following a successful capping by its support-turned-resistance zone.
The RSI remains established in bearish territory and continues to slope downward with negative velocity.
As long as price remains underneath this newly converted resistance, we see continued downward expansion toward lower support.
Our Technical View
Price executed a downward expansion initiated by a gap down from its support-turned-resistance zone.
The RSI remains established in bearish territory and is descending toward oversold boundaries.
As long as price remains underneath this converted gap-resistance, we see continued downward expansion toward lower support.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


