Company Coverage
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$108.80
HK$189.00
73.7%
HK$188.00
Analyst
Highlights
- Alibaba will report its 2QFY27 results in late-November, with revenue guided to grow 9% yoy to Rmb270b, slightly below our estimates. Adjusted EBITA should reach Rmb29b, above our Rmb22b forecast, supported by improving cloud profitability and narrowing instant retail and AI Labs and Applications losses. Cloud revenue growth should exceed 50% yoy, with EBITA margin reaching 12%, driven by higher MaaS contribution and T-Head cost efficiencies.
- Maintain BUY with a higher target price of HK$189.00 (US$194.00).
Analysis
- Group profitability expected to improve. Alibaba Group’s (Alibaba) September-quarter revenue is guided to grow 9% yoy to around Rmb270b, below our previous forecast of 11%, mainly reflecting weaker-than-expected Alibaba E-Commerce Group revenue, partly offset by accelerating cloud revenue growth. Group adjusted EBITA could reach Rmb29.4b, up from Rmb9.1b in the same quarter last year and Rmb27.3b in the previous quarter, exceeding our previous forecast of around Rmb21.9b and market consensus. The earnings improvement is primarily driven by higher cloud profitability and narrowing losses in instant retail and AI Labs and Applications.
- E-commerce profitability remains resilient. Alibaba E-Commerce Group revenue is guided at around Rmb199b for the September quarter, slightly below our previous forecast of Rmb204b, amid continued macroeconomic headwinds. Under the revised accounting treatment, which nets merchant subsidies against revenue, customer management revenue (CMR) is guided to decline by mid-single digits yoy, while growing 1% yoy on a like-for-like basis, both broadly in line with our expectations. The narrowing gap between reported and like-for-like CMR growth suggests a moderating impact from merchant subsidies.
Cloud revenue growth continues to accelerate. AI Cloud and Compute Services revenue growth is likely to accelerate to over 50% yoy in the September quarter, in line with our forecast and up from 45% yoy in the June quarter, driven by sustained AI-related demand. Management expects further acceleration in the December quarter and remains confident in sustaining around 50% growth in 2027 (vs 11% in 1QFY27). Cloud EBITA margin is expected to reach 12%, supported by a higher contribution from high-margin Model-as-a-Service (MaaS) revenue and cost efficiencies from self-developed T-Head chips. We believe the improving revenue mix and increasing adoption of proprietary chips should further strengthen cloud profitability. Management also sees potential to achieve its long-term margin target of 20% by end-27.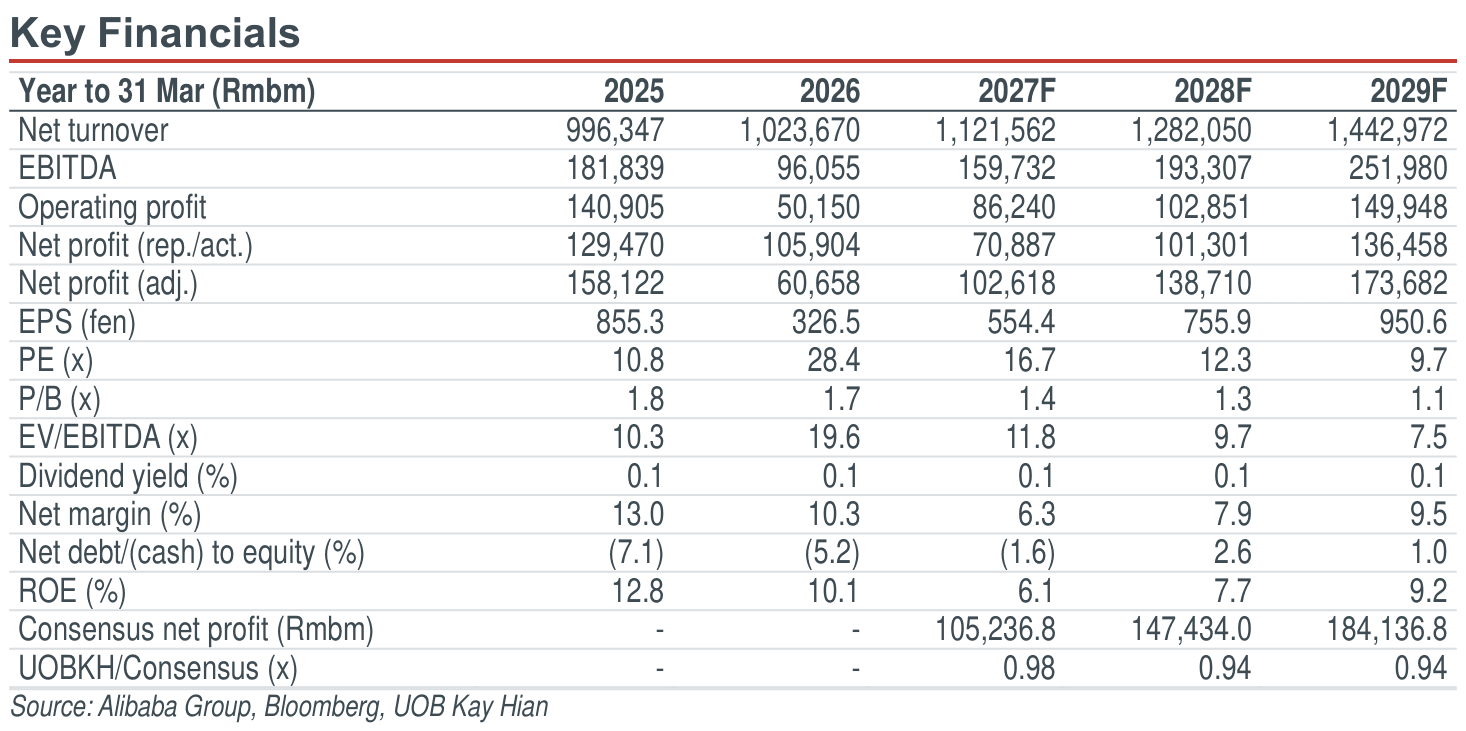
Highlights
- Alibaba will report its 2QFY27 results in late-November, with revenue guided to grow 9% yoy to Rmb270b, slightly below our estimates. Adjusted EBITA should reach Rmb29b, above our Rmb22b forecast, supported by improving cloud profitability and narrowing instant retail and AI Labs and Applications losses. Cloud revenue growth should exceed 50% yoy, with EBITA margin reaching 12%, driven by higher MaaS contribution and T-Head cost efficiencies.
- Maintain BUY with a higher target price of HK$189.00 (US$194.00).
Analysis
- Group profitability expected to improve. Alibaba Group’s (Alibaba) September-quarter revenue is guided to grow 9% yoy to around Rmb270b, below our previous forecast of 11%, mainly reflecting weaker-than-expected Alibaba E-Commerce Group revenue, partly offset by accelerating cloud revenue growth. Group adjusted EBITA could reach Rmb29.4b, up from Rmb9.1b in the same quarter last year and Rmb27.3b in the previous quarter, exceeding our previous forecast of around Rmb21.9b and market consensus. The earnings improvement is primarily driven by higher cloud profitability and narrowing losses in instant retail and AI Labs and Applications.
- E-commerce profitability remains resilient. Alibaba E-Commerce Group revenue is guided at around Rmb199b for the September quarter, slightly below our previous forecast of Rmb204b, amid continued macroeconomic headwinds. Under the revised accounting treatment, which nets merchant subsidies against revenue, customer management revenue (CMR) is guided to decline by mid-single digits yoy, while growing 1% yoy on a like-for-like basis, both broadly in line with our expectations. The narrowing gap between reported and like-for-like CMR growth suggests a moderating impact from merchant subsidies.
Cloud revenue growth continues to accelerate. AI Cloud and Compute Services revenue growth is likely to accelerate to over 50% yoy in the September quarter, in line with our forecast and up from 45% yoy in the June quarter, driven by sustained AI-related demand. Management expects further acceleration in the December quarter and remains confident in sustaining around 50% growth in 2027 (vs 11% in 1QFY27). Cloud EBITA margin is expected to reach 12%, supported by a higher contribution from high-margin Model-as-a-Service (MaaS) revenue and cost efficiencies from self-developed T-Head chips. We believe the improving revenue mix and increasing adoption of proprietary chips should further strengthen cloud profitability. Management also sees potential to achieve its long-term margin target of 20% by end-27.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$108.80
HK$189.00
73.7%
HK$188.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


