Company Coverage
Contemporary Amperex Technology Co (300750 CH): 3Q26: Earnings Miss Due To Delayed Pass-through Of Tax Hikes
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb227.90
Rmb470.00
106.2%
Rmb585.00
Analyst
Highlights
- 3Q26 net profit missed expectations at Rmb21.25b (+14.5% yoy/-5.8% qoq), as CATL bore the export VAT hikes and 2% consumption tax, and had not passed on to customers yet.
- We expect margins to recover in 3Q26, as the tax rate hikes will be partly passed through to customers via higher battery prices. Having said that, the further roll-back of tax concession in 2027 will remain a drag on margins.
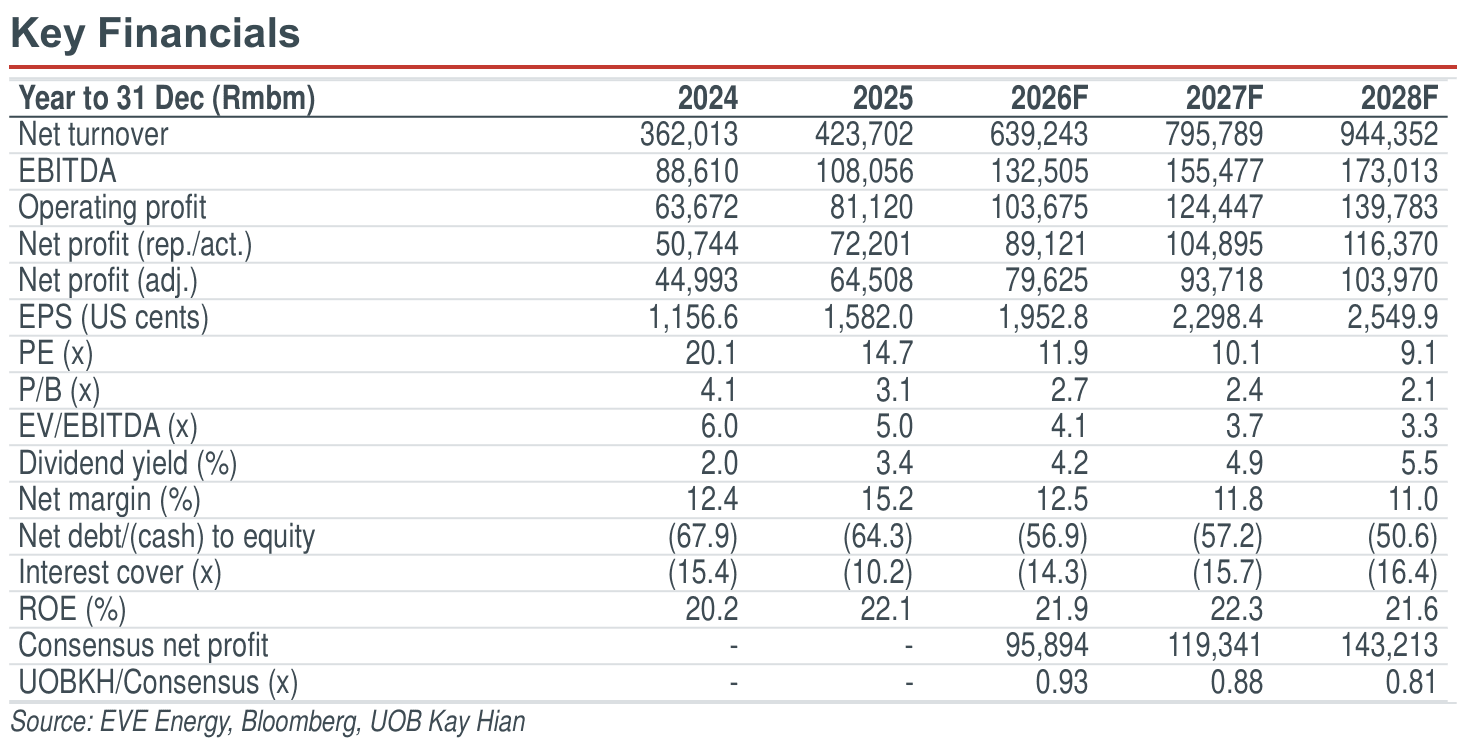
- We cut our 2026-28 net profit forecasts by 5%/10%/16% to Rmb89,121m/Rmb104,895m/Rmb116,370m respectively, as we now expect CATL to bear part of the tax hikes.
- Maintain BUY and cut target price from Rmb585.00 to Rmb470.00.
Analysis
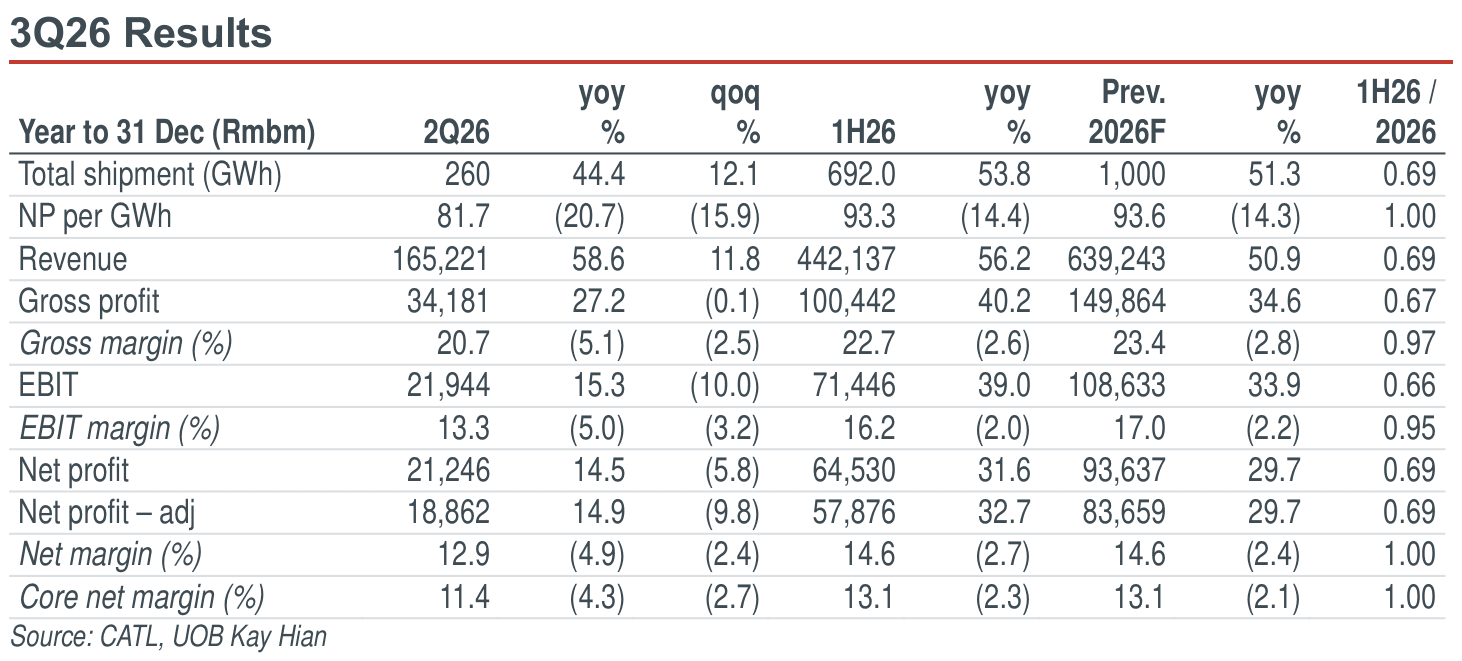
- 3Q26 results came in below estimates with GAAP net profit of Rmb21,246m (+14.5% yoy/-5.8% qoq) and adjusted net profit of Rmb18,862m (+14.9% yoy/-9.8% qoq), vs our estimate of Rmb23.92b. This brings 9M26 net profit and adjusted net profit to Rmb64,530m (+31.6% yoy) and Rmb57,876m (+32.7% yoy) respectively, representing 69% of our full-year estimates of Rmb93,637m (+29.7% yoy) and Rmb83,659m (+29.7% yoy). The earnings miss stemmed from margin contraction.
- Battery shipment grew 44.4% yoy and 12.1% qoq to Rmb260 GWh in 3Q26, in line with estimates, including 195 GWh EV battery (+35.4% yoy/+12.1% qoq) and 65 GWh energy storage system (ESS) battery (+80.6% yoy/+12.1% qoq).
- Battery shipment grew 44.4% yoy and 12.1% qoq to Rmb260 GWh in 3Q26, in line with estimates, including 195 GWh EV battery (+35.4% yoy/+12.1% qoq) and 65 GWh energy storage system (ESS) battery (+80.6% yoy/+12.1% qoq).
Highlights
- 3Q26 net profit missed expectations at Rmb21.25b (+14.5% yoy/-5.8% qoq), as CATL bore the export VAT hikes and 2% consumption tax, and had not passed on to customers yet.
- We expect margins to recover in 3Q26, as the tax rate hikes will be partly passed through to customers via higher battery prices. Having said that, the further roll-back of tax concession in 2027 will remain a drag on margins.
- We cut our 2026-28 net profit forecasts by 5%/10%/16% to Rmb89,121m/Rmb104,895m/Rmb116,370m respectively, as we now expect CATL to bear part of the tax hikes.
- Maintain BUY and cut target price from Rmb585.00 to Rmb470.00.
Analysis
- 3Q26 results came in below estimates with GAAP net profit of Rmb21,246m (+14.5% yoy/-5.8% qoq) and adjusted net profit of Rmb18,862m (+14.9% yoy/-9.8% qoq), vs our estimate of Rmb23.92b. This brings 9M26 net profit and adjusted net profit to Rmb64,530m (+31.6% yoy) and Rmb57,876m (+32.7% yoy) respectively, representing 69% of our full-year estimates of Rmb93,637m (+29.7% yoy) and Rmb83,659m (+29.7% yoy). The earnings miss stemmed from margin contraction.
- Battery shipment grew 44.4% yoy and 12.1% qoq to Rmb260 GWh in 3Q26, in line with estimates, including 195 GWh EV battery (+35.4% yoy/+12.1% qoq) and 65 GWh energy storage system (ESS) battery (+80.6% yoy/+12.1% qoq).
- Battery shipment grew 44.4% yoy and 12.1% qoq to Rmb260 GWh in 3Q26, in line with estimates, including 195 GWh EV battery (+35.4% yoy/+12.1% qoq) and 65 GWh energy storage system (ESS) battery (+80.6% yoy/+12.1% qoq).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb227.90
Rmb470.00
106.2%
Rmb585.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


