

Company Coverage
Food Empire Holdings (FEH SP) - Meeting Highlights: Strong Brand Equity Supports Inflation Resilience; Russian Risks Warrant Differentiated Assessment
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.92
S$3.49
+81.8%
Analyst
Analyst
Highlights
- FEH’s strong brand equity and extensive distribution network provide an operational hedge against prolonged inflation, supporting demand resilience, pricing power and potential market-share gains.
- FEH’s Russian operations remain unaffected by recent measures against Nestlé. While geopolitical risks remain, the development should not be directly extrapolated to FEH or justify excluding Russian earnings from its valuation.
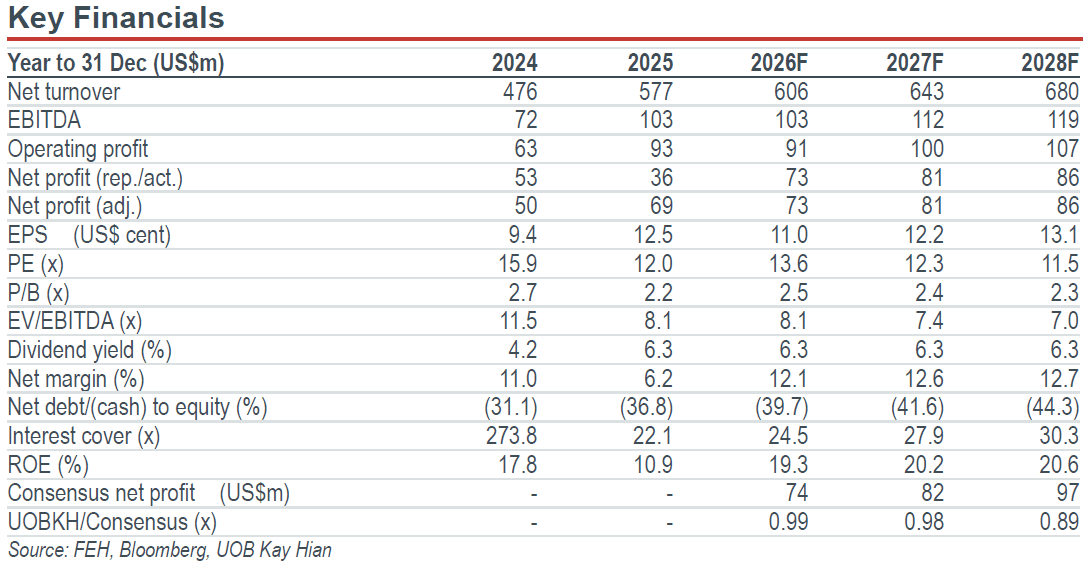
- Maintain BUY and target price of S$3.49. FEH trades at an attractive 12.2x 2027F PE, a 39% discount to peers’ 20x.
Analysis
- Brand equity and distribution infrastructure support inflation resilience and Russia risk requires a differentiated assessment. Our recent Kuala Lumpur non-deal roadshow highlighted investor concerns over prolonged input-cost inflation amid the Middle East conflict and Russia’s intervention in Nestlé’s local business. Food Empire Holdings’ (FEH) strong brand equity, extensive distribution network and experience operating in volatile markets provide an operational hedge against inflation and could support further market-share gains. While Russia remains a key geopolitical risk requiring continued monitoring, Nestlé’s situation should not be directly extrapolated to FEH or justify excluding Russian earnings from its base-case valuation.
- Brand equity and robust network provide an operational hedge against inflation. Investors raised concerns over prolonged inflation, particularly rising energy, sugar, packaging and logistics costs, alongside climate-related risks to coffee supply. FEH’s established brands and extensive distribution network support pricing power, product availability and customer retention. Its experience in managing commodity inflation and supply-chain disruptions also allows for price adjustments, product-mix optimisation and supply flexibility.
- Affordable products reinforce demand resilience. FEH’s coffee products occupy an affordable, everyday consumption category. Consumers facing tighter household budgets may continue purchasing packaged coffee while reducing spending on more expensive discretionary occasions. Brand familiarity, convenient availability and accessible pricing support this demand. In Vietnam, Café Phố’s established consumer franchise and distribution reach provide a strong platform for managing pricing while preserving purchase frequency. Affordability remains essential, and price increases have been calibrated carefully.
Highlights
- FEH’s strong brand equity and extensive distribution network provide an operational hedge against prolonged inflation, supporting demand resilience, pricing power and potential market-share gains.
- FEH’s Russian operations remain unaffected by recent measures against Nestlé. While geopolitical risks remain, the development should not be directly extrapolated to FEH or justify excluding Russian earnings from its valuation.
- Maintain BUY and target price of S$3.49. FEH trades at an attractive 12.2x 2027F PE, a 39% discount to peers’ 20x.
Analysis
- Brand equity and distribution infrastructure support inflation resilience and Russia risk requires a differentiated assessment. Our recent Kuala Lumpur non-deal roadshow highlighted investor concerns over prolonged input-cost inflation amid the Middle East conflict and Russia’s intervention in Nestlé’s local business. Food Empire Holdings’ (FEH) strong brand equity, extensive distribution network and experience operating in volatile markets provide an operational hedge against inflation and could support further market-share gains. While Russia remains a key geopolitical risk requiring continued monitoring, Nestlé’s situation should not be directly extrapolated to FEH or justify excluding Russian earnings from its base-case valuation.
- Brand equity and robust network provide an operational hedge against inflation. Investors raised concerns over prolonged inflation, particularly rising energy, sugar, packaging and logistics costs, alongside climate-related risks to coffee supply. FEH’s established brands and extensive distribution network support pricing power, product availability and customer retention. Its experience in managing commodity inflation and supply-chain disruptions also allows for price adjustments, product-mix optimisation and supply flexibility.
- Affordable products reinforce demand resilience. FEH’s coffee products occupy an affordable, everyday consumption category. Consumers facing tighter household budgets may continue purchasing packaged coffee while reducing spending on more expensive discretionary occasions. Brand familiarity, convenient availability and accessible pricing support this demand. In Vietnam, Café Phố’s established consumer franchise and distribution reach provide a strong platform for managing pricing while preserving purchase frequency. Affordability remains essential, and price increases have been calibrated carefully.
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.92
S$3.49
+81.8%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Sept 2026
Food Empire Holdings (FEH SP): Business As Usual In Russia; Share Price Weakness, Potential Market Share Gain And High Short Position Present Buying Opportunities

9 Oct 2026
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive

28 Sept 2026
Reclaims Global (RGL SP) : 1HFY27: Healthy Results; Margins Remain Resilient
Our latest research
9 Oct 2026
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive

8 Oct 2026
United Hampshire US REIT (UHU SP): Turning Around From Retail Apocalypse To Retail Renaissance

7 Oct 2026