
Company Coverage
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.775
S$1.21
+56.1%
Analyst
Analyst
Highlights
- A stronger US dollar against the ringgit and improving pricing power from recent ASP hikes by Chinese glovemakers should provide an earnings tailwind.
- The cleanroom glove segment, which contributes around 70% of earnings should remain robust, helped by ongoing orders from AI-related data centre and memory storage customers.
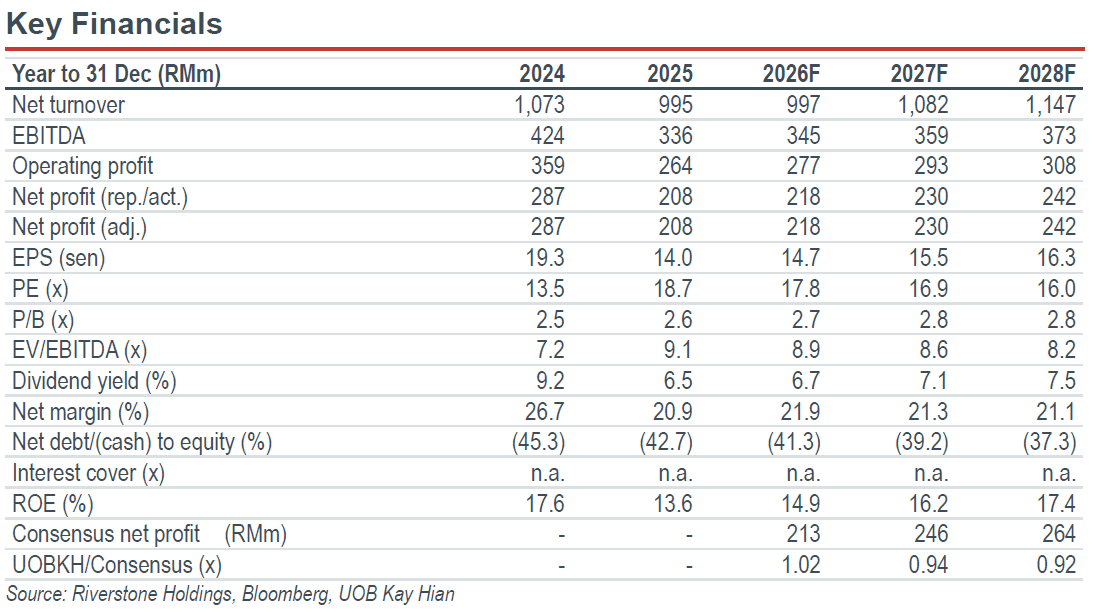
- Maintain BUY with an unchanged target price of S$1.21. Riverstone currently trades at around 15% discount to peers and offers an attractive 7% 2026 yield.
Analysis
- Stronger US dollar provides near-term earnings tailwind. The recent strengthening of the US dollar against the Malaysian ringgit should be positive for Riverstone Holdings (Riverstone), reversing some of the forex headwinds seen earlier in the year. USD/MYR has moved to around 4.08 in early-Oct 26, compared with the stronger ringgit environment that weighed on Riverstone’s 1H26 earnings. With a significant portion of sales denominated in US dollars while a large part of its core base is in ringgit, a stronger US dollar should support revenue translations and margins in the near term.
- Chinese glovemakers’ ASP hikes improve pricing environment. Recent price increases by Chinese glove manufacturers are positive for the broader glove pricing environment. Chinese generic nitrile glove ASPs have risen, narrowing their discount to Malaysian producers to around US$0.50/1,000 pieces from US$1.50-2.00 previously. This gives Malaysian glovemakers greater room to raise ASPs without materially widening the price differential and should support Riverstone’s healthcare glove pricing and margins. However, we expect Riverstone to remain selective in competing for generic volumes, given its focus on higher-value customised products.
- Cleanroom remains the key growth engine with demand boost from AI. Cleanroom glove demand has been rising since 2Q26, helped by ongoing orders from AI-related data centre and memory storage customers. We see the cleanroom segment as Riverstone’s main earnings driver going forward. Riverstone is also renewing older production lines and moving away from low margin generic output towards higher value cleanroom and customised healthcare products. This should improve product mix and margins over time.
Highlights
- A stronger US dollar against the ringgit and improving pricing power from recent ASP hikes by Chinese glovemakers should provide an earnings tailwind.
- The cleanroom glove segment, which contributes around 70% of earnings should remain robust, helped by ongoing orders from AI-related data centre and memory storage customers.
- Maintain BUY with an unchanged target price of S$1.21. Riverstone currently trades at around 15% discount to peers and offers an attractive 7% 2026 yield.
Analysis
- Stronger US dollar provides near-term earnings tailwind. The recent strengthening of the US dollar against the Malaysian ringgit should be positive for Riverstone Holdings (Riverstone), reversing some of the forex headwinds seen earlier in the year. USD/MYR has moved to around 4.08 in early-Oct 26, compared with the stronger ringgit environment that weighed on Riverstone’s 1H26 earnings. With a significant portion of sales denominated in US dollars while a large part of its core base is in ringgit, a stronger US dollar should support revenue translations and margins in the near term.
- Chinese glovemakers’ ASP hikes improve pricing environment. Recent price increases by Chinese glove manufacturers are positive for the broader glove pricing environment. Chinese generic nitrile glove ASPs have risen, narrowing their discount to Malaysian producers to around US$0.50/1,000 pieces from US$1.50-2.00 previously. This gives Malaysian glovemakers greater room to raise ASPs without materially widening the price differential and should support Riverstone’s healthcare glove pricing and margins. However, we expect Riverstone to remain selective in competing for generic volumes, given its focus on higher-value customised products.
- Cleanroom remains the key growth engine with demand boost from AI. Cleanroom glove demand has been rising since 2Q26, helped by ongoing orders from AI-related data centre and memory storage customers. We see the cleanroom segment as Riverstone’s main earnings driver going forward. Riverstone is also renewing older production lines and moving away from low margin generic output towards higher value cleanroom and customised healthcare products. This should improve product mix and margins over time.
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.775
S$1.21
+56.1%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

13 Aug 2026
Riverstone Holdings (RSTON SP): 2Q26: Strong Earnings Beat; Expect Continued Strength

14 Aug 2026
UltraGreen.ai (UGAI SP): 1H26: Robust Growth And More Positive Outlook For 2H26

17 Aug 2026
CSE Global (CSE SP) 1H26: Earnings Impacted by One-Offs; 2H26 Earnings To Be Stronger
Our latest research

8 Oct 2026
United Hampshire US REIT (UHU SP): Turning Around From Retail Apocalypse To Retail Renaissance

7 Oct 2026
Sasseur REIT (SASSR SP) - Sasseur Site Visit: Value Hunters Keep Chongqing Busy

6 Oct 2026