Company Coverage
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.11
S$2.92
38.4%
S$3.00
Analyst
Highlights
- FCT clocked positive rental reversion of 6.6% in FY26 and maintained stable portfolio occupancy at 99.7% as of Sep 26. Tenant retention was healthy at 81%. Occupancy cost of 16.3% was supported by tenant sales growth.
- Causeway Point, believed to be most susceptible to retail sales leakage to Johor Bahru, achieved growth in NPI of 6% yoy in 2HFY26. Northpoint City saw NPI growth of 23% yoy, boosted by full six-month contribution from Northpoint City South Wing (acquisition completed on 26 May 25).
- FCT creates value through AEIs. Maintain BUY. Target price: S$2.92.
Analysis
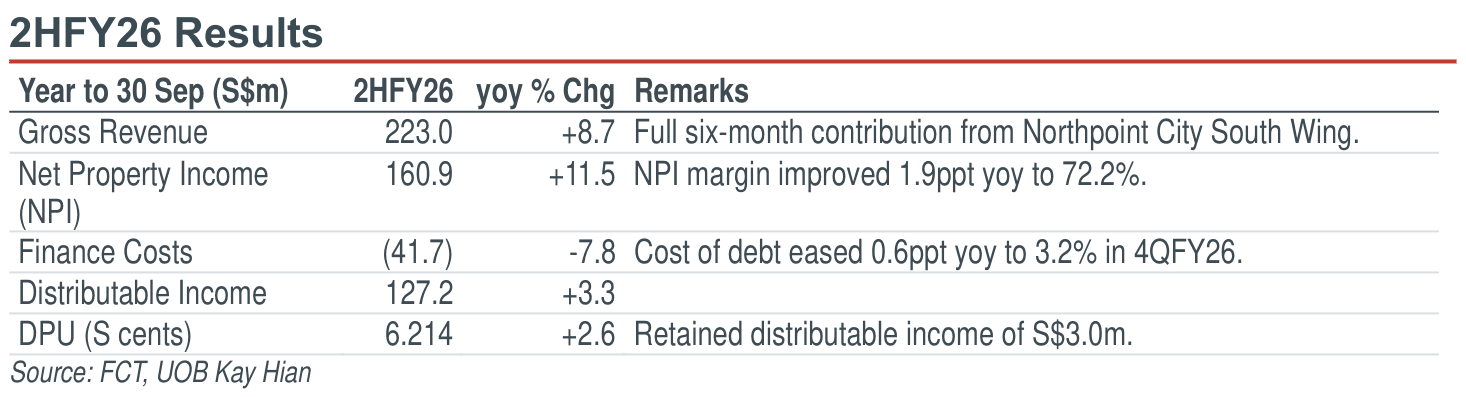
- Frasers Centrepoint Trust (FCT) reported 2HFY26 DPU of 6.214 S cents (+2.6% yoy), which is in line with our expectation despite retaining income of S$3m for asset enhancement initiatives (AEI) and working capital purposes. Full-year FY26 DPU was a record 12.35 S cents.
- Northpoint City drives NPI growth. Gross revenue and NPI grew 8.7% and 11.5% yoy in 2HFY26, driven by full six-month contribution from Northpoint City South Wing and higher passing rents across most malls. Northpoint City achieved 100% occupancy as of Sep 26 and generated NPI of S$48.5m in 2HFY26 (+23% yoy), accounting for 30% of group NPI. Causeway Point occupancy was 99.9%, with NPI increasing 6% yoy to S$36.4m. NPI margin improved 1.9ppt yoy to 72.2% in 2HFY26 due to cost savings from integrated facilities management and diagnostics & preventive maintenance.
- Healthy leasing despite slower sales growth. Committed portfolio occupancy was stable at 99.7% as of Sep 26, excluding NEX and the divested White Sands. Rental reversion was positive at 6.6% on an average-to-average basis in FY26, supported by food & beverage, beauty & healthcare and fashion & accessories. Tenant retention was 81%. Occupancy cost was healthy at 16.3% in FY26. In 4QFY26, traffic rose 1.0% but sales grew just 0.1%, affected by key tenant reconfigurations.
Highlights
- FCT clocked positive rental reversion of 6.6% in FY26 and maintained stable portfolio occupancy at 99.7% as of Sep 26. Tenant retention was healthy at 81%. Occupancy cost of 16.3% was supported by tenant sales growth.
- Causeway Point, believed to be most susceptible to retail sales leakage to Johor Bahru, achieved growth in NPI of 6% yoy in 2HFY26. Northpoint City saw NPI growth of 23% yoy, boosted by full six-month contribution from Northpoint City South Wing (acquisition completed on 26 May 25).
- FCT creates value through AEIs. Maintain BUY. Target price: S$2.92.
Analysis
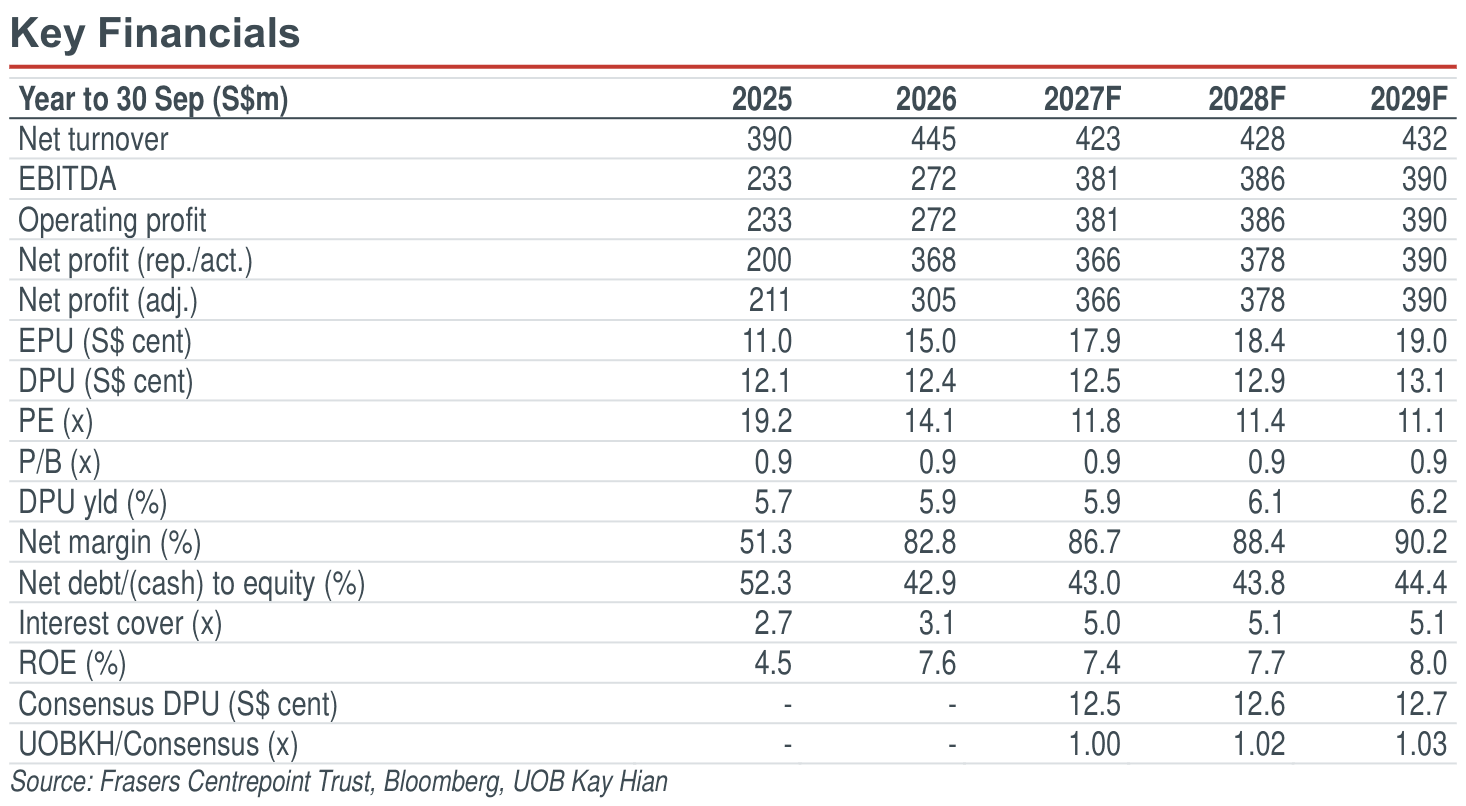
- Frasers Centrepoint Trust (FCT) reported 2HFY26 DPU of 6.214 S cents (+2.6% yoy), which is in line with our expectation despite retaining income of S$3m for asset enhancement initiatives (AEI) and working capital purposes. Full-year FY26 DPU was a record 12.35 S cents.
- Northpoint City drives NPI growth. Gross revenue and NPI grew 8.7% and 11.5% yoy in 2HFY26, driven by full six-month contribution from Northpoint City South Wing and higher passing rents across most malls. Northpoint City achieved 100% occupancy as of Sep 26 and generated NPI of S$48.5m in 2HFY26 (+23% yoy), accounting for 30% of group NPI. Causeway Point occupancy was 99.9%, with NPI increasing 6% yoy to S$36.4m. NPI margin improved 1.9ppt yoy to 72.2% in 2HFY26 due to cost savings from integrated facilities management and diagnostics & preventive maintenance.
- Healthy leasing despite slower sales growth. Committed portfolio occupancy was stable at 99.7% as of Sep 26, excluding NEX and the divested White Sands. Rental reversion was positive at 6.6% on an average-to-average basis in FY26, supported by food & beverage, beauty & healthcare and fashion & accessories. Tenant retention was 81%. Occupancy cost was healthy at 16.3% in FY26. In 4QFY26, traffic rose 1.0% but sales grew just 0.1%, affected by key tenant reconfigurations.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.11
S$2.92
38.4%
S$3.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles


Our latest research

22 Oct 2026
Centurion Corp (CENT SP): Building Value

21 Oct 2026
Keppel REIT (KREIT SP): Refocusing On Home Base Singapore

21 Oct 2026