Company Coverage
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.825
S$1.000
20.0%
Analyst
Highlights
- Portfolio RevPAU rose 4% yoy organically on a same-store basis in 3Q26. Occupancy improved 5ppt qoq to 84%. For AY2026-27, US student accommodation is expected to achieve occupancy of 98% and revenue growth of 7%. Japan rental housing clocked a positive rental reversion of 5%.
- Management is committed to delivering stable DPU, supported by top-up of distributions from past divestment gains, estimated at about S$300m cumulatively, and retained non-periodic foreign exchange gains.
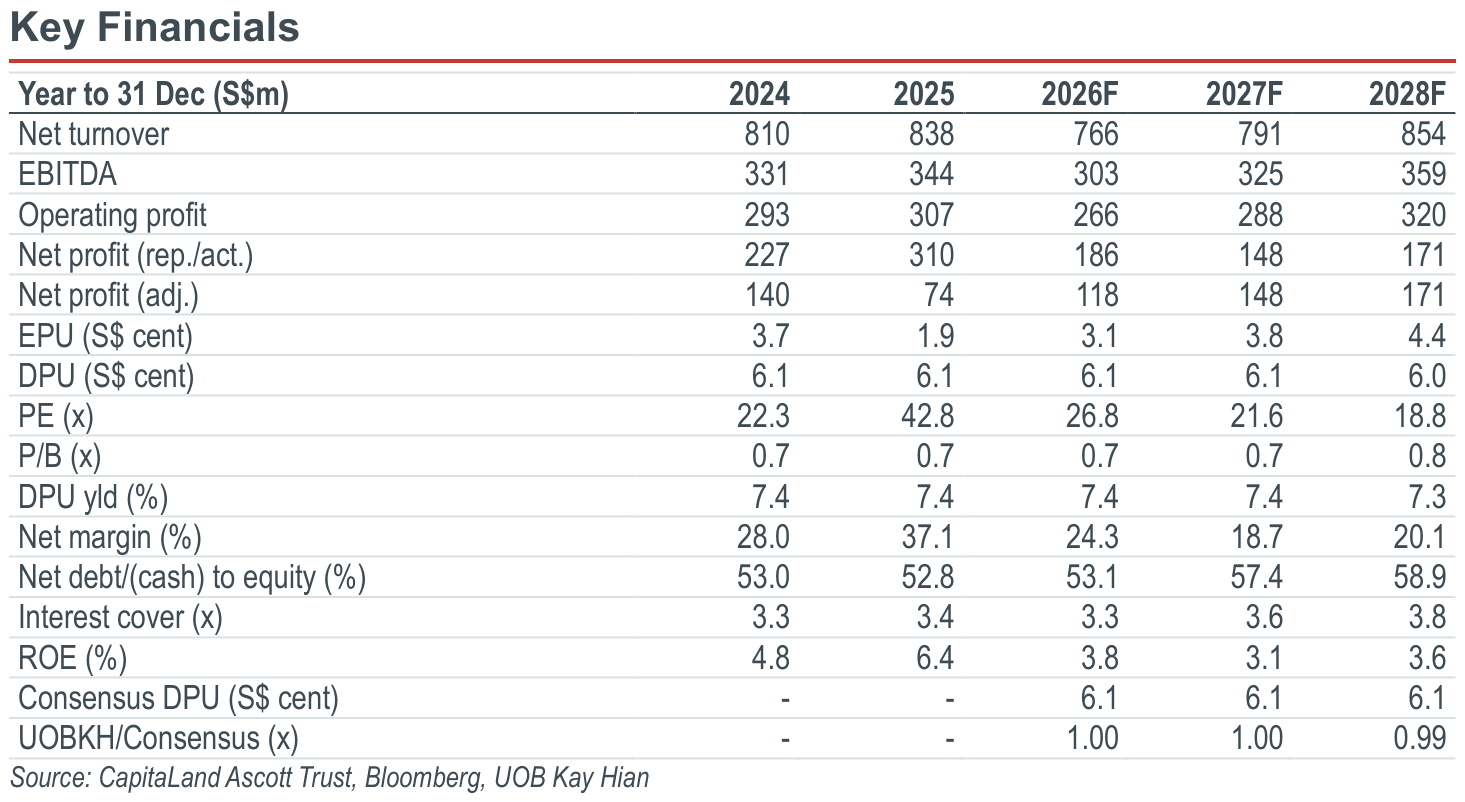
- CLAS continues to create value through disciplined portfolio reconstitution. It provides an attractive 2027 DPU yield of 7.4% due to unit price correction of 13.6% ytd. Maintain BUY. Target price: S$1.00.
Analysis
CapitaLand Ascott Trust (CLAS) reported its 3Q26 business update:
- Portfolio RevPAU grew 0.6% yoy and 5.6% qoq to S$164 in 3Q26. Excluding The Cavendish London (TCL), acquisitions and divestments, portfolio RevPAU rose 4% yoy on a same-store basis. Occupancy improved 5ppt qoq to 84%. Gross profit was affected by TCL's closure, other AEIs, divestments and foreign currency depreciation, partly offset by acquisitions and stronger same-store operations. Excluding TCL but including top-up, gross profit remained relatively stable.
- US – strong outlook strengthened by events calendar. RevPAU rose 12% yoy to US$289 in 3Q26, driven by higher demand during the FIFA World Cup, US Open and Fashion Week, alongside stronger performance at Sheraton Tribeca New York Hotel. Early completion of its asset enhancement initiative (AEI) in 2Q26 enabled Sheraton Tribeca to capture World Cup demand, with average daily rates increasing 16% vs pre-AEI levels in 3Q25. Management expects the strong momentum to continue in 4Q26, supported by events, conventions and year-end holiday demand.
- Student accommodation recovery strengthened for next academic year. US student accommodation revenue increased 2% yoy in 3Q26. Occupancy rose from 88% for AY2025-26 to 98% for AY2026-27, which commenced in Aug 26. Based on in-place leases, 2026-27 revenue is projected to grow 7%. The properties serve domestic students from reputable universities.
Highlights
- Portfolio RevPAU rose 4% yoy organically on a same-store basis in 3Q26. Occupancy improved 5ppt qoq to 84%. For AY2026-27, US student accommodation is expected to achieve occupancy of 98% and revenue growth of 7%. Japan rental housing clocked a positive rental reversion of 5%.
- Management is committed to delivering stable DPU, supported by top-up of distributions from past divestment gains, estimated at about S$300m cumulatively, and retained non-periodic foreign exchange gains.
- CLAS continues to create value through disciplined portfolio reconstitution. It provides an attractive 2027 DPU yield of 7.4% due to unit price correction of 13.6% ytd. Maintain BUY. Target price: S$1.00.
Analysis
CapitaLand Ascott Trust (CLAS) reported its 3Q26 business update:
- Portfolio RevPAU grew 0.6% yoy and 5.6% qoq to S$164 in 3Q26. Excluding The Cavendish London (TCL), acquisitions and divestments, portfolio RevPAU rose 4% yoy on a same-store basis. Occupancy improved 5ppt qoq to 84%. Gross profit was affected by TCL's closure, other AEIs, divestments and foreign currency depreciation, partly offset by acquisitions and stronger same-store operations. Excluding TCL but including top-up, gross profit remained relatively stable.
- US – strong outlook strengthened by events calendar. RevPAU rose 12% yoy to US$289 in 3Q26, driven by higher demand during the FIFA World Cup, US Open and Fashion Week, alongside stronger performance at Sheraton Tribeca New York Hotel. Early completion of its asset enhancement initiative (AEI) in 2Q26 enabled Sheraton Tribeca to capture World Cup demand, with average daily rates increasing 16% vs pre-AEI levels in 3Q25. Management expects the strong momentum to continue in 4Q26, supported by events, conventions and year-end holiday demand.
- Student accommodation recovery strengthened for next academic year. US student accommodation revenue increased 2% yoy in 3Q26. Occupancy rose from 88% for AY2025-26 to 98% for AY2026-27, which commenced in Aug 26. Based on in-place leases, 2026-27 revenue is projected to grow 7%. The properties serve domestic students from reputable universities.
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.825
S$1.000
20.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze

26 Oct 2026
Suntec REIT (SUN SP): 3Q26: Expression Of Interest Exercise To Divest Australia Assets
Our latest research

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth
26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze
26 Oct 2026