Company Coverage
Suntec REIT (SUN SP): 3Q26: Expression Of Interest Exercise To Divest Australia Assets
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.40
S$1.67
19.3%
Analyst
Highlights
- Suntec City Mall maintained its stellar performance with NPI growth of 11.6% yoy in 3Q26. Its occupancy was stable at 98.6%, and rental reversion strengthened to 11.2%. Tenant sales psf grew an impressive 10% yoy.
- SUN has launched expression of interest for 177 Pacific Highway and 21 Harris Street in Sydney and 477 Collins Street in Melbourne, which are valued at S$1,037m in aggregate. The exercise should conclude in Nov 26.
- SUN trades at steep 32% discount to NAV. Maintain BUY. Target price: S$1.67.
Analysis
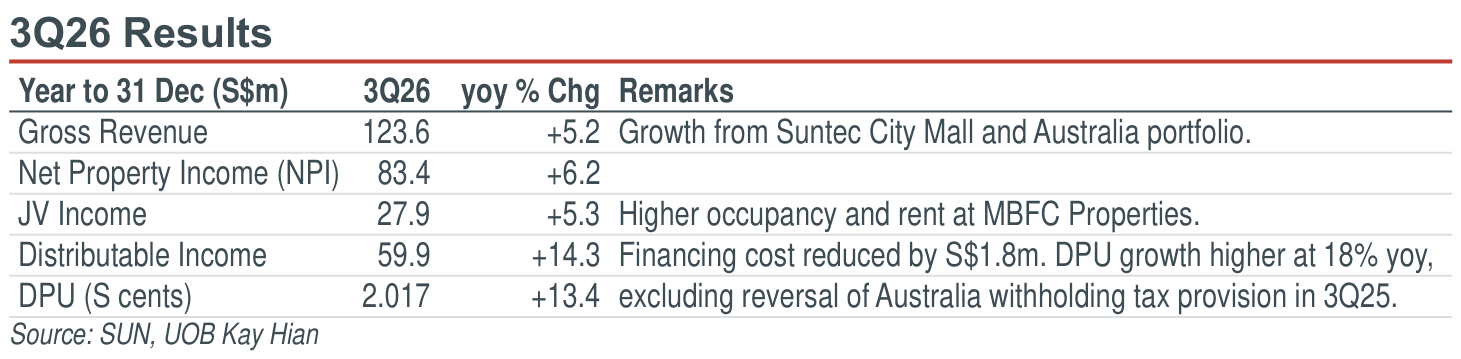
- Suntec REIT (SUN) reported DPU of 2.017 S cents for 3Q26 (+13.4% yoy), which is in line with our expectation. Excluding the S$2m reversal of Australian withholding tax provisions last year in 3Q25, DPU growth would be higher at 18% yoy on an operating basis.
- Singapore office benefits from limited CBD supply. Committed occupancy was 99.6% as of Sep 26, with Suntec City Office fully occupied and One Raffles Quay (ORQ) and Marina Bay Financial Centre (MBFC) Towers 1 & 2 at 99.3% and 99.1% respectively. Suntec City Office rental reversion moderated to 4.4% in 3Q26 from 11.0% in 2Q26. ORQ and MBFC achieved 11.0% reversion in 3Q26. Singapore office NPI edged up 0.7% yoy to S$29.5m as higher operating expenses tempered rental income growth. JV income rose 6.0% to S$19.5m, led by MBFC. Management expects high occupancy and full-year rental reversion of 5-10%.
- Suntec City Mall sustains strong rent and sales growth. Committed occupancy was 98.6% as of Sep 26. Rental reversion increased to 11.2% in 3Q26 from 8.5% in 2Q26. Singapore retail NPI increased 11.6% yoy to S$27.8m, supported by higher occupancy and rents at Suntec City Mall. Tenant sales psf grew 10% yoy in 3Q26, outpacing shopper traffic growth of 5%. August sales were boosted by Sincere Fine Watches' vault sales. Management expects full-year rental reversion of around 10%, with major events, MICE activity and festive spending supporting 4Q26.
Highlights
- Suntec City Mall maintained its stellar performance with NPI growth of 11.6% yoy in 3Q26. Its occupancy was stable at 98.6%, and rental reversion strengthened to 11.2%. Tenant sales psf grew an impressive 10% yoy.
- SUN has launched expression of interest for 177 Pacific Highway and 21 Harris Street in Sydney and 477 Collins Street in Melbourne, which are valued at S$1,037m in aggregate. The exercise should conclude in Nov 26.
- SUN trades at steep 32% discount to NAV. Maintain BUY. Target price: S$1.67.
Analysis
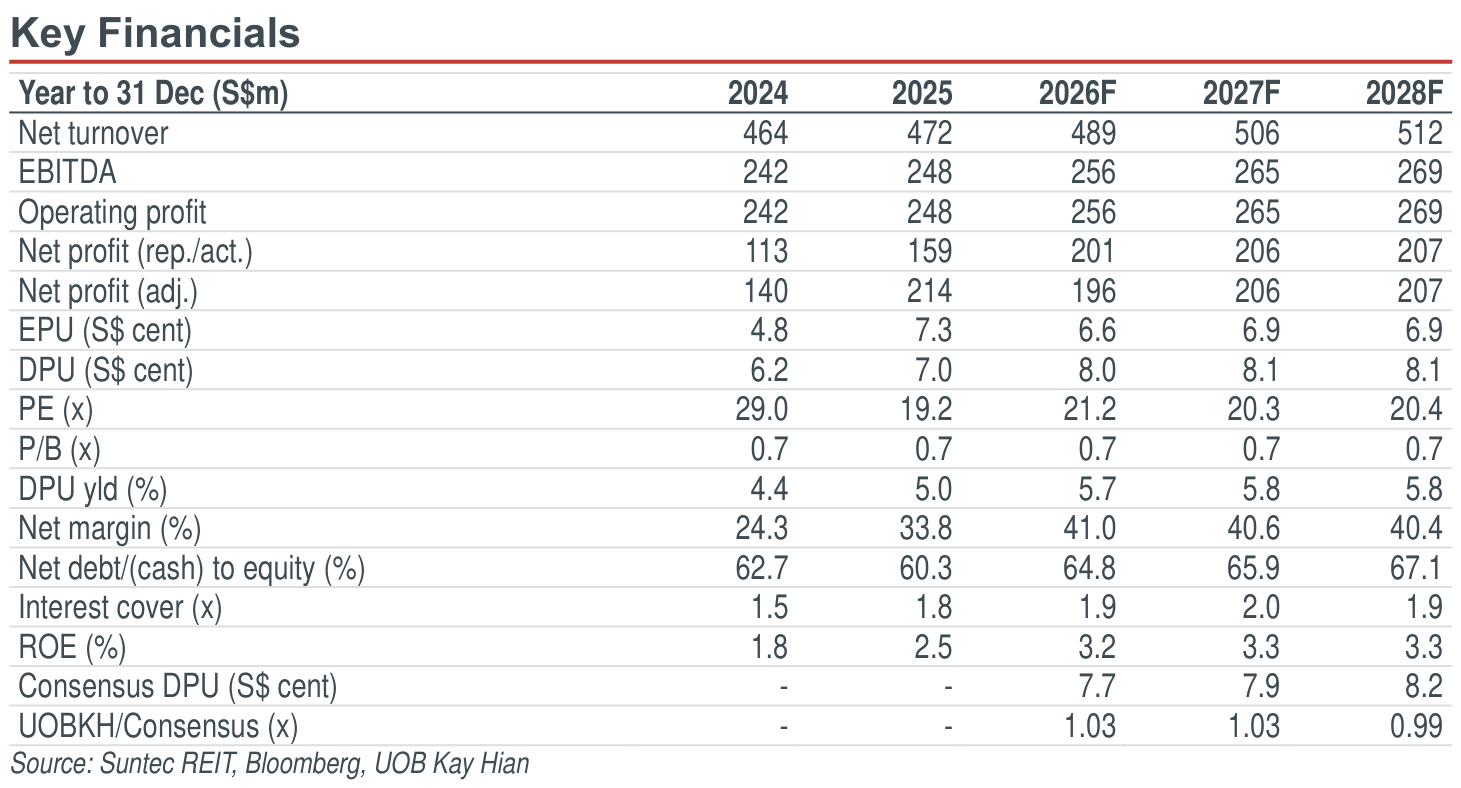
- Suntec REIT (SUN) reported DPU of 2.017 S cents for 3Q26 (+13.4% yoy), which is in line with our expectation. Excluding the S$2m reversal of Australian withholding tax provisions last year in 3Q25, DPU growth would be higher at 18% yoy on an operating basis.
- Singapore office benefits from limited CBD supply. Committed occupancy was 99.6% as of Sep 26, with Suntec City Office fully occupied and One Raffles Quay (ORQ) and Marina Bay Financial Centre (MBFC) Towers 1 & 2 at 99.3% and 99.1% respectively. Suntec City Office rental reversion moderated to 4.4% in 3Q26 from 11.0% in 2Q26. ORQ and MBFC achieved 11.0% reversion in 3Q26. Singapore office NPI edged up 0.7% yoy to S$29.5m as higher operating expenses tempered rental income growth. JV income rose 6.0% to S$19.5m, led by MBFC. Management expects high occupancy and full-year rental reversion of 5-10%.
- Suntec City Mall sustains strong rent and sales growth. Committed occupancy was 98.6% as of Sep 26. Rental reversion increased to 11.2% in 3Q26 from 8.5% in 2Q26. Singapore retail NPI increased 11.6% yoy to S$27.8m, supported by higher occupancy and rents at Suntec City Mall. Tenant sales psf grew 10% yoy in 3Q26, outpacing shopper traffic growth of 5%. August sales were boosted by Sincere Fine Watches' vault sales. Management expects full-year rental reversion of around 10%, with major events, MICE activity and festive spending supporting 4Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.40
S$1.67
19.3%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze

29 Sept 2026
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy

23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth
Our latest research
26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze
23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth

22 Oct 2026