Company Coverage
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$10.24
S$11.90
+16.2%
S$13.26
Analyst
Highlights
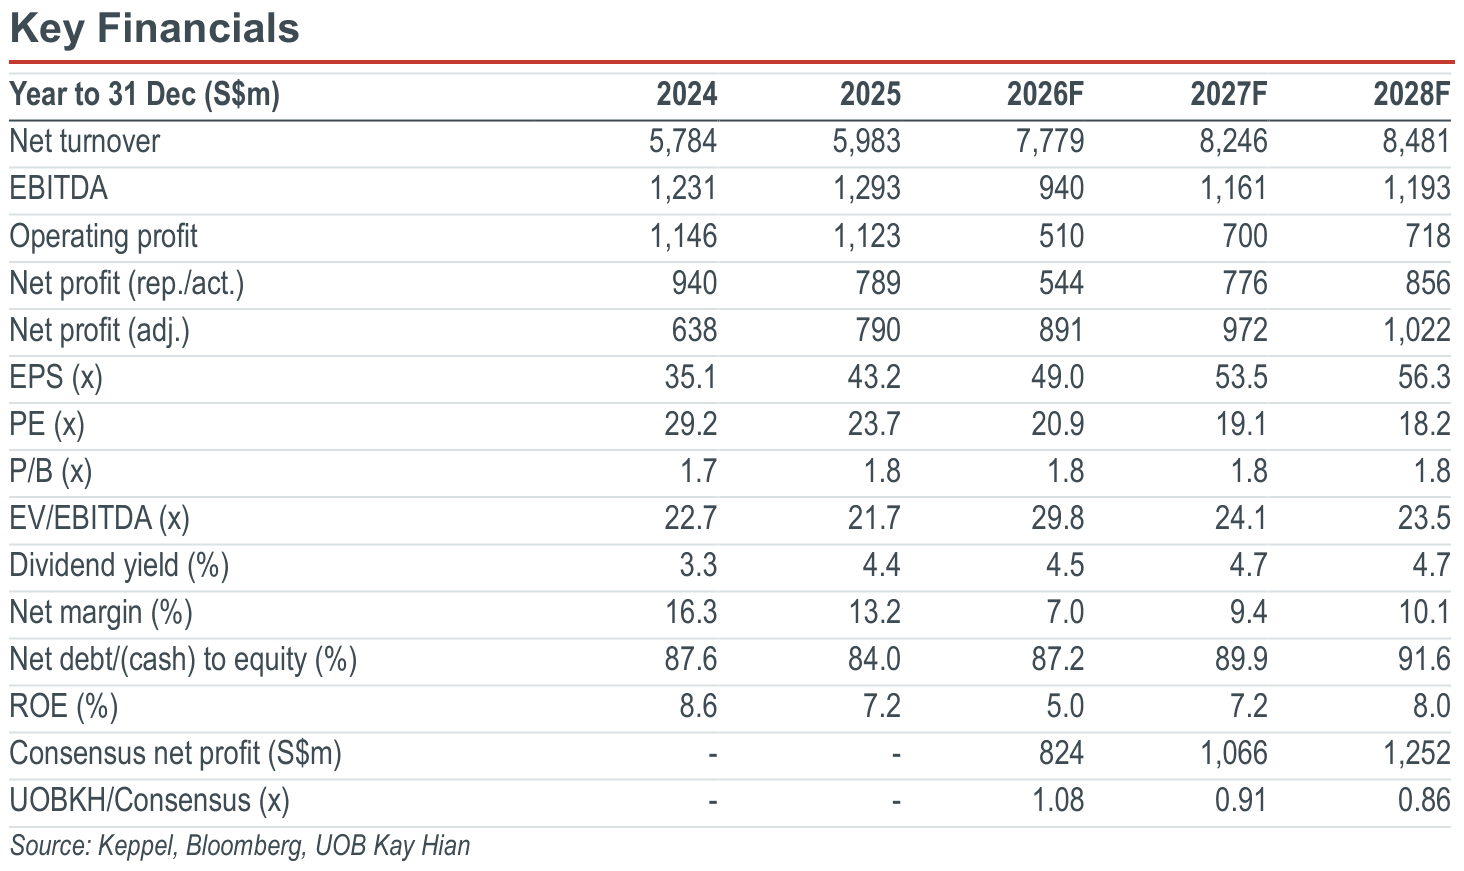
- 3Q26 headline net profit of new Keppel rose 15% yoy; however, 9M26 core earnings growth of over 10% yoy came in behind our 20% full-year growth projection, due to weaker-than-expected integrated power contribution.
- Asset management fees rose 18% yoy in 9M26, driven by expanding FUM, having surpassed S$100b.
- We lower our core earnings forecast for Keppel by 4-6%, as we fine-tune our estimates for the integrated power business.
- Keppel continues to ride favourable secular trends of rising power demand and AI-driven digital infrastructure investments, while scaling up its fund management business towards its 2030 goals.
- Maintain BUY, with a lower target price of S$11.90, which values Keppel at 17x 2027F core earnings, adjusted for assets for divestments and net debt.
Analysis
- New Keppel’s headline net profit rose 15% yoy. Keppel reported that the headline net profit of the new Keppel rose 15% yoy in 3Q26 and over 20% yoy in 9M26, driven by strong connectivity earnings and steady infrastructure contributions. Including the divestment portfolio and discontinued operations, Keppel’s 3Q26 overall net profit grew 20% yoy in 3Q26, though the 9M26 figure was 40% lower yoy due to the sizeable impairment losses recorded in 1H26 on the non-core portfolio for divestment.
- Core earnings growth weaker than expected. Excluding one-time items such as revaluation/disposal gains/(losses), recurring net profit of the new Keppel rose over 10% yoy in 9M26, trailing behind our projected 20% yoy growth for 2026. The shortfall was mainly from the integrated power business, whose EBITDA rose only 7% yoy in 9M26, although the Keppel Sakra Cogen Plant (which commenced commercial operations in May 26) has expanded Keppel’s generation capacity by 45%. The weaker-than-expected integrated power contribution may be explained by: a) some downtime related to the planned maintenance of a power generating unit at the Keppel Merlimau Cogen Plant, and b) overall yoy weaker spark spread across the broader portfolio.
Highlights
- 3Q26 headline net profit of new Keppel rose 15% yoy; however, 9M26 core earnings growth of over 10% yoy came in behind our 20% full-year growth projection, due to weaker-than-expected integrated power contribution.
- Asset management fees rose 18% yoy in 9M26, driven by expanding FUM, having surpassed S$100b.
- We lower our core earnings forecast for Keppel by 4-6%, as we fine-tune our estimates for the integrated power business.
- Keppel continues to ride favourable secular trends of rising power demand and AI-driven digital infrastructure investments, while scaling up its fund management business towards its 2030 goals.
- Maintain BUY, with a lower target price of S$11.90, which values Keppel at 17x 2027F core earnings, adjusted for assets for divestments and net debt.
Analysis
- New Keppel’s headline net profit rose 15% yoy. Keppel reported that the headline net profit of the new Keppel rose 15% yoy in 3Q26 and over 20% yoy in 9M26, driven by strong connectivity earnings and steady infrastructure contributions. Including the divestment portfolio and discontinued operations, Keppel’s 3Q26 overall net profit grew 20% yoy in 3Q26, though the 9M26 figure was 40% lower yoy due to the sizeable impairment losses recorded in 1H26 on the non-core portfolio for divestment.
- Core earnings growth weaker than expected. Excluding one-time items such as revaluation/disposal gains/(losses), recurring net profit of the new Keppel rose over 10% yoy in 9M26, trailing behind our projected 20% yoy growth for 2026. The shortfall was mainly from the integrated power business, whose EBITDA rose only 7% yoy in 9M26, although the Keppel Sakra Cogen Plant (which commenced commercial operations in May 26) has expanded Keppel’s generation capacity by 45%. The weaker-than-expected integrated power contribution may be explained by: a) some downtime related to the planned maintenance of a power generating unit at the Keppel Merlimau Cogen Plant, and b) overall yoy weaker spark spread across the broader portfolio.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$10.24
S$11.90
+16.2%
S$13.26
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

7 Sept 2026
Soon Hock Enterprise (SHOCK SP): 1H26: Robust Development Pipeline Supports Growth
Our latest research

30 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): 3Q26: Uptick For Office Occupancy; Firmer Reversion For Retail

30 Oct 2026
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue

29 Oct 2026