

Company Coverage
NTT DC REIT (NTTDCR SP): Embracing Closer Alignment With Unitholders’ Interest
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$0.90
US$1.31
+45.6%
US$1.29
Analyst
Highlights
- NTTDCR aims to expand in Europe to increase its exposure to Tier 1 markets. It has debt headroom of US$261m based on a gearing of 40%, which could be utilised to acquire a hyperscale 24MW DC in Frankfurt, Germany in 2HFY27.
- NTTDCR is the first data centre REIT to link payment of performance fee to DPU growth and set a stringent minimum threshold for DPU growth of 3%. Unitholders’ interest is protected as new units issued for payment of management fees is priced at NAV or higher. The restructuring incentivises DPU growth and increases alignment with unitholders’ interest.
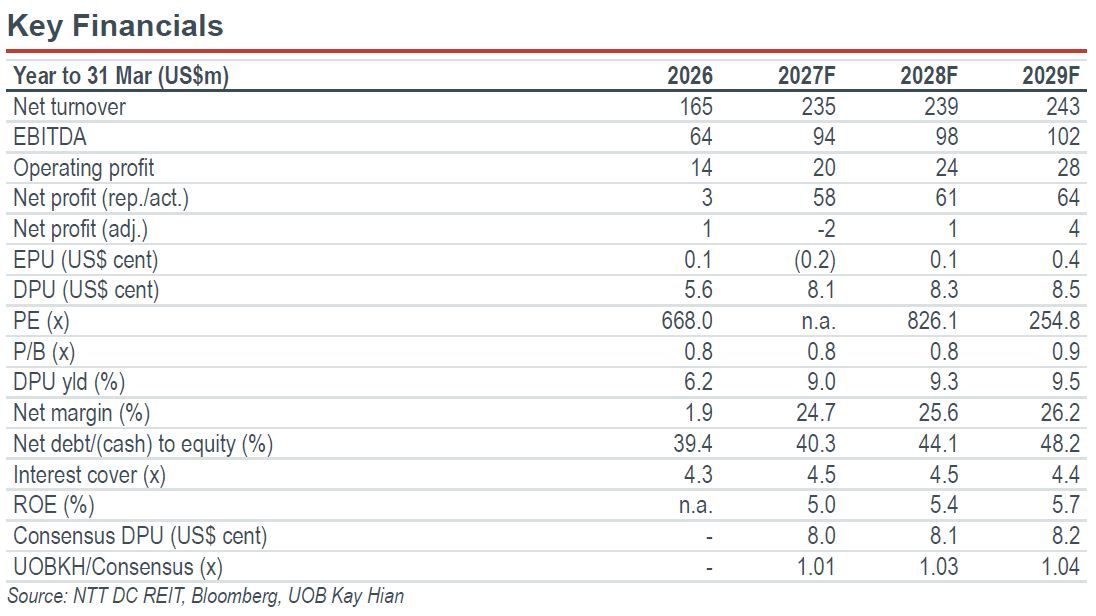
- We raised our FY27 and FY28 DPU forecasts by 2% due to cost reduction. Re-iterate BUY for its attractive DPU yield of 9.0% for FY27 and 9.3% for FY28. Target price: US$1.31.
Analysis
- Expanding in Europe to increase exposure to Tier 1 markets. NTT DC REIT (NTTDCR) plans to acquire a hyperscale 24MW data centre (DC) in Frankfurt, Germany valued at US$450m-500m in 2HFY27. The DC is anchored by two US-based hyperscalers with a long WALE of 10 years and is expected to provide an NPI yield of above 6%. Frankfurt is the largest DC market in Europe. After the acquisition, the mix between Tier 1 and secondary markets could shift from 32:68 to 48:52. Likewise, the reliance on the US market, which includes its DCs in Northern Virginia (VA2) and Sacramento (CA1, CA2 and CA3), would be reduced from 64% to 49% of portfolio valuation.
- Building NTTDCR into a viable offtake vehicle. NTTDCR has a global right of first refusal over its sponsor’s stabilised DCs covering more than 160 properties in operation with a total IT load of 1,630MW. NTTDCR and its sponsor are currently preparing the Frankfurt DC to be carved out, including local regulatory approvals and tax planning strategies.
- Leasing momentum supports occupancy growth. Portfolio occupancy by IT load improved 0.8ppt qoq to 95.9% as of Jun 26, driven by expansion leases secured at CA1, CA3 and SG1. Including committed new leases that have yet to commence, occupancy would have increased 3.3ppt to 99.2%. Management highlighted that the bulk of new leases previously secured are expected to commence revenue contribution starting from 3QFY27, providing a further earnings uplift in the upcoming quarters.
Highlights
- NTTDCR aims to expand in Europe to increase its exposure to Tier 1 markets. It has debt headroom of US$261m based on a gearing of 40%, which could be utilised to acquire a hyperscale 24MW DC in Frankfurt, Germany in 2HFY27.
- NTTDCR is the first data centre REIT to link payment of performance fee to DPU growth and set a stringent minimum threshold for DPU growth of 3%. Unitholders’ interest is protected as new units issued for payment of management fees is priced at NAV or higher. The restructuring incentivises DPU growth and increases alignment with unitholders’ interest.
- We raised our FY27 and FY28 DPU forecasts by 2% due to cost reduction. Re-iterate BUY for its attractive DPU yield of 9.0% for FY27 and 9.3% for FY28. Target price: US$1.31.
Analysis
- Expanding in Europe to increase exposure to Tier 1 markets. NTT DC REIT (NTTDCR) plans to acquire a hyperscale 24MW data centre (DC) in Frankfurt, Germany valued at US$450m-500m in 2HFY27. The DC is anchored by two US-based hyperscalers with a long WALE of 10 years and is expected to provide an NPI yield of above 6%. Frankfurt is the largest DC market in Europe. After the acquisition, the mix between Tier 1 and secondary markets could shift from 32:68 to 48:52. Likewise, the reliance on the US market, which includes its DCs in Northern Virginia (VA2) and Sacramento (CA1, CA2 and CA3), would be reduced from 64% to 49% of portfolio valuation.
- Building NTTDCR into a viable offtake vehicle. NTTDCR has a global right of first refusal over its sponsor’s stabilised DCs covering more than 160 properties in operation with a total IT load of 1,630MW. NTTDCR and its sponsor are currently preparing the Frankfurt DC to be carved out, including local regulatory approvals and tax planning strategies.
- Leasing momentum supports occupancy growth. Portfolio occupancy by IT load improved 0.8ppt qoq to 95.9% as of Jun 26, driven by expansion leases secured at CA1, CA3 and SG1. Including committed new leases that have yet to commence, occupancy would have increased 3.3ppt to 99.2%. Management highlighted that the bulk of new leases previously secured are expected to commence revenue contribution starting from 3QFY27, providing a further earnings uplift in the upcoming quarters.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$0.90
US$1.31
+45.6%
US$1.29
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

24 Aug 2026
NTT DC REIT (NTTDCR SP): 1QFY27: A Journey Of A Thousand Miles Begins With A Single Step

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

6 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Disciplined Reconstitution To Pivot Towards The Living Sector
Our latest research
13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

12 Oct 2026
Food Empire Holdings (FEH SP) - Meeting Highlights: Strong Brand Equity Supports Inflation Resilience; Russian Risks Warrant Differentiated Assessment

9 Oct 2026