
Company Coverage
SATS (SATS SP): 1HFY27: Steady Headline Earnings Supported By Tax Items; Cost Pressures Peak, Margins Poised To Recover
BUY (Maintained)
Current price:
Target price:
Upside:
S$4.17
S$5.00
19.9%
Analyst
Highlights
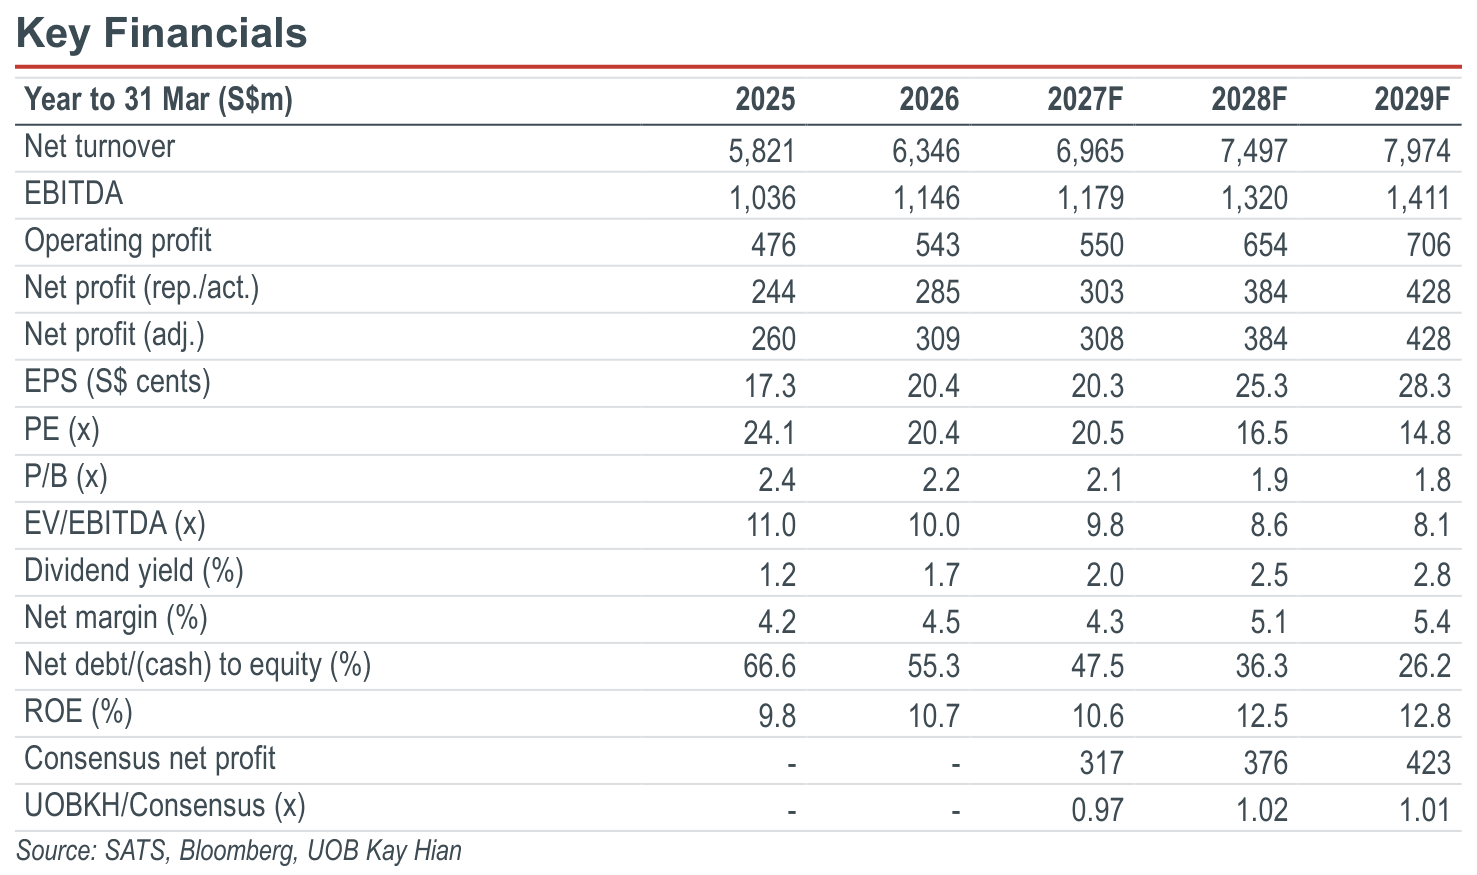
- SATS recorded steady headline earnings in 1HFY27, supported by one-off tax items. Excluding all one-offs, core earnings dropped 9.9% yoy in 2QFY27.
- The weaker 2QFY27 core earnings should not be a concern, as the 2QFY27 margin weakness, caused by transitory cost pressures, has been well guided.
- Management is incrementally more positive, noting that cost pressures are likely to have peaked and margins should be on a recovery trend.
- Maintain BUY with an unchanged target price of S$5.00. We like SATS for its strong business fundamentals and upbeat medium-term growth trajectory.
Analysis
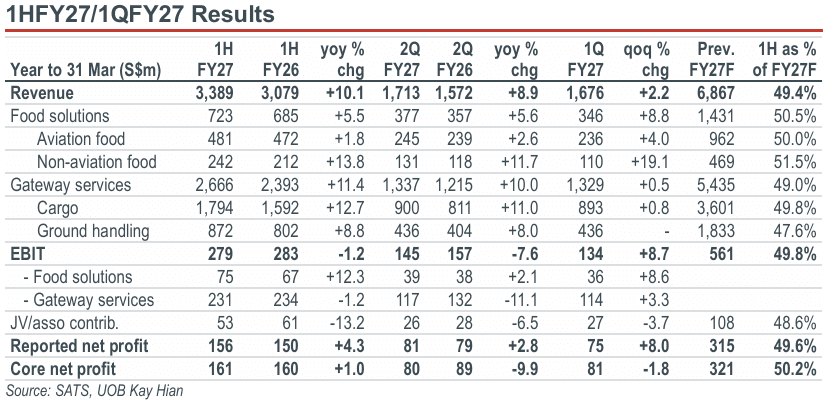
- Steady headline performance supported by tax items. SATS’ headline net profit rose 4.3% yoy to S$156m in 1HFY27, helped by a 22% yoy, or S$15.4m, decline in tax expense. This reflected the reversal of prior-year tax overprovisions in 1HFY27, compared with top-up provisions for prior years in 1HFY26. Adjusting for all one-off items, including these tax provision adjustments, we estimate that SATS’ core earnings rose 1.0% yoy in 1HFY27 (supported by a strong 1QFY27 core performance), but dropped 9.9% yoy in 2QFY27.
Highlights
- SATS recorded steady headline earnings in 1HFY27, supported by one-off tax items. Excluding all one-offs, core earnings dropped 9.9% yoy in 2QFY27.
- The weaker 2QFY27 core earnings should not be a concern, as the 2QFY27 margin weakness, caused by transitory cost pressures, has been well guided.
- Management is incrementally more positive, noting that cost pressures are likely to have peaked and margins should be on a recovery trend.
- Maintain BUY with an unchanged target price of S$5.00. We like SATS for its strong business fundamentals and upbeat medium-term growth trajectory.
Analysis
- Steady headline performance supported by tax items. SATS’ headline net profit rose 4.3% yoy to S$156m in 1HFY27, helped by a 22% yoy, or S$15.4m, decline in tax expense. This reflected the reversal of prior-year tax overprovisions in 1HFY27, compared with top-up provisions for prior years in 1HFY26. Adjusting for all one-off items, including these tax provision adjustments, we estimate that SATS’ core earnings rose 1.0% yoy in 1HFY27 (supported by a strong 1QFY27 core performance), but dropped 9.9% yoy in 2QFY27.
BUY (Maintained)
Current price:
Target price:
Upside:
S$4.17
S$5.00
19.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

24 Sept 2026
Yangzijiang Shipbuilding (YZJSGD SP): Expect Strong 2H26 Order Win Momentum Underpinned By Active Enquiry Pipeline; Earnings Visibility Extending Into 2030

13 Nov 2026
Singapore Airlines (SIA SP): 1HFY27: Results Miss Our Expectations; Expect 2HFY27 To Remain Weighed Down By Elevated Jet Fuel Prices
Our latest research

13 Nov 2026
Food Empire Holdings (FEH SP): 3Q26: Healthy Growth; Expect Better Margins And Earnings hoh For 2H26

13 Nov 2026
Genting Singapore (GENS SP): 3Q26: Dragged By Weaker Gaming Operations
13 Nov 2026