
Company Coverage
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.92
S$3.60
+23.3%
S$3.75
Analyst
Highlights
- 1HFY27 net profit of S$81.9m (-1.7% yoy) is in line with our expectations, forming 48% of our full-year forecast.
- Underlying earnings growth was masked by higher gestation costs at its engine JV SAESL. Excluding the gestation costs for SAESL, we estimate that SIAEC’s earnings would have improved by close to 20% yoy.
- SIAEC continues to push capacity and regional expansion, which come with near-term gestation pains. That said, gestation costs are expected to peak in FY27 and taper from FY28 onwards, driving a medium-term earnings growth.
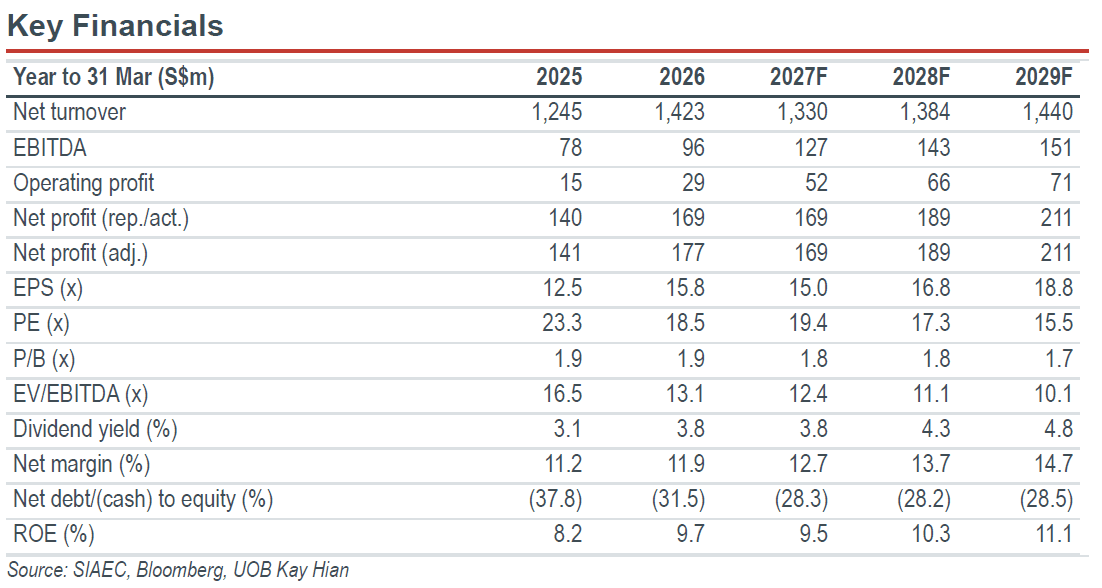
- Maintain BUY, with a slightly lower target price of S$3.60, based on 21.3x FY28F PE (pegged to its historical mean).
Analysis
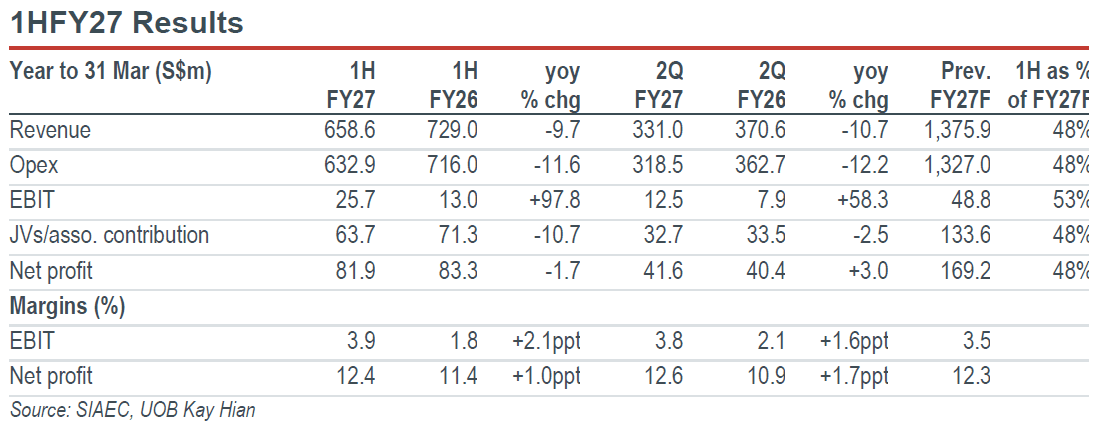
Results in line. SIA Engineering’s (SIAEC) 1HFY27 results are in line with our expectations, with reported net profit of S$81.9m (-1.7% yoy), forming 48% of our full-year forecast. Operating profit almost doubled yoy to S$25.7m, driven by healthy business volumes and lower gestation losses related to expansion. However, the improvement in operating performance was offset by weaker contributions from JVs and associates (S$63.7m in 1HFY27, down 10.7% yoy), lower net interest income and higher tax expenses. SIAEC maintained its interim dividend at 2.5 S cents per share for 1HFY27.
Highlights
- 1HFY27 net profit of S$81.9m (-1.7% yoy) is in line with our expectations, forming 48% of our full-year forecast.
- Underlying earnings growth was masked by higher gestation costs at its engine JV SAESL. Excluding the gestation costs for SAESL, we estimate that SIAEC’s earnings would have improved by close to 20% yoy.
- SIAEC continues to push capacity and regional expansion, which come with near-term gestation pains. That said, gestation costs are expected to peak in FY27 and taper from FY28 onwards, driving a medium-term earnings growth.
- Maintain BUY, with a slightly lower target price of S$3.60, based on 21.3x FY28F PE (pegged to its historical mean).
Analysis
Results in line. SIA Engineering’s (SIAEC) 1HFY27 results are in line with our expectations, with reported net profit of S$81.9m (-1.7% yoy), forming 48% of our full-year forecast. Operating profit almost doubled yoy to S$25.7m, driven by healthy business volumes and lower gestation losses related to expansion. However, the improvement in operating performance was offset by weaker contributions from JVs and associates (S$63.7m in 1HFY27, down 10.7% yoy), lower net interest income and higher tax expenses. SIAEC maintained its interim dividend at 2.5 S cents per share for 1HFY27.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.92
S$3.60
+23.3%
S$3.75
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
NetLink NBN Trust (NETLINK SP) - 1HFY27: EBITDA In Line; Higher Depreciation A Drag To Earnings

16 Sept 2026
Singapore Airlines (SIA SP): Near-term Outlook Clouded By Elevated Jet Fuel Prices Amid Middle East Tensions

30 Oct 2026
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue
Our latest research

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

5 Nov 2026
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income

5 Nov 2026