
Company Coverage
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.38
S$0.70
+84.2%
S$0.75
Analyst
Highlights
- 9M26 revenue of S$84.3m and PATMI of S$7.8m met 77.3% and 76.6% of our 2026 forecasts respectively, slightly ahead of expectations.
- 3Q26 gross margin recovered and jumped to 38.1%, while S$71.2m of remaining contracted work supports revenue visibility beyond 2026.
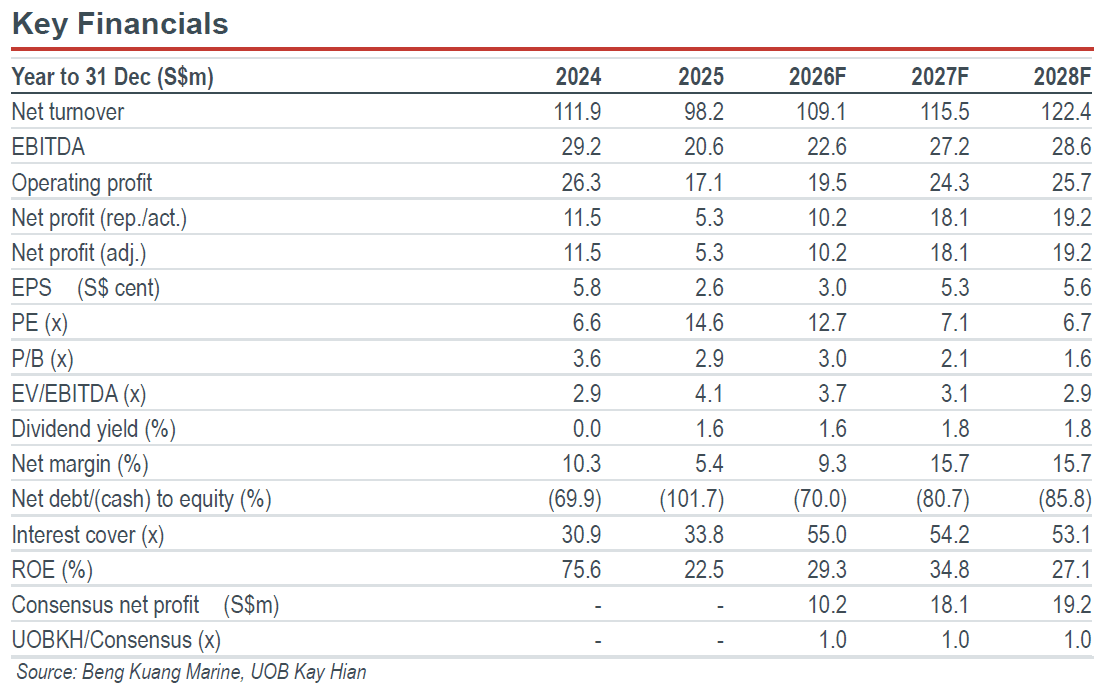
- Maintain BUY with a lower S$0.70 target price on 13.1x 2027F PE, 1.0 SD above its historical mean, representing an 84% upside.
Analysis
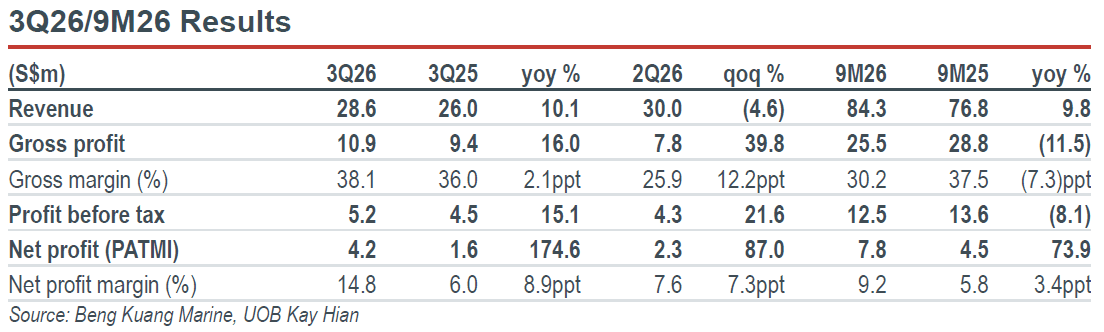
- Offshore execution restores margins. 3Q26 revenue rose 10.1% yoy to S$28.6m and PATMI surged 174.6% to S$4.2m, meeting 26.2% and 41.8% of our 2026 forecasts respectively. West Africa Basin execution and later-stage Batam deliveries, alongside higher operational efficiencies, lifted 3Q26 gross profit 16.0% to S$10.9m and 3Q26 PBT 15.1% to S$5.2m, while 3Q26 EBITDA margin excluding other gains and losses reached 22.8% (3Q25: 18.2%). 9M26 revenue and PATMI grew 9.8% and 73.9% yoy to S$84.3m and S$7.8m respectively, meeting 77.3% and 76.6% of our full-year forecasts, slightly ahead of expectations.
- Full ASOM ownership boosts earnings attribution. 3Q26 was the first full quarter of 100% ownership following the May acquisition of the remaining 49%. Non-controlling interests fell to S$0.04m from S$1.51m in 3Q25, helping PATMI outpace PBT growth. We expect 3Q26 results to be a good baseline to annualise Beng Kuang Marine’s (BKM) full-year result for 2027. 2027 will be the first full year of full ASOM earnings ownership.
Highlights
- 9M26 revenue of S$84.3m and PATMI of S$7.8m met 77.3% and 76.6% of our 2026 forecasts respectively, slightly ahead of expectations.
- 3Q26 gross margin recovered and jumped to 38.1%, while S$71.2m of remaining contracted work supports revenue visibility beyond 2026.
- Maintain BUY with a lower S$0.70 target price on 13.1x 2027F PE, 1.0 SD above its historical mean, representing an 84% upside.
Analysis
- Offshore execution restores margins. 3Q26 revenue rose 10.1% yoy to S$28.6m and PATMI surged 174.6% to S$4.2m, meeting 26.2% and 41.8% of our 2026 forecasts respectively. West Africa Basin execution and later-stage Batam deliveries, alongside higher operational efficiencies, lifted 3Q26 gross profit 16.0% to S$10.9m and 3Q26 PBT 15.1% to S$5.2m, while 3Q26 EBITDA margin excluding other gains and losses reached 22.8% (3Q25: 18.2%). 9M26 revenue and PATMI grew 9.8% and 73.9% yoy to S$84.3m and S$7.8m respectively, meeting 77.3% and 76.6% of our full-year forecasts, slightly ahead of expectations.
- Full ASOM ownership boosts earnings attribution. 3Q26 was the first full quarter of 100% ownership following the May acquisition of the remaining 49%. Non-controlling interests fell to S$0.04m from S$1.51m in 3Q25, helping PATMI outpace PBT growth. We expect 3Q26 results to be a good baseline to annualise Beng Kuang Marine’s (BKM) full-year result for 2027. 2027 will be the first full year of full ASOM earnings ownership.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.38
S$0.70
+84.2%
S$0.75
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

9 Oct 2026
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

3 Nov 2026
Lendlease Global Commercial REIT (LREIT SP) - 1QFY27: Retail Momentum Builds; Planning More AEIs
Our latest research

5 Nov 2026
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income
5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

5 Nov 2026