
Company Coverage
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.38
S$3.80
+59.7%
S$4.05
Analyst
Highlights
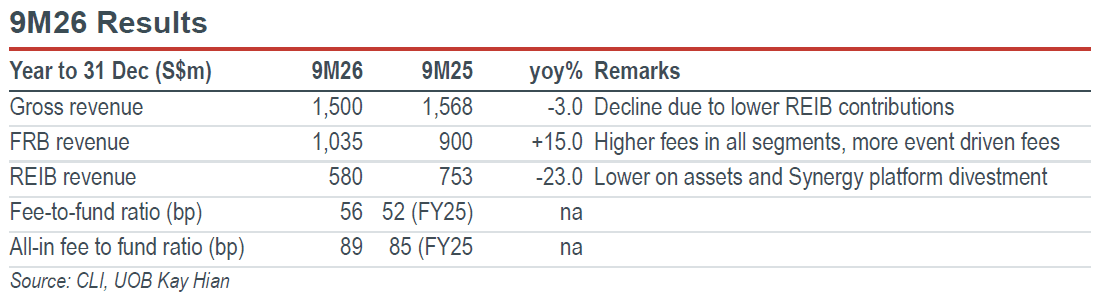
- CLI’s 9M26 revenue dipped 3% yoy to S$1.5b due to a 23% yoy decline in real estate investment business (REIB) income, largely offset by higher contributions from its stakes in listed and private funds and strong expansion in fee income (+15% yoy to S$1.035b). Fee-related business (FRB) revenue was mainly lifted by a 30% yoy growth in listed fund management fees and a 32% higher private funds management income.
- CLI established FeeCo and AssetCo to sharpen growth focus. FeeCo aims to scale a dual growth engine from listed and private funds to grow recurring income and leverage on commercial and lodging management business to drive fees and asset performance. AssetCo would focus on monetisation through capital recycling platforms including C-REITs, P-REITs and RMB Master Funds as third party sales and to pursue longer-term strategic pathways for China AssetCo. Maintain BUY. Target price: S$3.80.
Analysis
- Continued scaling up of fee business. CapitaLand Investment Limited (CLI) indicated it raised S$4.3b in equity through its listed and private funds and deployed S$9.6b and divested S$5.7b of assets from Jan to Nov 26. We think this multi-pronged fund growth strategy should enable it to continue scaling up its fee business.
Highlights
- CLI’s 9M26 revenue dipped 3% yoy to S$1.5b due to a 23% yoy decline in real estate investment business (REIB) income, largely offset by higher contributions from its stakes in listed and private funds and strong expansion in fee income (+15% yoy to S$1.035b). Fee-related business (FRB) revenue was mainly lifted by a 30% yoy growth in listed fund management fees and a 32% higher private funds management income.
- CLI established FeeCo and AssetCo to sharpen growth focus. FeeCo aims to scale a dual growth engine from listed and private funds to grow recurring income and leverage on commercial and lodging management business to drive fees and asset performance. AssetCo would focus on monetisation through capital recycling platforms including C-REITs, P-REITs and RMB Master Funds as third party sales and to pursue longer-term strategic pathways for China AssetCo. Maintain BUY. Target price: S$3.80.
Analysis
- Continued scaling up of fee business. CapitaLand Investment Limited (CLI) indicated it raised S$4.3b in equity through its listed and private funds and deployed S$9.6b and divested S$5.7b of assets from Jan to Nov 26. We think this multi-pronged fund growth strategy should enable it to continue scaling up its fee business.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$2.38
S$3.80
+59.7%
S$4.05
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing

29 Sept 2026
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze
Our latest research

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

5 Nov 2026