
Company Coverage
Seatrium (STM SP): Steady Operational Performance in 3Q26 With Improving Margins; Weak Orderbook Remains A Concern
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.71
S$1.80
5.2%
S$2.30
Analyst
Highlights
- Seatrium reported a steady operating performance in 3Q26, maintaining its revenue run rate and sustaining the improvement in gross margins.
- Order win momentum picked up slightly in recent months, but remained weak, with 2026 ytd order wins of S$1.7b implying an annualised book-to-bill ratio of less than 0.3x. As a result, orderbook on hand weakened qoq to S$12.2b.
- Management continues to pursue a pipeline of opportunities, although the timing of clients’ final investment decision remains uncertain.
- Maintain HOLD, with a lower target price of S$1.80 based on 0.82x 2026F P/B (1SD below historical mean P/B of 1.05x). Seatrium needs some sizeable contract wins in the next few months to bolster investor confidence.
Analysis
- Operational performance remained steady in 3Q26. Management sees revenue maintaining its run rate in 3Q26 and gross margin continuing to improve relative to 1H26. Management expects the margin expansion to continue for the rest of the year and to sustain into 2027, driven by improving project margin mix, continued cost discipline and progressive cost savings associated with ongoing non-core divestments.
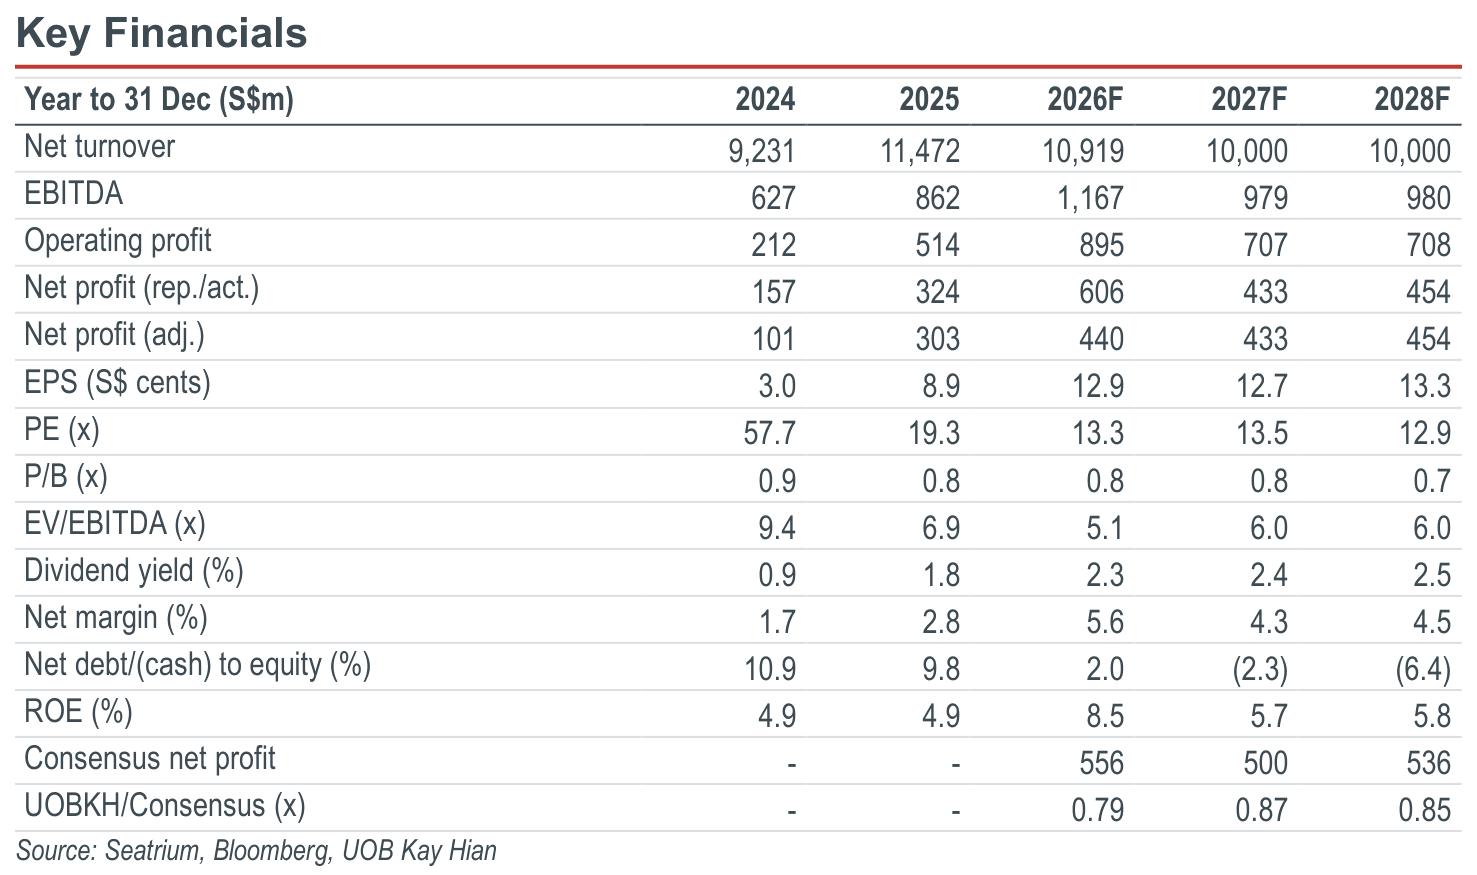
- Maintaining guidance for a strong closing to 2026. Given the near-term revenue visibility and margin improvement expectations, Seatrium has maintained the guidance that its underlying 2026 net profit is expected to be materially higher than 2025’s. This is reflected in our 2H26 core earnings forecast of S$234m (+56% yoy, +13% hoh).
- Weak orderbook remains a key issue. Orderbook weakened further to S$12.2b, from S$13.3b as of end-1H26, or S$17.8b as of end-25. The current orderbook, equivalent to less than 1.5 years’ burn, provides very limited revenue/earnings visibility. In addition, over 70% of the net orderbook value comes from projects with delivery dates extending beyond 2029, and hence a sizeable portion of the orderbook value from these projects is unlikely to be billed to customers in the next two years.
Highlights
- Seatrium reported a steady operating performance in 3Q26, maintaining its revenue run rate and sustaining the improvement in gross margins.
- Order win momentum picked up slightly in recent months, but remained weak, with 2026 ytd order wins of S$1.7b implying an annualised book-to-bill ratio of less than 0.3x. As a result, orderbook on hand weakened qoq to S$12.2b.
- Management continues to pursue a pipeline of opportunities, although the timing of clients’ final investment decision remains uncertain.
- Maintain HOLD, with a lower target price of S$1.80 based on 0.82x 2026F P/B (1SD below historical mean P/B of 1.05x). Seatrium needs some sizeable contract wins in the next few months to bolster investor confidence.
Analysis
- Operational performance remained steady in 3Q26. Management sees revenue maintaining its run rate in 3Q26 and gross margin continuing to improve relative to 1H26. Management expects the margin expansion to continue for the rest of the year and to sustain into 2027, driven by improving project margin mix, continued cost discipline and progressive cost savings associated with ongoing non-core divestments.
- Maintaining guidance for a strong closing to 2026. Given the near-term revenue visibility and margin improvement expectations, Seatrium has maintained the guidance that its underlying 2026 net profit is expected to be materially higher than 2025’s. This is reflected in our 2H26 core earnings forecast of S$234m (+56% yoy, +13% hoh).
- Weak orderbook remains a key issue. Orderbook weakened further to S$12.2b, from S$13.3b as of end-1H26, or S$17.8b as of end-25. The current orderbook, equivalent to less than 1.5 years’ burn, provides very limited revenue/earnings visibility. In addition, over 70% of the net orderbook value comes from projects with delivery dates extending beyond 2029, and hence a sizeable portion of the orderbook value from these projects is unlikely to be billed to customers in the next two years.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.71
S$1.80
5.2%
S$2.30
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

16 Nov 2026
Singapore Technologies Engineering (STE SP): 3Q26: Revenue Broadly In Line; Expect Strong Closing For 2026 And Sustainable Healthy Growth In the Medium Term

12 Nov 2026
Yangzijiang Shipbuilding (YZJSGD SP): Strong New Contract Wins Bring Orderbook To A New Record-high Level, Extending Earnings Visibility Through 2030
Our latest research

20 Nov 2026
Frencken Group (FRKN SP): 3Q26: Strong Momentum; More Positive Growth Outlook

19 Nov 2026
Riverstone Holdings (RSTON SP): 3Q26: Increased Capacity And Consumables To Drive Future Growth

18 Nov 2026