
Company Coverage
Frencken Group (FRKN SP): 3Q26: Strong Momentum; More Positive Growth Outlook
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.70
S$2.15
26.5%
S$3.30
Analyst
Highlights
- 9M26 revenue and PATMI rose to S$666m (+3.6% yoy) and S$32m (+8.1% yoy), and accounted for 71.6% and 71.5% of our full-year forecasts respectively, in line with expectations.
- 3Q26 revenue rose 12.8% yoy to S$239m, driven by semiconductor (+25.9% yoy) and medical (+26.1% yoy) growth.
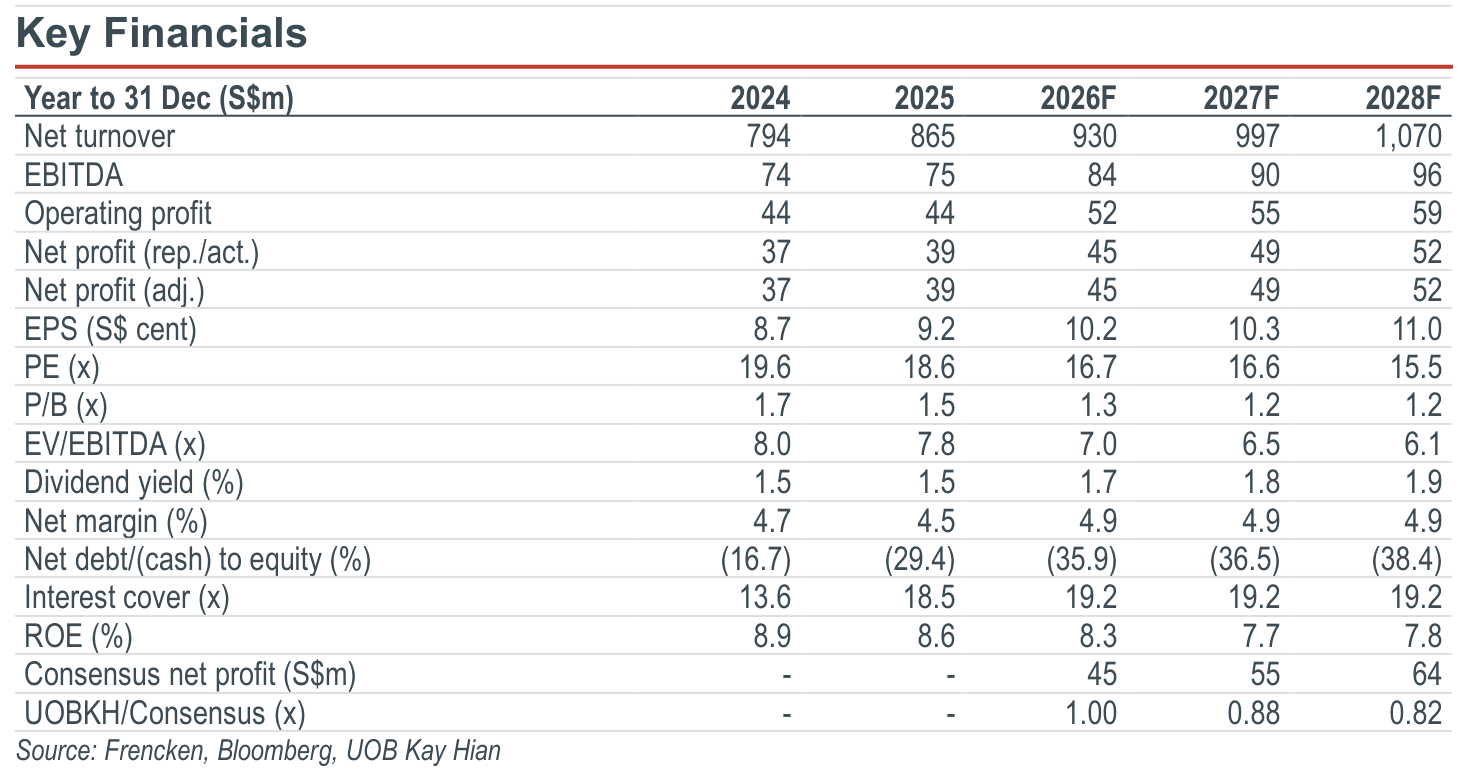
- Frencken expects 2H26 revenue to improve yoy and hoh. The strong momentum is expected to continue into 2027. Maintain BUY. Target price: S$2.15.
Analysis
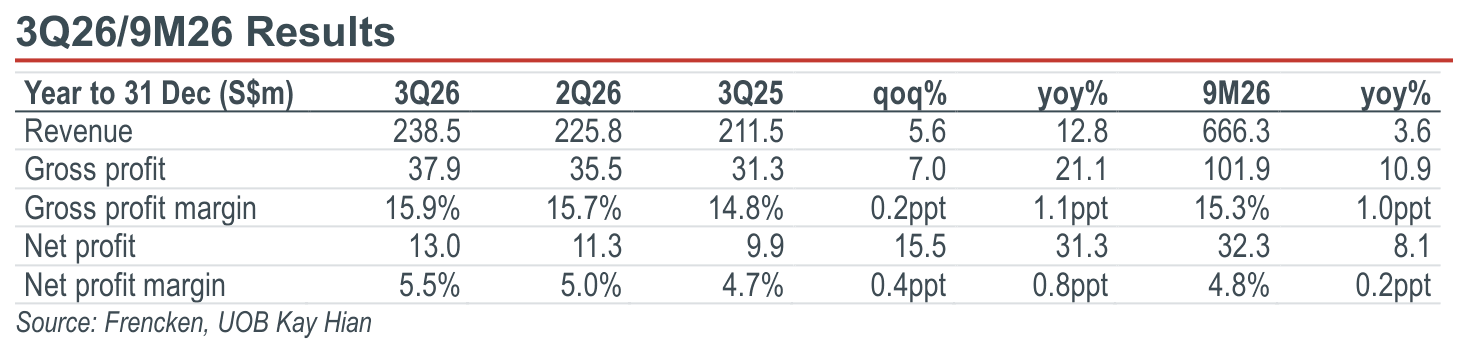
- 9M26 results broadly in line with expectations. Frencken reported 3Q26 revenue of S$238.5m (+12.8% yoy, +5.6% qoq), driven by strong semiconductor sales in Asia and improving business activities in Europe. PATMI rose 31.3% yoy and 15.5% qoq to S$13.0m, supported by gross margin expanding 1.1ppt yoy to 15.9%. 9M26 revenue and PATMI increased 3.6% and 8.1% yoy to S$666.3m and S$32.3m respectively, representing 71.6% and 71.5% of our full-year forecasts.
- Semiconductor and medical segments drove revenue growth. The mechatronics division's 3Q26 revenue rose 13.4% yoy to S$214.3m, driven by semiconductor (+25.9% yoy to S$124.8m) and medical (+26.1% yoy to S$39.9m) sales. Semiconductor growth was supported by strong Asian sales and sequential improvements in Europe, while medical benefitted from higher European orders. Meanwhile, analytical life sciences (-8.6% yoy) and industrial automation (-39.9% yoy) declined due to softer European demand and lower orders from a major customer. Automotive revenue rose 10.0% yoy to S$17.2m on higher radar antenna sales.
- Positive 2H26 outlook maintained; semiconductor remains key growth driver. Management expects 2H26 and 2026 revenue and net profit to increase yoy, supported by strong customer demand. Semiconductor growth in Asia will be driven by additional customer programmes, while Europe continues to recover despite supply constraints.
Highlights
- 9M26 revenue and PATMI rose to S$666m (+3.6% yoy) and S$32m (+8.1% yoy), and accounted for 71.6% and 71.5% of our full-year forecasts respectively, in line with expectations.
- 3Q26 revenue rose 12.8% yoy to S$239m, driven by semiconductor (+25.9% yoy) and medical (+26.1% yoy) growth.
- Frencken expects 2H26 revenue to improve yoy and hoh. The strong momentum is expected to continue into 2027. Maintain BUY. Target price: S$2.15.
Analysis
- 9M26 results broadly in line with expectations. Frencken reported 3Q26 revenue of S$238.5m (+12.8% yoy, +5.6% qoq), driven by strong semiconductor sales in Asia and improving business activities in Europe. PATMI rose 31.3% yoy and 15.5% qoq to S$13.0m, supported by gross margin expanding 1.1ppt yoy to 15.9%. 9M26 revenue and PATMI increased 3.6% and 8.1% yoy to S$666.3m and S$32.3m respectively, representing 71.6% and 71.5% of our full-year forecasts.
- Semiconductor and medical segments drove revenue growth. The mechatronics division's 3Q26 revenue rose 13.4% yoy to S$214.3m, driven by semiconductor (+25.9% yoy to S$124.8m) and medical (+26.1% yoy to S$39.9m) sales. Semiconductor growth was supported by strong Asian sales and sequential improvements in Europe, while medical benefitted from higher European orders. Meanwhile, analytical life sciences (-8.6% yoy) and industrial automation (-39.9% yoy) declined due to softer European demand and lower orders from a major customer. Automotive revenue rose 10.0% yoy to S$17.2m on higher radar antenna sales.
- Positive 2H26 outlook maintained; semiconductor remains key growth driver. Management expects 2H26 and 2026 revenue and net profit to increase yoy, supported by strong customer demand. Semiconductor growth in Asia will be driven by additional customer programmes, while Europe continues to recover despite supply constraints.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.70
S$2.15
26.5%
S$3.30
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth
Our latest research

20 Nov 2026
Seatrium (STM SP): Steady Operational Performance in 3Q26 With Improving Margins; Weak Orderbook Remains A Concern

19 Nov 2026
Riverstone Holdings (RSTON SP): 3Q26: Increased Capacity And Consumables To Drive Future Growth

18 Nov 2026