Company Coverage
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt32.00
Bt35.20
10.00%
Bt32.50
Analyst
Highlights
- We expect COM7 to report a 49% yoy increase in its 3Q26 net profit, driven by growth in both retail and other businesses.
- 4Q26 earnings are expected to grow yoy, supported by higher iPhone ASPs and continued growth in UFund and iCare.
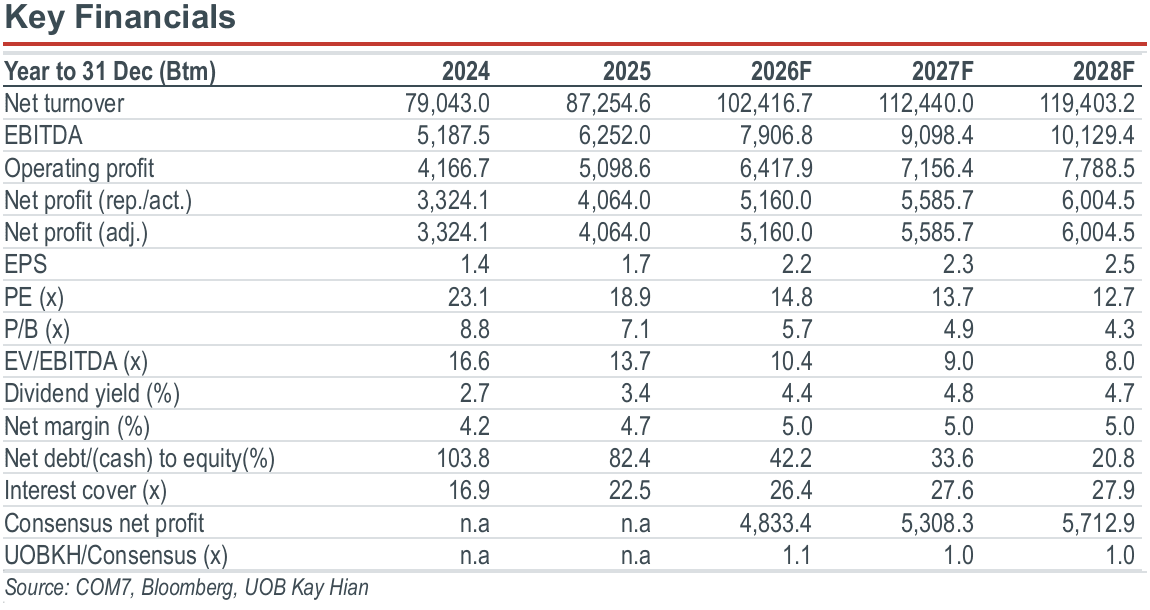
- Maintain BUY with a higher target price of Bt35.20 (from 32.50), reflecting an 8% upward revision to our earnings forecasts.
Analysis
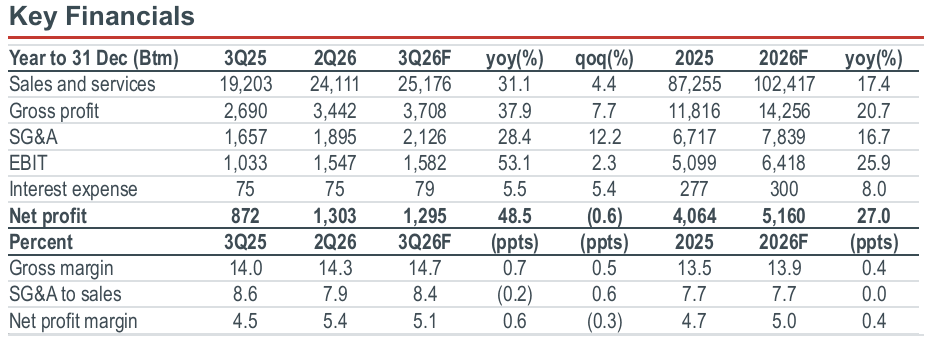
- Earnings to surge in 3Q26. We expect COM7 to report 3Q26 net profit of Bt1.29b, up 49% yoy and flat qoq, driven by growth in both its retail and other businesses. The strong earnings are expected to be supported by: a) a 31% yoy increase in sales, driven by panic buying of the iPhone 17 ahead of the price increase, with higher ASPs more than offsetting lower shipment volume, alongside strong growth in other businesses, particularly UFund and iCare; b) a 70bps yoy expansion in gross margin, driven by higher contribution from other businesses; c) a lower SG&A-to-sales ratio, supported by improving SSSG; and d) a slight increase in interest expenses following higher borrowings to fund the expansion of other businesses.
- 4Q26 earnings to grow at a normalised pace. We expect 4Q26 earnings to grow yoy, supported by higher iPhone ASPs, which should more than offset lower shipment volume, and continued growth in UFund and iCare. UFund earnings should benefit from loan portfolio expansion with controllable asset quality, while iCare should gain from a larger insurance portfolio. However, earnings momentum may be slower than that of 3Q26 due to front-loaded demand for entry-level iPhones and supply shortages in the entry-level smartphone segment, partly related to the delayed launch of the iPhone 18.
Highlights
- We expect COM7 to report a 49% yoy increase in its 3Q26 net profit, driven by growth in both retail and other businesses.
- 4Q26 earnings are expected to grow yoy, supported by higher iPhone ASPs and continued growth in UFund and iCare.
- Maintain BUY with a higher target price of Bt35.20 (from 32.50), reflecting an 8% upward revision to our earnings forecasts.
Analysis
- Earnings to surge in 3Q26. We expect COM7 to report 3Q26 net profit of Bt1.29b, up 49% yoy and flat qoq, driven by growth in both its retail and other businesses. The strong earnings are expected to be supported by: a) a 31% yoy increase in sales, driven by panic buying of the iPhone 17 ahead of the price increase, with higher ASPs more than offsetting lower shipment volume, alongside strong growth in other businesses, particularly UFund and iCare; b) a 70bps yoy expansion in gross margin, driven by higher contribution from other businesses; c) a lower SG&A-to-sales ratio, supported by improving SSSG; and d) a slight increase in interest expenses following higher borrowings to fund the expansion of other businesses.
- 4Q26 earnings to grow at a normalised pace. We expect 4Q26 earnings to grow yoy, supported by higher iPhone ASPs, which should more than offset lower shipment volume, and continued growth in UFund and iCare. UFund earnings should benefit from loan portfolio expansion with controllable asset quality, while iCare should gain from a larger insurance portfolio. However, earnings momentum may be slower than that of 3Q26 due to front-loaded demand for entry-level iPhones and supply shortages in the entry-level smartphone segment, partly related to the delayed launch of the iPhone 18.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt32.00
Bt35.20
10.00%
Bt32.50
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


