
Periodic/Sector reports
China Property: Oct 26: Supply Keeps Contracting While Sales Diverge, With Tier 1 And Second-hand Homes Ahead
UNDERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- Supply continued to contract. MOF data showed land sales revenue fell 27.9% yoy in 9M26, with the decline gradually narrowing. Tier 1 inventory months decreased further in Oct 26, led by Beijing, where they dropped by 1.0 month and saleable GFA dropped 3.4% mtd.
- On the demand side, sales diverged among cities and markets. High frequency data for 1-25 Oct 26 showed Tier 1 still leading, though new-home growth slowed: new-home sales rose 2% yoy in four Tier 1 cities and fell 23% in nine Tier 2 cities, while second-hand sales grew 22% yoy in three Tier 1 cities and declined 1% in eight Tier 2 cities. ICE listing prices edged down 0.6% mom.
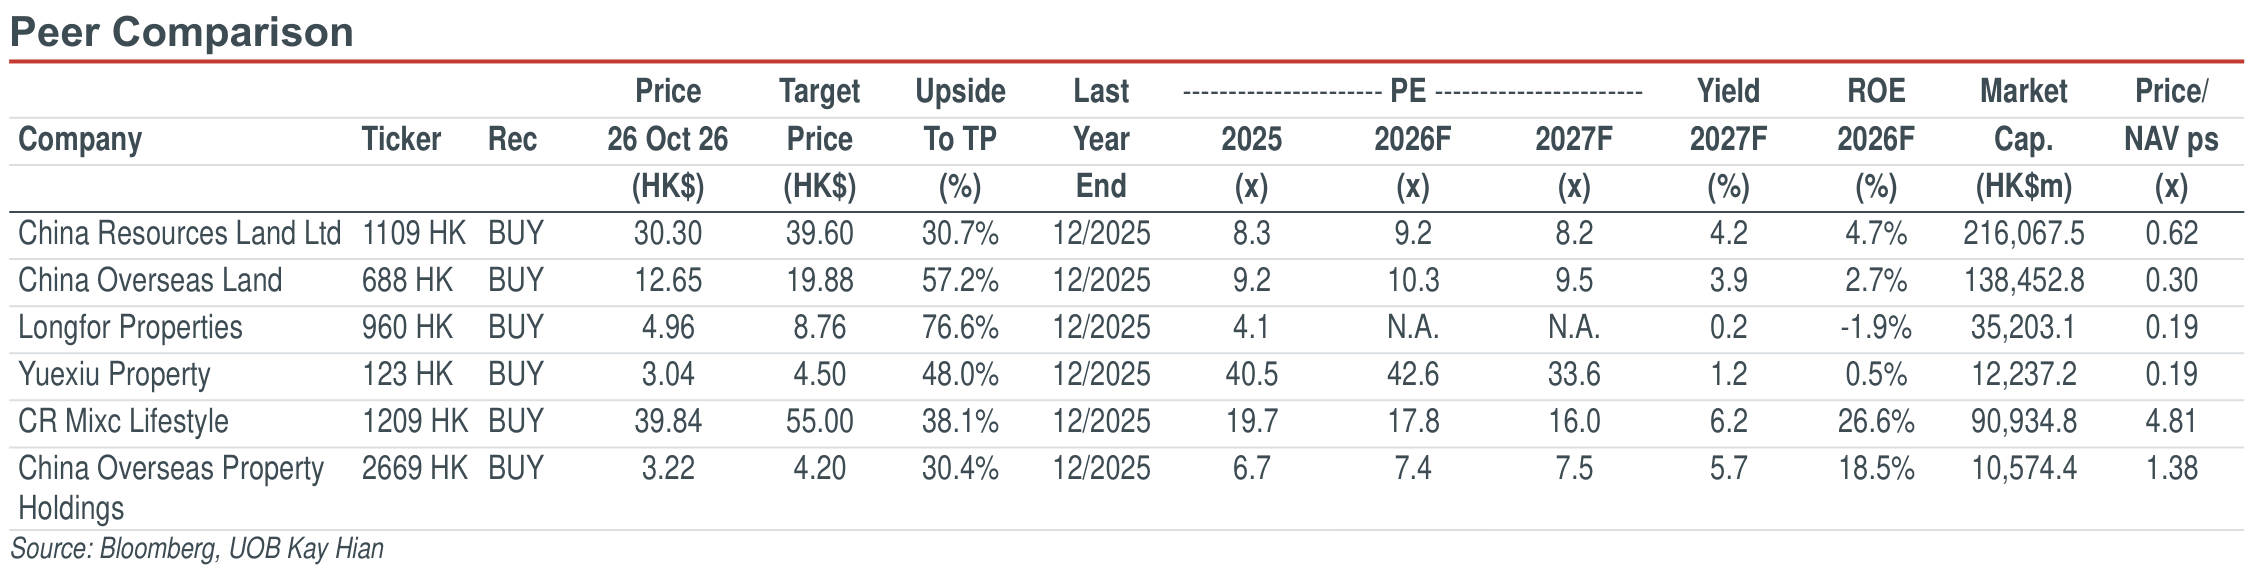
- Maintain UNDERWEIGHT. Our top picks are COLI and CR Mixc.
Analysis
- Supply continued to contract, with land sales revenue falling 27.9% yoy in 9M26... According to the MOF, land sales revenue was Rmb1,608.7b in 9M26, and the cumulative decline narrowed from 30.8% in 7M26 and 28.6% in 8M26. Derived from the cumulative figures, Sep 26 land sales revenue was about Rmb233.4b, down 23.2% yoy, a smaller drop than the 9M26 average.
- …while saleable GFA in Tier 1 inventory months declined further in Oct 26, led by Beijing. As of 25 Oct 26, saleable GFA in Beijing/Shanghai/ Guangzhou/Shenzhen changed by -20.0%/-5.5%/-11.3%/-37.4% yoy respectively, and inventory months dropped 3.2/1.2/1.7/7.7 months ytd to 17.1/7.7/16.1/15.9 months. Since end-Sep 26, Beijing’s saleable GFA has decreased 3.4% and its inventory months have gone down by 1.0 month, while the other three cities have each seen declines of less than 0.2 months.
- On the demand side, sales diverged among cities and markets. Property sales continued to show the following trends in October: a) Tier 1 cities outperformed Tier 2 cities, and b) the secondary market outperformed the new-home market. In our view, this reflects continued divergence across market segments amid relatively weak overall demand. a) During 1-25 Oct 26, new-home sales rose 2% yoy in four Tier 1 cities and declined 23% yoy in nine Tier 2 cities. Among Tier 1 cities, Beijing/Shanghai/Guangzhou/Shenzhen changed by +40%/-7%/-4%/-18% yoy, with Shanghai turning negative from +3% in 1-18 Oct 26. On a ytd basis (as of 25 Oct 26), 19 major cities fell 5% yoy, with Tier 1/2 cities at +4%/-9% yoy.
Highlights
- Supply continued to contract. MOF data showed land sales revenue fell 27.9% yoy in 9M26, with the decline gradually narrowing. Tier 1 inventory months decreased further in Oct 26, led by Beijing, where they dropped by 1.0 month and saleable GFA dropped 3.4% mtd.
- On the demand side, sales diverged among cities and markets. High frequency data for 1-25 Oct 26 showed Tier 1 still leading, though new-home growth slowed: new-home sales rose 2% yoy in four Tier 1 cities and fell 23% in nine Tier 2 cities, while second-hand sales grew 22% yoy in three Tier 1 cities and declined 1% in eight Tier 2 cities. ICE listing prices edged down 0.6% mom.
- Maintain UNDERWEIGHT. Our top picks are COLI and CR Mixc.
Analysis
- Supply continued to contract, with land sales revenue falling 27.9% yoy in 9M26... According to the MOF, land sales revenue was Rmb1,608.7b in 9M26, and the cumulative decline narrowed from 30.8% in 7M26 and 28.6% in 8M26. Derived from the cumulative figures, Sep 26 land sales revenue was about Rmb233.4b, down 23.2% yoy, a smaller drop than the 9M26 average.
- …while saleable GFA in Tier 1 inventory months declined further in Oct 26, led by Beijing. As of 25 Oct 26, saleable GFA in Beijing/Shanghai/ Guangzhou/Shenzhen changed by -20.0%/-5.5%/-11.3%/-37.4% yoy respectively, and inventory months dropped 3.2/1.2/1.7/7.7 months ytd to 17.1/7.7/16.1/15.9 months. Since end-Sep 26, Beijing’s saleable GFA has decreased 3.4% and its inventory months have gone down by 1.0 month, while the other three cities have each seen declines of less than 0.2 months.
- On the demand side, sales diverged among cities and markets. Property sales continued to show the following trends in October: a) Tier 1 cities outperformed Tier 2 cities, and b) the secondary market outperformed the new-home market. In our view, this reflects continued divergence across market segments amid relatively weak overall demand. a) During 1-25 Oct 26, new-home sales rose 2% yoy in four Tier 1 cities and declined 23% yoy in nine Tier 2 cities. Among Tier 1 cities, Beijing/Shanghai/Guangzhou/Shenzhen changed by +40%/-7%/-4%/-18% yoy, with Shanghai turning negative from +3% in 1-18 Oct 26. On a ytd basis (as of 25 Oct 26), 19 major cities fell 5% yoy, with Tier 1/2 cities at +4%/-9% yoy.
UNDERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


