
Periodic/Sector reports
Banking: 3Q26 Results Round-up: NII Turns Around Into Upward Trend
OVERWEIGHT (Upgraded)
Analyst
Highlights
Banks’ 3Q26 results showed resilient lending and wealth management growth, although weaker trading and investment income weighed on earnings. Asset quality improved across all three banks, with NPL ratios declining by 0.1ppt qoq to 0.9% for DBS, 0.8% for OCBC and 1.5% for UOB.
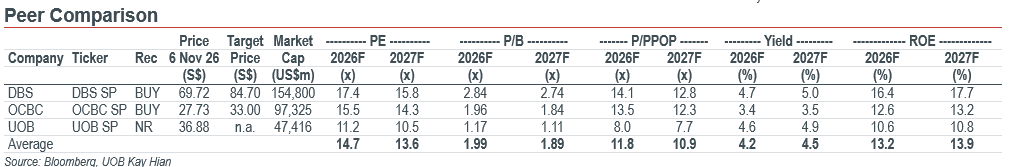
We upgrade the Banking sector to OVERWEIGHT due to rising SORA, healthy lending demand and wealth inflows, which will support earnings growth. Our preferred pick is DBS (BUY/Target: S$84.70) due to its wealth management leadership and strong deposit franchise. We lowered our target price for OCBC (BUY/Target: S$33.00) as its regional growth strategy is tempered by near-term uncertainties in Indonesia.
Analysis
Oversea-Chinese Banking Corp’s (OCBC) 3Q26 results met our expectation, but DBS Group Holdings’ (DBS) was slightly below our expectation. Loan growth and wealth management supported underlying business momentum, while weaker trading and investment income weighed on earnings.
Loan growth cushioned margin pressure. DBS demonstrated resilience in funding and asset pricing. Its net interest income (NII) increased 4% yoy and qoq to S$3,711m in 3Q26, supported by hedging and loan growth of 11% yoy, while net interest margin (NIM) remained stable qoq at 1.87%. OCBC’s loans expanded 14% yoy, lifting NII 4% yoy to S$2,313m despite a 4bp qoq NIM contraction to 1.66%. UOB experienced more severe NIM compression of 6bp qoq to 1.68% due to higher deposit costs, leaving NII up just 1% yoy. DBS’s stable NIM helped sustain its sector-leading ROE of 17.5%.
Wealth management remained a key growth driver, although investment activities moderated sequentially at DBS and OCBC. DBS’ wealth AUM reached S$544b (+16% yoy), supported by record quarterly net new money of S$15b, while OCBC’s AUM increased 7% yoy to a record S$358b. Their total fee income grew 6% and 8% yoy respectively, but softened qoq. UOB achieved record fee income of S$733m, up 19% yoy and 10% qoq, supported by wealth management and lending activities.
Weakness in market-sensitive sources of income. DBS’ markets trading income fell 68% qoq, and UOB’s other non-interest income dropped 41% qoq as prior-quarter divestment gains were not repeated and trading income weakened. OCBC’s net trading income dropped 33% qoq, while its insurance income declined 48% qoq amid market-driven valuation losses.
Asset quality improved across all three banks. NPL ratios declined by 0.1ppt to 0.9% for DBS, 0.8% for OCBC and 1.5% for UOB. NPL formation was benign and muted at S$82m for DBS and S$127m for OCBC. OCBC recorded particularly low credit costs of 6bp, alongside recoveries from Chinese real estate exposures. NPL coverage stood at 134% for DBS and 168% for OCBC. UOB has thinner NPL coverage at 86% and exposure to slow recovery in Greater China real estate. Capital remained sound, with fully phased-in or fully loaded CET1 ratios of around 14% across the banks.
Highlights
Banks’ 3Q26 results showed resilient lending and wealth management growth, although weaker trading and investment income weighed on earnings. Asset quality improved across all three banks, with NPL ratios declining by 0.1ppt qoq to 0.9% for DBS, 0.8% for OCBC and 1.5% for UOB.
We upgrade the Banking sector to OVERWEIGHT due to rising SORA, healthy lending demand and wealth inflows, which will support earnings growth. Our preferred pick is DBS (BUY/Target: S$84.70) due to its wealth management leadership and strong deposit franchise. We lowered our target price for OCBC (BUY/Target: S$33.00) as its regional growth strategy is tempered by near-term uncertainties in Indonesia.
Analysis
Oversea-Chinese Banking Corp’s (OCBC) 3Q26 results met our expectation, but DBS Group Holdings’ (DBS) was slightly below our expectation. Loan growth and wealth management supported underlying business momentum, while weaker trading and investment income weighed on earnings.
Loan growth cushioned margin pressure. DBS demonstrated resilience in funding and asset pricing. Its net interest income (NII) increased 4% yoy and qoq to S$3,711m in 3Q26, supported by hedging and loan growth of 11% yoy, while net interest margin (NIM) remained stable qoq at 1.87%. OCBC’s loans expanded 14% yoy, lifting NII 4% yoy to S$2,313m despite a 4bp qoq NIM contraction to 1.66%. UOB experienced more severe NIM compression of 6bp qoq to 1.68% due to higher deposit costs, leaving NII up just 1% yoy. DBS’s stable NIM helped sustain its sector-leading ROE of 17.5%.
Wealth management remained a key growth driver, although investment activities moderated sequentially at DBS and OCBC. DBS’ wealth AUM reached S$544b (+16% yoy), supported by record quarterly net new money of S$15b, while OCBC’s AUM increased 7% yoy to a record S$358b. Their total fee income grew 6% and 8% yoy respectively, but softened qoq. UOB achieved record fee income of S$733m, up 19% yoy and 10% qoq, supported by wealth management and lending activities.
Weakness in market-sensitive sources of income. DBS’ markets trading income fell 68% qoq, and UOB’s other non-interest income dropped 41% qoq as prior-quarter divestment gains were not repeated and trading income weakened. OCBC’s net trading income dropped 33% qoq, while its insurance income declined 48% qoq amid market-driven valuation losses.
Asset quality improved across all three banks. NPL ratios declined by 0.1ppt to 0.9% for DBS, 0.8% for OCBC and 1.5% for UOB. NPL formation was benign and muted at S$82m for DBS and S$127m for OCBC. OCBC recorded particularly low credit costs of 6bp, alongside recoveries from Chinese real estate exposures. NPL coverage stood at 134% for DBS and 168% for OCBC. UOB has thinner NPL coverage at 86% and exposure to slow recovery in Greater China real estate. Capital remained sound, with fully phased-in or fully loaded CET1 ratios of around 14% across the banks.
OVERWEIGHT (Upgraded)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

15 Oct 2026
Banking: 3Q26 Results Preview: NIM Bottoming, While Net Interest Income Turns Around

12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships

20 Oct 2026


