

Periodic/Sector reports
Retail: Private Brands To Drive Home Improvement Retail Earnings In 3Q26
MARKET WEIGHT (Maintained)
Analyst
Highlights
- We expect the home improvement retail segment’s 3Q26 earnings to rise 7% yoy, driven by an increase in its store count and strong gross margin expansion on the back of higher contribution from private brands.
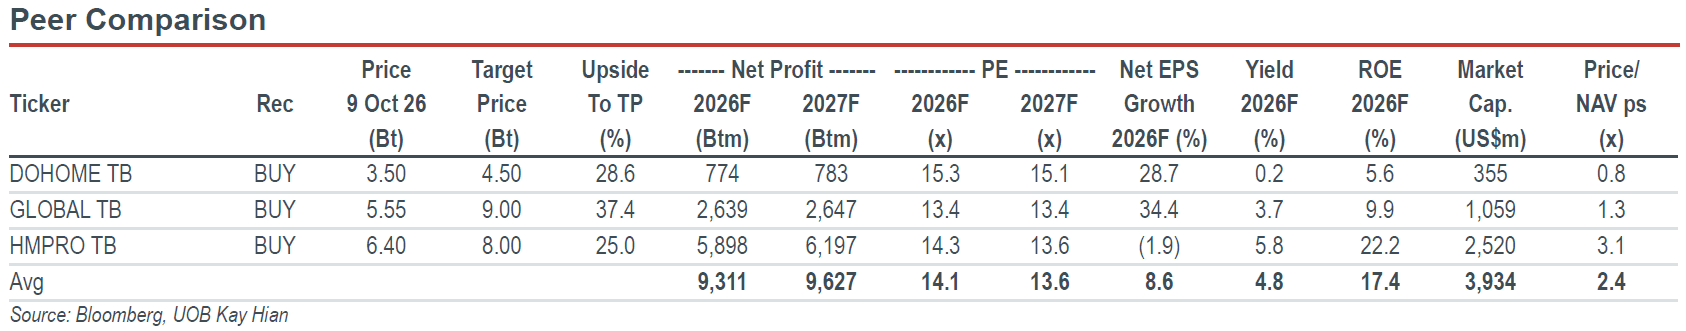
- GLOBAL is expected to outperform its peers due to better SG&A control, lower interest expenses and higher equity income.
- Maintain OVERWEIGHT on the home improvement retail segment and MARKET WEIGHT on the retail sector, with GLOBAL as our top pick in the home improvement retail segment.
Analysis
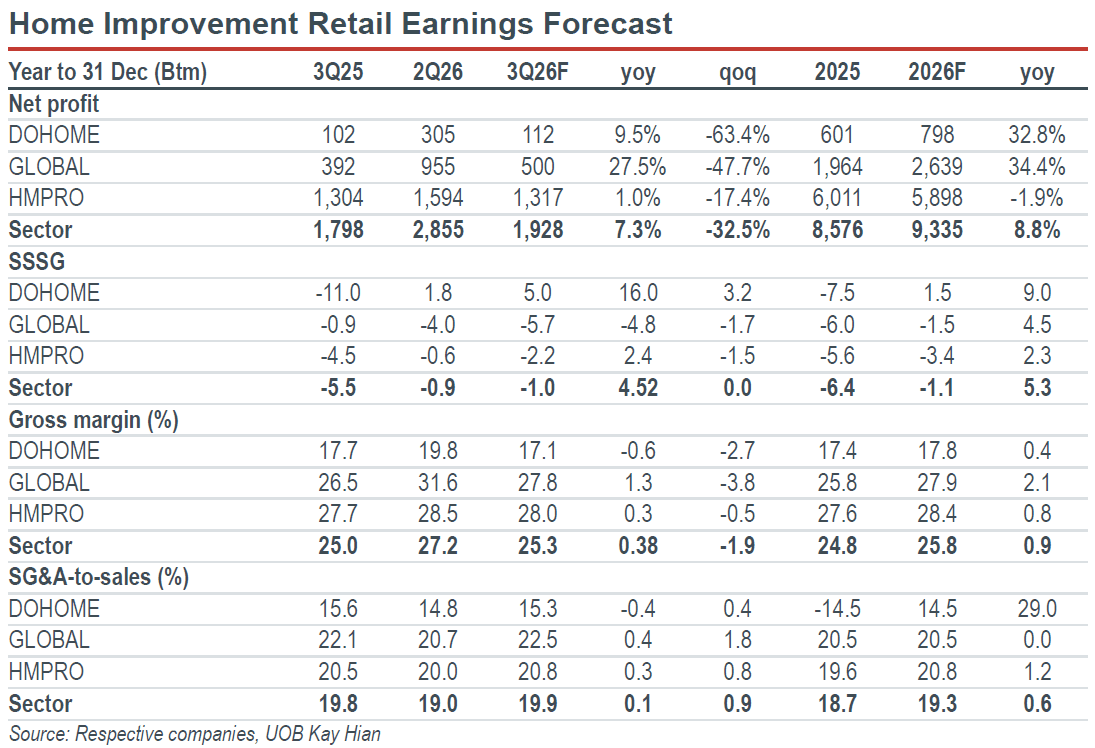
- 3Q26 earnings forecasts. We expect the home improvement retail segment to report 3Q26 earnings of Bt1.9b (+7% yoy, -33% qoq), driven by: a) 2.4% sales growth from an increase in its store count, despite a 1% yoy decline in SSSG; b) 40bp gross margin expansion to 24.8%; and c) a 10bp increase in SG&A-to-sales to 19.9%. Earnings growth is expected to moderate from 2Q26 as the benefits from low-cost inventory will start to fade from 3Q26 onwards. However, gross margin expansion will remain the key earnings driver in 3Q26, with all stocks under our coverage increasing their private-label sales mix.
Highlights
- We expect the home improvement retail segment’s 3Q26 earnings to rise 7% yoy, driven by an increase in its store count and strong gross margin expansion on the back of higher contribution from private brands.
- GLOBAL is expected to outperform its peers due to better SG&A control, lower interest expenses and higher equity income.
- Maintain OVERWEIGHT on the home improvement retail segment and MARKET WEIGHT on the retail sector, with GLOBAL as our top pick in the home improvement retail segment.
Analysis
- 3Q26 earnings forecasts. We expect the home improvement retail segment to report 3Q26 earnings of Bt1.9b (+7% yoy, -33% qoq), driven by: a) 2.4% sales growth from an increase in its store count, despite a 1% yoy decline in SSSG; b) 40bp gross margin expansion to 24.8%; and c) a 10bp increase in SG&A-to-sales to 19.9%. Earnings growth is expected to moderate from 2Q26 as the benefits from low-cost inventory will start to fade from 3Q26 onwards. However, gross margin expansion will remain the key earnings driver in 3Q26, with all stocks under our coverage increasing their private-label sales mix.
MARKET WEIGHT (Maintained)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


