
Key Indices
Top Stories
Company Results | Food Empire Holdings (FEH SP/BUY/S$1.79/Target: S$3.00)
- FEH’s 9M26 revenue reached a record US$477m (+12% yoy), ahead of expectations. We expect 2H26 net margin and earnings to be better hoh as FEH is deliberately prioritising profitability over chasing sales. Maintain BUY with a target price of S$3.00. FEH trades at an attractive 11.4x 2027F PE, a 46% discount to peers’ 21x. Its 6.7% yield is also attractive.
Company Results | Genting Singapore (GENS SP/HOLD/S$0.61/Target: S$0.65)
- GENS’ weaker 3Q26 results mainly reflects lower VIP volume and win rates. Meanwhile, the gradual launch of non-gaming attractions, such as the Singapore Oceanarium, The Weave and The Laurus hotel, continues to support the non-gaming segment’s earnings momentum. While the ongoing modernisation programme may temporarily reduce available hotel rooms and lift operating expenses, we remain neutral on GENS’s near-term outlook. Nevertheless, its prospective dividend yield of 6.6% is attractive. Maintain HOLD with a lower target price of S$0.65.
Company Results | SATS (SATS SP/BUY/S$4.17/Target: S$5.00)
- SATS delivered steady headline earnings in 1HFY27, supported by one-off tax items. After excluding all one-offs, core earnings declined 9.9% yoy in 2QFY27. This is not a concern to us, as the 2QFY27 margin weakness reflected transitory cost pressures that have been well flagged by management. Management’s tone is incrementally more positive, with cost pressures likely past their peak and margins poised to recover. Maintain BUY with an unchanged S$5.00 target price, underpinned by strong fundamentals and favourable medium-term prospects.
Company Results | Singapore Airlines (SIA SP/SELL/S$7.25/Target: S$6.65)
- SIA’s 2QFY27 net profit of S$210m missed our guided range of S$230m-370m, due to weaker-than-expected passenger yields; excluding one-off accounting gains from Air India, the miss would have been larger. Although jet fuel prices have eased from recent peaks, elevated costs are likely to continue weighing on 3Q and 2HFY27 earnings, which we forecast to decline 33% and 29% yoy respectively. At 1.40x FY27F P/B (1.6SD above mean), we deem valuation as demanding. Maintain SELL; target price: S$6.65.
Market Spotlight
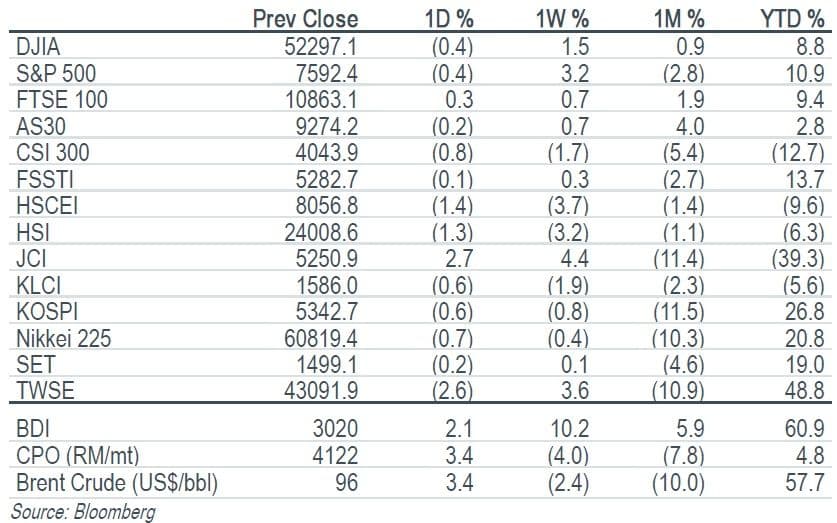
- US stocks were lower on Thursday. All indices fell as materials, industrials and financials sectors slid. There were more decliners than advancers on both NYSE and NASDAQ.
- The FSSTI fell 6.96 points to 5,282.70, on the back of weakness in UMS and OCBC Bank. Both mid- and small-cap indices fell with a broad market decline on S$1.71b turnover.
What’s Inside
Company Results | AEM Holdings (AEM SP/BUY/S$6.80/Target: S$9.08)
- 3Q26 adjusted net profit reached S$42.6m (+1530% yoy/111% qoq), ahead of our estimate. 3Q26 adjusted earnings surged 111% qoq to S$34.8m, driven by AMPS shipments. 2026 EPS guidance rose by around 20% to 30-33 S cents, while revenue guidance was raised by around 4%. AEM remains confident in its growth trajectory. Maintain BUY with a 30% lower target price of S$9.08.
Company Results | ComfortDelGro Corp (CD SP/HOLD/S$1.29/Target: S$1.41)
- ComfortDelGro’s 9M26 revenue rose 4.9% yoy, while PATMI fell 20.0%, representing 77.7% and 78.6% of full-year forecasts respectively, in line with expectations. Public transport earnings remained resilient, supported by overseas contracts, while taxi/PHV profitability weakened amid competition. Inspection and testing benefitted from ERP 2.0 installations, although contributions may taper off. Maintain HOLD with S$1.41 target price, pegged to 17x 2026F PE.
Company Results | NTT DC REIT (NTTDCR SP/BUY/US$0.93/Target: US$1.29)
- Occupancy by IT load rose to 97.5%, supported by expansion demand from existing tenants at key assets CA1, CA2 and CA3. NTTDCR also achieved positive rental reversions of 11.7% in 1HFY27. Maintain BUY and target price at US$1.29 due to favourable supply-demand dynamics, ongoing tenant expansion, and potential acquisitions from its sponsor pipeline. NTTDCR provides an attractive FY27 DPU yield of 9.2%.
Company Update | Centurion Corp. (CENT SP/BUY/S$1.21/Target: S$2.05)
- CENT reported a 34.5% yoy rise in 9M26 revenue to S$280.1m, buoyed by higher bed capacity in Singapore, positive rental reversions in Singapore and Australia as well as contributions from new acquisitions in Malaysia and Australia. Looking ahead, portfolio capacity is expected to expand by 27% to around 108,263 beds by 2028, largely coming from Singapore, Malaysia and Australia. This will likely underpin the group’s strong and visible earnings and value creation pipeline. Maintain BUY with a target price of S$2.05.
Technical Analysis
Parkway Life Real Estate Investment Trust (PREIT SP)
Trading Buy Range: S$4.02-4.03
UMS Holdings (UMSH SP)
Trading Sell Range: S$1.82-1.83
Top Stories
Company Results | Food Empire Holdings (FEH SP/BUY/S$1.79/Target: S$3.00)
- FEH’s 9M26 revenue reached a record US$477m (+12% yoy), ahead of expectations. We expect 2H26 net margin and earnings to be better hoh as FEH is deliberately prioritising profitability over chasing sales. Maintain BUY with a target price of S$3.00. FEH trades at an attractive 11.4x 2027F PE, a 46% discount to peers’ 21x. Its 6.7% yield is also attractive.
Company Results | Genting Singapore (GENS SP/HOLD/S$0.61/Target: S$0.65)
- GENS’ weaker 3Q26 results mainly reflects lower VIP volume and win rates. Meanwhile, the gradual launch of non-gaming attractions, such as the Singapore Oceanarium, The Weave and The Laurus hotel, continues to support the non-gaming segment’s earnings momentum. While the ongoing modernisation programme may temporarily reduce available hotel rooms and lift operating expenses, we remain neutral on GENS’s near-term outlook. Nevertheless, its prospective dividend yield of 6.6% is attractive. Maintain HOLD with a lower target price of S$0.65.
Company Results | SATS (SATS SP/BUY/S$4.17/Target: S$5.00)
- SATS delivered steady headline earnings in 1HFY27, supported by one-off tax items. After excluding all one-offs, core earnings declined 9.9% yoy in 2QFY27. This is not a concern to us, as the 2QFY27 margin weakness reflected transitory cost pressures that have been well flagged by management. Management’s tone is incrementally more positive, with cost pressures likely past their peak and margins poised to recover. Maintain BUY with an unchanged S$5.00 target price, underpinned by strong fundamentals and favourable medium-term prospects.
Company Results | Singapore Airlines (SIA SP/SELL/S$7.25/Target: S$6.65)
- SIA’s 2QFY27 net profit of S$210m missed our guided range of S$230m-370m, due to weaker-than-expected passenger yields; excluding one-off accounting gains from Air India, the miss would have been larger. Although jet fuel prices have eased from recent peaks, elevated costs are likely to continue weighing on 3Q and 2HFY27 earnings, which we forecast to decline 33% and 29% yoy respectively. At 1.40x FY27F P/B (1.6SD above mean), we deem valuation as demanding. Maintain SELL; target price: S$6.65.
Market Spotlight
- US stocks were lower on Thursday. All indices fell as materials, industrials and financials sectors slid. There were more decliners than advancers on both NYSE and NASDAQ.
- The FSSTI fell 6.96 points to 5,282.70, on the back of weakness in UMS and OCBC Bank. Both mid- and small-cap indices fell with a broad market decline on S$1.71b turnover.
What’s Inside
Company Results | AEM Holdings (AEM SP/BUY/S$6.80/Target: S$9.08)
- 3Q26 adjusted net profit reached S$42.6m (+1530% yoy/111% qoq), ahead of our estimate. 3Q26 adjusted earnings surged 111% qoq to S$34.8m, driven by AMPS shipments. 2026 EPS guidance rose by around 20% to 30-33 S cents, while revenue guidance was raised by around 4%. AEM remains confident in its growth trajectory. Maintain BUY with a 30% lower target price of S$9.08.
Company Results | ComfortDelGro Corp (CD SP/HOLD/S$1.29/Target: S$1.41)
- ComfortDelGro’s 9M26 revenue rose 4.9% yoy, while PATMI fell 20.0%, representing 77.7% and 78.6% of full-year forecasts respectively, in line with expectations. Public transport earnings remained resilient, supported by overseas contracts, while taxi/PHV profitability weakened amid competition. Inspection and testing benefitted from ERP 2.0 installations, although contributions may taper off. Maintain HOLD with S$1.41 target price, pegged to 17x 2026F PE.
Company Results | NTT DC REIT (NTTDCR SP/BUY/US$0.93/Target: US$1.29)
- Occupancy by IT load rose to 97.5%, supported by expansion demand from existing tenants at key assets CA1, CA2 and CA3. NTTDCR also achieved positive rental reversions of 11.7% in 1HFY27. Maintain BUY and target price at US$1.29 due to favourable supply-demand dynamics, ongoing tenant expansion, and potential acquisitions from its sponsor pipeline. NTTDCR provides an attractive FY27 DPU yield of 9.2%.
Company Update | Centurion Corp. (CENT SP/BUY/S$1.21/Target: S$2.05)
- CENT reported a 34.5% yoy rise in 9M26 revenue to S$280.1m, buoyed by higher bed capacity in Singapore, positive rental reversions in Singapore and Australia as well as contributions from new acquisitions in Malaysia and Australia. Looking ahead, portfolio capacity is expected to expand by 27% to around 108,263 beds by 2028, largely coming from Singapore, Malaysia and Australia. This will likely underpin the group’s strong and visible earnings and value creation pipeline. Maintain BUY with a target price of S$2.05.
Technical Analysis
Parkway Life Real Estate Investment Trust (PREIT SP)
Trading Buy Range: S$4.02-4.03
UMS Holdings (UMSH SP)
Trading Sell Range: S$1.82-1.83
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


