
Overnight Markets
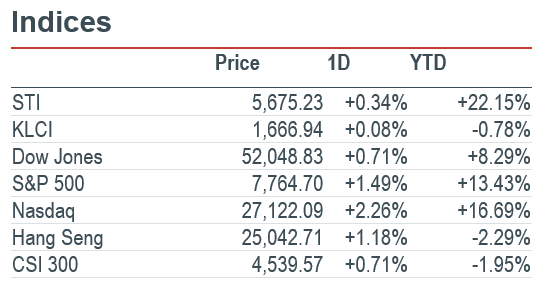
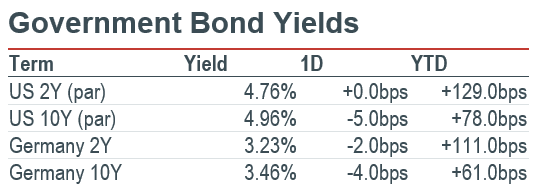
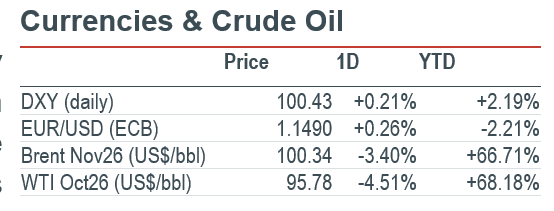
Market Movers: US equities advanced in Monday’s completed session: the S&P 500 rose 1.49% and the Nasdaq 2.26%. Meta (META US) gained about 11.3% as a new Wells Fargo target increase reinforced optimism about its existing Muse AI agent. Advanced Micro Devices (AMD US) climbed about 9.9%, reaching US$1tn in market value as AI demand broadened to server CPUs. Warner Bros Discovery (WBD US) rose about 10.8%; state and union settlements reduced obstacles to its US$110bn Paramount merger, with court approval still required. Semiconductors (SOXX US) gained about 4.9%. Hong Kong’s Hang Seng, China’s CSI 300 and Korea’s KOSPI rose about 1.2%, 0.7% and 1.6%, respectively; Japan was closed for a holiday. (Reuters / Stock Unlock / Stock Analysis / Reuters / Reuters) Meta (META US) is our Core Recommendation; iShares Semiconductor ETF (SOXX US) is our Trading Buy.
Macro: Chicago Fed President Austan Goolsbee warned on Monday that strong demand may be reinforcing persistent supply-driven inflation. Elevated services prices and AI data-centre construction are areas of concern. If demand is overheating, he said rate increases may need to be faster and more front-loaded. Restoring inflation to 2% could weigh on output and employment. (Chicago Fed / Reuters)
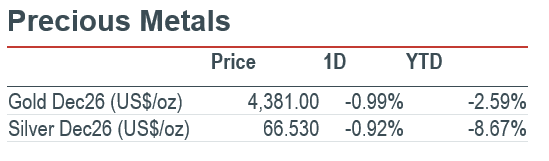
FICC: Brent November futures settled at US$100.34/bbl on Monday, down 3.40%; WTI October settled down 4.51% at US$95.78/bbl. Hopes for US–Iran diplomacy at this week’s UN gathering and a partial recovery in Saudi exports weighed on prices. Aramco loaded about 14mn barrels on Sunday, although continuing fighting and disrupted routes leave the supply outlook vulnerable. (Reuters)
AI
Meta's Muse optimism extends into a double-digit rerating. Meta Platforms (META US) rose about 11.3% from its previous close in the US session on 21 September. Wells Fargo lifted its target from US$640 to US$796, reinforcing expectations for Muse, the personal AI agent launched on 8 September. Its ability to complete tasks such as travel planning expands monetisation opportunities; sustained usage and revenue conversion now matter for the valuation. (Stock Unlock / Meta / Stock Analysis) Meta Platforms (META US) is our Core Recommendation.
AMD's US$1tn milestone broadens the AI-compute rally. Advanced Micro Devices (AMD US) gained about 9.9% from its previous close in the US session on 21 September, reaching US$1tn in market capitalisation. Arm Holdings (ARM US) advanced about 17.2%. Reuters linked demand to AI inference and server CPUs, alongside accelerators, as AMD expands into complete systems. The shift broadens the potential revenue pool beyond graphics processors. (Reuters / AMD prices / Arm prices)
SoftBank turns to bond markets to refinance OpenAI funding. SoftBank Group (9984 JP) launched a proposed US$10bn and EUR1bn senior unsecured offering on 21 September, Reuters reported. Dollar maturities span 3.5, 5.5 and 7.5 years; euro tranches run four and six years. Proceeds would replace bridge funding for the third US$10bn instalment of its previously announced OpenAI investment. Pricing will test its financing cost and investor appetite. (Reuters / SoftBank)
OpenAI proposes common standards for the next generation of frontier models. Its 21 September proposal combines coordinated national and international technical standards with common approaches to capability measurement, incident reporting and human oversight. It explicitly excludes licensing and mandatory pre-release approval from its proposed framework. Shared definitions could reduce inconsistent compliance demands across markets, but this remains an industry proposal whose economic effect depends on government and developer adoption. (OpenAI / Reuters)
Americas
Tesla gains another European regulatory foothold for FSD. The Czech Republic provisionally approved Tesla's (TSLA US) Full Self-Driving system on 21 September, reversing earlier safety objections after additional European data and monitoring safeguards. The decision follows Dutch approval in April and extends the opportunity to monetise driving software beyond vehicle sales. Conditional regulatory access and effective driver oversight remain important constraints on how quickly that opportunity becomes revenue. (Reuters)
Warner Bros merger settlements reduce closing risk but add operating commitments. Warner Bros Discovery (WBD US) rose about 10.8% from its previous close in the US session on 21 September. Paramount Skydance (PSKY US) settled state and writers' union challenges to the US$110bn transaction. The state agreement requires court approval and US$1.5bn of additional domestic production over five years. These undertakings improve closing visibility while limiting aggressive cost reductions. (Reuters / California Attorney General / WBD prices)
Qatar's US$20bn mandate expands JPMorgan's institutional investment franchise. Qatar Investment Authority and J.P. Morgan Asset Management signed a memorandum of understanding on 21 September covering US$15bn in public equities and US$5bn in private investments. The latter targets senior financing for US middle-market businesses. The partnership adds potential managed assets and fees for JPMorgan Chase (JPM US); the US$20bn headline describes investment allocations, rather than an acquisition price. (JPMorgan / Dow Jones)
AppLovin's e-commerce client growth supports a sharp rebound. AppLovin (APP US) gained about 7.2% from its previous close in the US session on 21 September. Citi's latest checks counted 13,105 global e-commerce clients through 18 September, up 5.1% over the week and the fastest growth in five months, TheFly reported. Broader advertiser adoption supports expansion beyond gaming, although client counts alone do not establish advertising spend or revenue. (TheFly / Stock Analysis) AppLovin (APP US) is our Trading Buy.
Grail rallies as FDA briefing narrows the outstanding questions on Galleri. Grail (GRAL US) rose about 33.7% from its previous close in the US session on 21 September. FDA reviewers had no outstanding analytical-performance or specified primary-safety questions, but still sought advice on benefits, risks and the early-detection claim. The panel begins at 21:00 SGT on 23 September. Reduced technical uncertainty improves visibility; approval and labelling remain unresolved. (Reuters / FDA briefing / FDA calendar / Grail prices)
Strategy balances fresh Bitcoin purchases with preferred-share repurchases. Strategy (MSTR US) disclosed on 21 September that it bought 950 Bitcoin for US$75.7m during 14–20 September, taking holdings to 846,000 coins. It also spent US$174m repurchasing STRC preferred shares. Both uses were cash-funded, with no at-the-market share sales during the period. Capital allocation is balancing additional Bitcoin exposure against reducing preferred claims on future resources. (Strategy / SEC)
Boeing's China order conversion advances without a new purchase commitment. US Trade Representative Jamieson Greer said on 21 September that roughly 140 of the 200 Boeing (BA US) aircraft purchases announced in May were progressing well, with orders being written for another 10. He gave no indication of an additional commitment, Reuters reported. Converting the existing agreement into firm business supports the backlog; contractual execution and deliveries determine the cash-flow benefit. (Reuters)
Priority's management-led buyout crystallises value but retains approval risk. Priority Technology (PRTH US) announced on 21 September that a group led by chairman and CEO Thomas Priore would acquire shares it does not own for US$8.05 each in cash. The proposed transaction values the business at approximately US$1.6bn including debt. Completion is expected in the first half of 2027, subject to regulatory clearance and unaffiliated shareholder approval. (Priority / SEC / Latham & Watkins)
Canada faces renewed tension between weaker growth and persistent inflation. Governor Tiff Macklem warned on 21 September that new US tariffs, if maintained, could roughly halve fourth-quarter growth to below 1%. Inflation has remained around 3%, with energy disruption creating further upside risk. He cautioned against both unnecessary tightening and a delayed response to persistent inflation. Canadian rates therefore remain sensitive to trade negotiations and broader transmission of fuel costs. (Bank of Canada / Reuters)
Greater China
CATL deploys buyback capacity. CATL (300750.SZ) repurchased 3.69mn A shares for about RMB1.1bn on Monday, according to its Hong Kong filing reported by National Business Daily. Purchases at RMB296.26–301.00 implement the existing capital-return programme; the shares are intended for cancellation. The transaction offers a concrete capital-allocation signal, although the value created still depends on the acquisition price and future operating returns. (National Business Daily / China Fund News) CATL (300750.SZ) is our Core Recommendation.
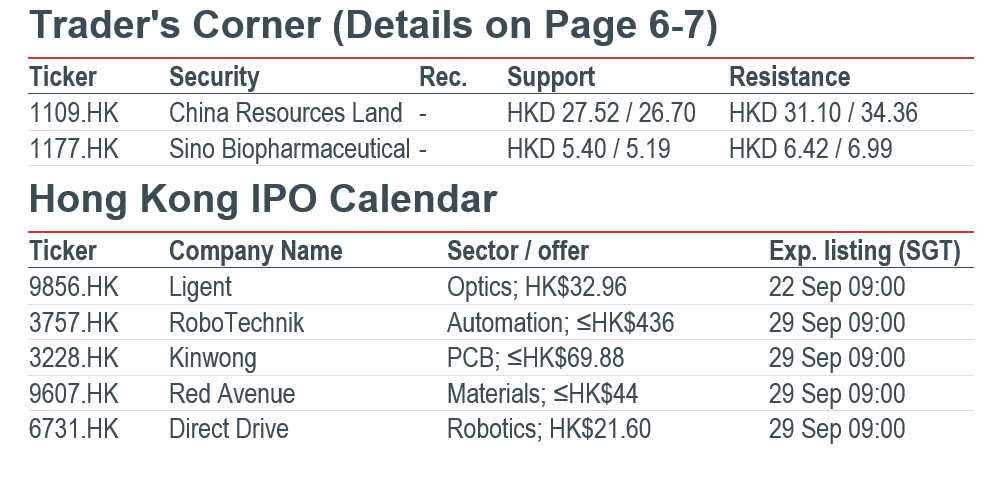
Industrial issuers reopen Hong Kong subscriptions. Public subscriptions for RoboTechnik, Kinwong Electronic, Red Avenue and Direct Drive opened at 9am SGT on Monday. Reuters reported combined base fundraising of about HK$14.35bn, with RoboTechnik alone seeking up to HK$5.18bn before options. The launches broaden equity supply across automation, circuit boards, materials and motors. Their reception will test whether strong listing activity translates into investor demand at the proposed valuations. (HKEX / Reuters)
Seazen tests refinancing appetite. Seazen Holdings (601155.SH) began Monday bookbuilding for up to RMB400mn of two-year bonds to refinance funds used for an earlier redemption. Its current exchange filing gives indicative coupons of 6.00–7.00% on the RMB300mn secured tranche and 6.00–7.80% on the RMB100mn unsecured tranche. The structure demonstrates access to domestic funding, while the pricing ranges underline the continuing cost of developer refinancing. (SSE)
Petroleum engineering orders build visibility. China Petroleum Engineering (600339.SH) disclosed on Monday that new contracts reached RMB101.05bn in January–August, up 15.91% year on year, including RMB3.75bn in August. Overseas business represented 40.53% of the eight-month total. The order intake supports medium-term activity across engineering and construction, but signed contract value is not recognised revenue; execution schedules, project margins and cash collection determine how much ultimately reaches earnings. (Company filing / Reuters)
Asia ex. China
Korean chip shipments drive export surge. South Korea's Monday customs release showed exports of US$71.41bn in September's first 20 days, up 78.3% year on year. Semiconductor exports increased 259.4% to US$34.13bn, accounting for 47.8% of shipments, according to Aju News. This reinforces the importance of the chip cycle to regional earnings and trade, while the preliminary data measure export value and cannot by themselves separate higher prices from higher volumes. (Korea Customs / Aju News)
Vietnam's index upgrade starts in stages. Vietnam entered FTSE Russell's secondary emerging-market classification at Monday's market open. Implementation begins with 10% of eligible investability weight, followed by 20% in March 2027 and 35% each in June and September 2027. This expands access to global benchmarks through a measured transition, with most index inclusion still ahead. Fund demand will depend on portfolio tracking and execution, so the upgrade does not imply a full immediate allocation. (FTSE Russell / The Investor)
Suntec's refocus meets a cautious market. Suntec REIT (T82U SP) fell about 2.2% from Friday at Monday's Singapore close after an early-morning portfolio review. The manager plans sale campaigns for three Australian properties while sharpening its Singapore focus. Successful disposals are expected to reduce aggregate leverage below 40%, creating room for acquisitions or capital returns. These are proposed sales without assured completion; valuation and execution will determine the balance-sheet benefit. (Suntec REIT / SGX/ShareInvestor)
EMEA and Others
Novo sets a demanding growth agenda. Novo Nordisk (NOVOB DC) fell about 7.7% from Friday at Monday's Copenhagen close as its capital markets day set ambitious growth goals. Management targets more than five multiblockbuster launches by 2030 and over DKK150bn of risk-adjusted pipeline sales in 2035, alongside peer-level adjusted revenue growth through 2030. These are strategic ambitions rather than financial guidance; clinical delivery and commercial execution remain essential amid intensifying obesity-treatment competition. (Novo Nordisk / Reuters)
Kuehne+Nagel deepens Amazon logistics role. Kuehne+Nagel (KNIN SW) announced a long-term Amazon partnership on Monday covering logistics for AWS infrastructure, from construction equipment to upgrades and maintenance. Amazon receives an option over existing Kuehne+Nagel shares, vesting against commercial milestones and services over up to seven years, with cash or share settlement. The arrangement links logistics demand to data-centre expansion, but undisclosed contract value and option size limit earnings and ownership analysis. (Kuehne+Nagel / FreightWaves)
Societe Generale raises the return bar. Societe Generale (GLE FP) unveiled Monday targets for a 13–14% return on tangible equity in 2029 and more than 15% from 2030. Its plan assumes roughly 3% annual revenue growth from 2026 estimates to 2029, operating costs below EUR16.3bn and a cost-to-income ratio under 55%. The investment case therefore relies on cost discipline and capital efficiency as much as expansion, with execution determining whether higher returns prove durable. (Societe Generale)
Ipsen prices in a new generic competitor. Ipsen (IPN FP) fell about 5.1% from Friday at Monday's Paris close after Amneal's Friday post-European-close announcement of US approval and launch of generic lanreotide. The approved 120mg/0.5mL injection references Somatuline Depot. Amneal cited US$983mn of US market sales for the twelve months to July, using IQVIA data. The launch raises price and share-retention risk for Ipsen; that market estimate is not an Ipsen revenue figure. (Amneal / Reuters / Boursorama)
Nordnet returns surplus capital. Nordnet (SAVE SS) launched a share-buyback programme on Monday for up to SEK250mn, with execution mandated independently to Citigroup. Purchases can run through 23 December 2026, subject to the programme ceiling. Management said the purpose is to optimise the capital structure and distribute surplus capital. The programme sets a defined near-term return of capital, while its actual pace will depend on available trading liquidity and permitted purchase conditions. (Nordnet)
Traders’ corner
Our Technical View
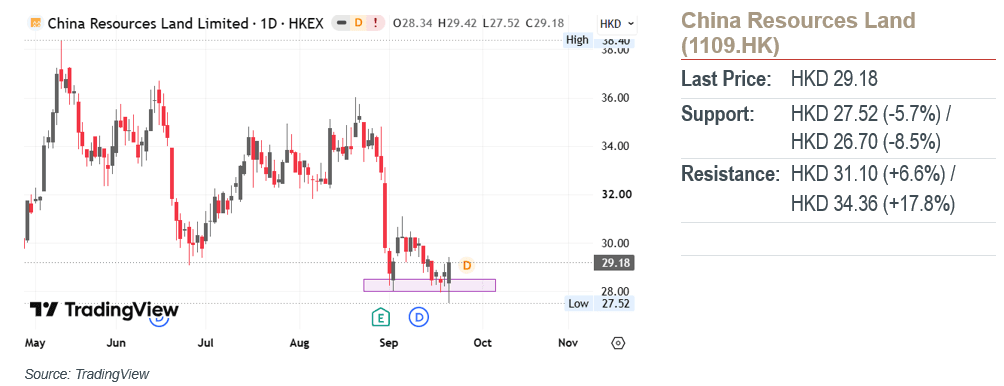
Price successfully defended its primary demand floor at the previous low support zone, setting up a potential double bottom reversal pattern.
The RSI is generating a classic bullish divergence signal.
As long as price maintains structural integrity above this support anchor, we could expect a sustained upward rebound toward overhead resistance targets.
Our Technical View
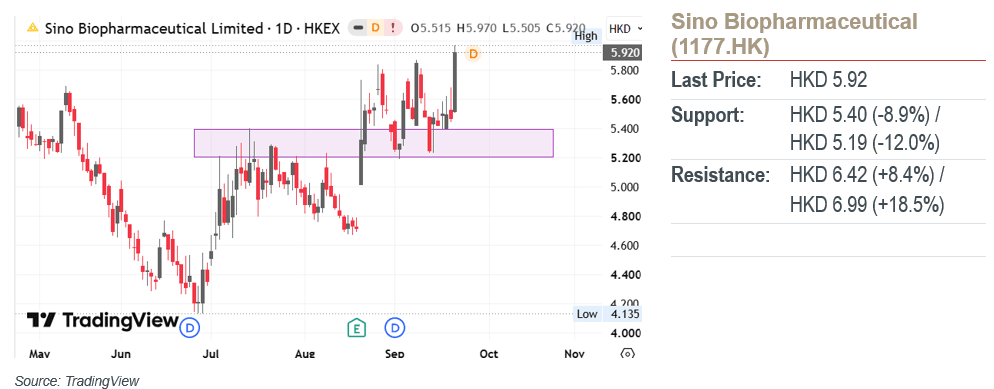
Price executed a rebound off its resistance-turned-support zone.
The RSI maintains its position comfortably above the neutral 50-midline.
As long as price maintains structural integrity above this support anchor, path-of-least-resistance dynamics heavily favours continued upward expansion toward higher extension targets.
Market Movers: US equities advanced in Monday’s completed session: the S&P 500 rose 1.49% and the Nasdaq 2.26%. Meta (META US) gained about 11.3% as a new Wells Fargo target increase reinforced optimism about its existing Muse AI agent. Advanced Micro Devices (AMD US) climbed about 9.9%, reaching US$1tn in market value as AI demand broadened to server CPUs. Warner Bros Discovery (WBD US) rose about 10.8%; state and union settlements reduced obstacles to its US$110bn Paramount merger, with court approval still required. Semiconductors (SOXX US) gained about 4.9%. Hong Kong’s Hang Seng, China’s CSI 300 and Korea’s KOSPI rose about 1.2%, 0.7% and 1.6%, respectively; Japan was closed for a holiday. (Reuters / Stock Unlock / Stock Analysis / Reuters / Reuters) Meta (META US) is our Core Recommendation; iShares Semiconductor ETF (SOXX US) is our Trading Buy.
Macro: Chicago Fed President Austan Goolsbee warned on Monday that strong demand may be reinforcing persistent supply-driven inflation. Elevated services prices and AI data-centre construction are areas of concern. If demand is overheating, he said rate increases may need to be faster and more front-loaded. Restoring inflation to 2% could weigh on output and employment. (Chicago Fed / Reuters)
FICC: Brent November futures settled at US$100.34/bbl on Monday, down 3.40%; WTI October settled down 4.51% at US$95.78/bbl. Hopes for US–Iran diplomacy at this week’s UN gathering and a partial recovery in Saudi exports weighed on prices. Aramco loaded about 14mn barrels on Sunday, although continuing fighting and disrupted routes leave the supply outlook vulnerable. (Reuters)
AI
Meta's Muse optimism extends into a double-digit rerating. Meta Platforms (META US) rose about 11.3% from its previous close in the US session on 21 September. Wells Fargo lifted its target from US$640 to US$796, reinforcing expectations for Muse, the personal AI agent launched on 8 September. Its ability to complete tasks such as travel planning expands monetisation opportunities; sustained usage and revenue conversion now matter for the valuation. (Stock Unlock / Meta / Stock Analysis) Meta Platforms (META US) is our Core Recommendation.
AMD's US$1tn milestone broadens the AI-compute rally. Advanced Micro Devices (AMD US) gained about 9.9% from its previous close in the US session on 21 September, reaching US$1tn in market capitalisation. Arm Holdings (ARM US) advanced about 17.2%. Reuters linked demand to AI inference and server CPUs, alongside accelerators, as AMD expands into complete systems. The shift broadens the potential revenue pool beyond graphics processors. (Reuters / AMD prices / Arm prices)
SoftBank turns to bond markets to refinance OpenAI funding. SoftBank Group (9984 JP) launched a proposed US$10bn and EUR1bn senior unsecured offering on 21 September, Reuters reported. Dollar maturities span 3.5, 5.5 and 7.5 years; euro tranches run four and six years. Proceeds would replace bridge funding for the third US$10bn instalment of its previously announced OpenAI investment. Pricing will test its financing cost and investor appetite. (Reuters / SoftBank)
OpenAI proposes common standards for the next generation of frontier models. Its 21 September proposal combines coordinated national and international technical standards with common approaches to capability measurement, incident reporting and human oversight. It explicitly excludes licensing and mandatory pre-release approval from its proposed framework. Shared definitions could reduce inconsistent compliance demands across markets, but this remains an industry proposal whose economic effect depends on government and developer adoption. (OpenAI / Reuters)
Americas
Tesla gains another European regulatory foothold for FSD. The Czech Republic provisionally approved Tesla's (TSLA US) Full Self-Driving system on 21 September, reversing earlier safety objections after additional European data and monitoring safeguards. The decision follows Dutch approval in April and extends the opportunity to monetise driving software beyond vehicle sales. Conditional regulatory access and effective driver oversight remain important constraints on how quickly that opportunity becomes revenue. (Reuters)
Warner Bros merger settlements reduce closing risk but add operating commitments. Warner Bros Discovery (WBD US) rose about 10.8% from its previous close in the US session on 21 September. Paramount Skydance (PSKY US) settled state and writers' union challenges to the US$110bn transaction. The state agreement requires court approval and US$1.5bn of additional domestic production over five years. These undertakings improve closing visibility while limiting aggressive cost reductions. (Reuters / California Attorney General / WBD prices)
Qatar's US$20bn mandate expands JPMorgan's institutional investment franchise. Qatar Investment Authority and J.P. Morgan Asset Management signed a memorandum of understanding on 21 September covering US$15bn in public equities and US$5bn in private investments. The latter targets senior financing for US middle-market businesses. The partnership adds potential managed assets and fees for JPMorgan Chase (JPM US); the US$20bn headline describes investment allocations, rather than an acquisition price. (JPMorgan / Dow Jones)
AppLovin's e-commerce client growth supports a sharp rebound. AppLovin (APP US) gained about 7.2% from its previous close in the US session on 21 September. Citi's latest checks counted 13,105 global e-commerce clients through 18 September, up 5.1% over the week and the fastest growth in five months, TheFly reported. Broader advertiser adoption supports expansion beyond gaming, although client counts alone do not establish advertising spend or revenue. (TheFly / Stock Analysis) AppLovin (APP US) is our Trading Buy.
Grail rallies as FDA briefing narrows the outstanding questions on Galleri. Grail (GRAL US) rose about 33.7% from its previous close in the US session on 21 September. FDA reviewers had no outstanding analytical-performance or specified primary-safety questions, but still sought advice on benefits, risks and the early-detection claim. The panel begins at 21:00 SGT on 23 September. Reduced technical uncertainty improves visibility; approval and labelling remain unresolved. (Reuters / FDA briefing / FDA calendar / Grail prices)
Strategy balances fresh Bitcoin purchases with preferred-share repurchases. Strategy (MSTR US) disclosed on 21 September that it bought 950 Bitcoin for US$75.7m during 14–20 September, taking holdings to 846,000 coins. It also spent US$174m repurchasing STRC preferred shares. Both uses were cash-funded, with no at-the-market share sales during the period. Capital allocation is balancing additional Bitcoin exposure against reducing preferred claims on future resources. (Strategy / SEC)
Boeing's China order conversion advances without a new purchase commitment. US Trade Representative Jamieson Greer said on 21 September that roughly 140 of the 200 Boeing (BA US) aircraft purchases announced in May were progressing well, with orders being written for another 10. He gave no indication of an additional commitment, Reuters reported. Converting the existing agreement into firm business supports the backlog; contractual execution and deliveries determine the cash-flow benefit. (Reuters)
Priority's management-led buyout crystallises value but retains approval risk. Priority Technology (PRTH US) announced on 21 September that a group led by chairman and CEO Thomas Priore would acquire shares it does not own for US$8.05 each in cash. The proposed transaction values the business at approximately US$1.6bn including debt. Completion is expected in the first half of 2027, subject to regulatory clearance and unaffiliated shareholder approval. (Priority / SEC / Latham & Watkins)
Canada faces renewed tension between weaker growth and persistent inflation. Governor Tiff Macklem warned on 21 September that new US tariffs, if maintained, could roughly halve fourth-quarter growth to below 1%. Inflation has remained around 3%, with energy disruption creating further upside risk. He cautioned against both unnecessary tightening and a delayed response to persistent inflation. Canadian rates therefore remain sensitive to trade negotiations and broader transmission of fuel costs. (Bank of Canada / Reuters)
Greater China
CATL deploys buyback capacity. CATL (300750.SZ) repurchased 3.69mn A shares for about RMB1.1bn on Monday, according to its Hong Kong filing reported by National Business Daily. Purchases at RMB296.26–301.00 implement the existing capital-return programme; the shares are intended for cancellation. The transaction offers a concrete capital-allocation signal, although the value created still depends on the acquisition price and future operating returns. (National Business Daily / China Fund News) CATL (300750.SZ) is our Core Recommendation.
Industrial issuers reopen Hong Kong subscriptions. Public subscriptions for RoboTechnik, Kinwong Electronic, Red Avenue and Direct Drive opened at 9am SGT on Monday. Reuters reported combined base fundraising of about HK$14.35bn, with RoboTechnik alone seeking up to HK$5.18bn before options. The launches broaden equity supply across automation, circuit boards, materials and motors. Their reception will test whether strong listing activity translates into investor demand at the proposed valuations. (HKEX / Reuters)
Seazen tests refinancing appetite. Seazen Holdings (601155.SH) began Monday bookbuilding for up to RMB400mn of two-year bonds to refinance funds used for an earlier redemption. Its current exchange filing gives indicative coupons of 6.00–7.00% on the RMB300mn secured tranche and 6.00–7.80% on the RMB100mn unsecured tranche. The structure demonstrates access to domestic funding, while the pricing ranges underline the continuing cost of developer refinancing. (SSE)
Petroleum engineering orders build visibility. China Petroleum Engineering (600339.SH) disclosed on Monday that new contracts reached RMB101.05bn in January–August, up 15.91% year on year, including RMB3.75bn in August. Overseas business represented 40.53% of the eight-month total. The order intake supports medium-term activity across engineering and construction, but signed contract value is not recognised revenue; execution schedules, project margins and cash collection determine how much ultimately reaches earnings. (Company filing / Reuters)
Asia ex. China
Korean chip shipments drive export surge. South Korea's Monday customs release showed exports of US$71.41bn in September's first 20 days, up 78.3% year on year. Semiconductor exports increased 259.4% to US$34.13bn, accounting for 47.8% of shipments, according to Aju News. This reinforces the importance of the chip cycle to regional earnings and trade, while the preliminary data measure export value and cannot by themselves separate higher prices from higher volumes. (Korea Customs / Aju News)
Vietnam's index upgrade starts in stages. Vietnam entered FTSE Russell's secondary emerging-market classification at Monday's market open. Implementation begins with 10% of eligible investability weight, followed by 20% in March 2027 and 35% each in June and September 2027. This expands access to global benchmarks through a measured transition, with most index inclusion still ahead. Fund demand will depend on portfolio tracking and execution, so the upgrade does not imply a full immediate allocation. (FTSE Russell / The Investor)
Suntec's refocus meets a cautious market. Suntec REIT (T82U SP) fell about 2.2% from Friday at Monday's Singapore close after an early-morning portfolio review. The manager plans sale campaigns for three Australian properties while sharpening its Singapore focus. Successful disposals are expected to reduce aggregate leverage below 40%, creating room for acquisitions or capital returns. These are proposed sales without assured completion; valuation and execution will determine the balance-sheet benefit. (Suntec REIT / SGX/ShareInvestor)
EMEA and Others
Novo sets a demanding growth agenda. Novo Nordisk (NOVOB DC) fell about 7.7% from Friday at Monday's Copenhagen close as its capital markets day set ambitious growth goals. Management targets more than five multiblockbuster launches by 2030 and over DKK150bn of risk-adjusted pipeline sales in 2035, alongside peer-level adjusted revenue growth through 2030. These are strategic ambitions rather than financial guidance; clinical delivery and commercial execution remain essential amid intensifying obesity-treatment competition. (Novo Nordisk / Reuters)
Kuehne+Nagel deepens Amazon logistics role. Kuehne+Nagel (KNIN SW) announced a long-term Amazon partnership on Monday covering logistics for AWS infrastructure, from construction equipment to upgrades and maintenance. Amazon receives an option over existing Kuehne+Nagel shares, vesting against commercial milestones and services over up to seven years, with cash or share settlement. The arrangement links logistics demand to data-centre expansion, but undisclosed contract value and option size limit earnings and ownership analysis. (Kuehne+Nagel / FreightWaves)
Societe Generale raises the return bar. Societe Generale (GLE FP) unveiled Monday targets for a 13–14% return on tangible equity in 2029 and more than 15% from 2030. Its plan assumes roughly 3% annual revenue growth from 2026 estimates to 2029, operating costs below EUR16.3bn and a cost-to-income ratio under 55%. The investment case therefore relies on cost discipline and capital efficiency as much as expansion, with execution determining whether higher returns prove durable. (Societe Generale)
Ipsen prices in a new generic competitor. Ipsen (IPN FP) fell about 5.1% from Friday at Monday's Paris close after Amneal's Friday post-European-close announcement of US approval and launch of generic lanreotide. The approved 120mg/0.5mL injection references Somatuline Depot. Amneal cited US$983mn of US market sales for the twelve months to July, using IQVIA data. The launch raises price and share-retention risk for Ipsen; that market estimate is not an Ipsen revenue figure. (Amneal / Reuters / Boursorama)
Nordnet returns surplus capital. Nordnet (SAVE SS) launched a share-buyback programme on Monday for up to SEK250mn, with execution mandated independently to Citigroup. Purchases can run through 23 December 2026, subject to the programme ceiling. Management said the purpose is to optimise the capital structure and distribute surplus capital. The programme sets a defined near-term return of capital, while its actual pace will depend on available trading liquidity and permitted purchase conditions. (Nordnet)
Traders’ corner
Our Technical View
Price successfully defended its primary demand floor at the previous low support zone, setting up a potential double bottom reversal pattern.
The RSI is generating a classic bullish divergence signal.
As long as price maintains structural integrity above this support anchor, we could expect a sustained upward rebound toward overhead resistance targets.
Our Technical View
Price executed a rebound off its resistance-turned-support zone.
The RSI maintains its position comfortably above the neutral 50-midline.
As long as price maintains structural integrity above this support anchor, path-of-least-resistance dynamics heavily favours continued upward expansion toward higher extension targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


