
Company Coverage
Frasers Logistics & Commercial Trust (FLT SP): 2HFY26: Logistics Strength But Higher Gearing Limits Debt Headroom
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
S$0.925
S$0.98
5.9%
0.96
Analyst
Highlights
FLT reported 2HFY26 DPU of 2.95 S cents, flat yoy due to lower capital distributions from past divestment gains. NPI grew 9.6% yoy, supported by rental uplift for logistics properties, stronger AUD and EUR exchange rates, higher occupancy at ATP, and recent logistics acquisitions in Europe.
FLT's logistics portfolio remained resilient with occupancy of 99.1%, with virtually full occupancies in Australia, Europe and the UK. Management continues to backfill vacant space at ATP and saw stronger performance from Farnborough Business Park and Blythe Valley Park in the UK.
FLT continues to reposition towards logistics assets, targeting allocation of 85% over time through acquisitions in Europe and Singapore. Downgrade to HOLD due to limited upside with target price at S$0.98.
Analysis
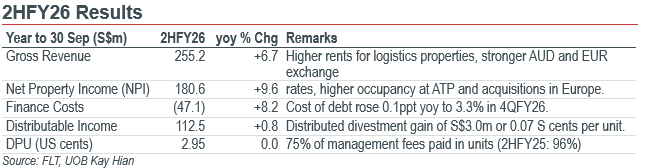
Frasers Logistics & Commercial Trust (FLT) reported a DPU of 2.95 S cents for 2HFY26 (flat yoy), which is in line with our expectation. DPU before capital distribution of divestment gains increased 7.1% yoy to 2.88 S cents, but capital distributions of past divestment gains fell 70% yoy from S$9.8m (0.26 S cents) to S$3.0m (0.07 S cents).
Growth supported by higher rents and acquisitions. Revenue and adjusted NPI increased 6.7% and 9.6% yoy respectively in 2HFY26. Growth came from higher rents for logistics properties, stronger AUD and EUR exchange rates, higher occupancy at Alexandra Technopark (ATP) and acquisitions of one logistics property in Netherlands (completion: 15 Apr 26) and four logistics properties in Germany and Netherlands (completion: 31 Jul 26), partially offset by the divestment of 357 Collins Street in Melbourne, Australia (completion: 30 Sep 25). Finance costs rose 8.2% yoy. Distributable income before capital distribution grew 7.1% yoy despite lower proportion of management fees paid in units.
Logistics occupancy remains high, with the exception of Singapore. Logistics occupancy was 99.1% as of Sep 26, with Europe and the UK fully occupied and Australia stable at 99.8%. Singapore occupancy fell 20.6ppt qoq to 74.4% due to non-renewal by a third party logistics provider. New supply is limited in Singapore. Management is confident in backfilling the vacant space with negotiation with prospective tenants already ongoing.
Highlights
FLT reported 2HFY26 DPU of 2.95 S cents, flat yoy due to lower capital distributions from past divestment gains. NPI grew 9.6% yoy, supported by rental uplift for logistics properties, stronger AUD and EUR exchange rates, higher occupancy at ATP, and recent logistics acquisitions in Europe.
FLT's logistics portfolio remained resilient with occupancy of 99.1%, with virtually full occupancies in Australia, Europe and the UK. Management continues to backfill vacant space at ATP and saw stronger performance from Farnborough Business Park and Blythe Valley Park in the UK.
FLT continues to reposition towards logistics assets, targeting allocation of 85% over time through acquisitions in Europe and Singapore. Downgrade to HOLD due to limited upside with target price at S$0.98.
Analysis
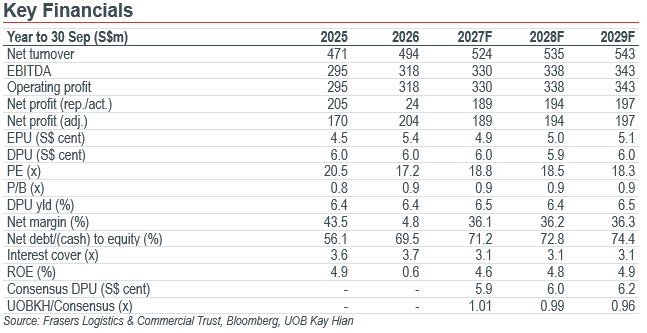
Frasers Logistics & Commercial Trust (FLT) reported a DPU of 2.95 S cents for 2HFY26 (flat yoy), which is in line with our expectation. DPU before capital distribution of divestment gains increased 7.1% yoy to 2.88 S cents, but capital distributions of past divestment gains fell 70% yoy from S$9.8m (0.26 S cents) to S$3.0m (0.07 S cents).
Growth supported by higher rents and acquisitions. Revenue and adjusted NPI increased 6.7% and 9.6% yoy respectively in 2HFY26. Growth came from higher rents for logistics properties, stronger AUD and EUR exchange rates, higher occupancy at Alexandra Technopark (ATP) and acquisitions of one logistics property in Netherlands (completion: 15 Apr 26) and four logistics properties in Germany and Netherlands (completion: 31 Jul 26), partially offset by the divestment of 357 Collins Street in Melbourne, Australia (completion: 30 Sep 25). Finance costs rose 8.2% yoy. Distributable income before capital distribution grew 7.1% yoy despite lower proportion of management fees paid in units.
Logistics occupancy remains high, with the exception of Singapore. Logistics occupancy was 99.1% as of Sep 26, with Europe and the UK fully occupied and Australia stable at 99.8%. Singapore occupancy fell 20.6ppt qoq to 74.4% due to non-renewal by a third party logistics provider. New supply is limited in Singapore. Management is confident in backfilling the vacant space with negotiation with prospective tenants already ongoing.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
S$0.925
S$0.98
5.9%
0.96
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: https://research-api.uobkayhian.com/assets/disclaimer/df64a6ea-7980-447c-ae9e-fd19b93257dc, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

3 Nov 2026
Lendlease Global Commercial REIT (LREIT SP) - 1QFY27: Retail Momentum Builds; Planning More AEIs

6 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Disciplined Reconstitution To Pivot Towards The Living Sector

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region
Our latest research

10 Nov 2026
Oversea-Chinese Banking Corp (OCBC SP): 3Q26: Banking Strength Offsets Insurance Weakness

10 Nov 2026
Venture Corporation (VMS SP): 3Q26: Broadening Growth Led By Portfolio B; Maintain BUY

6 Nov 2026