
Company Coverage
DBS Group Holdings (DBS SP) - 3Q26: Focus On Resiliency And Growth Of Core Franchise
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$71.20
S$84.70
+19.0%
S$83.60
Analyst
Highlights
- DBS reported 3Q26 net profit of S$2,813m, down 5% yoy and 9% qoq, due to weaker markets trading income. Underlying momentum remained healthy, with NII rising 4% yoy, wealth AUM reaching S$544b and record net new money of S$15b. Asset quality improved as NPL ratio fell to 0.9%.
- Management expects NII and loans to grow about 5% in 2027, alongside high single-digit to low double-digit growth in non-interest income. A resilient wealth franchise, disciplined costs and S$2.6b of unused share buyback capacity support earnings and capital return outlook.
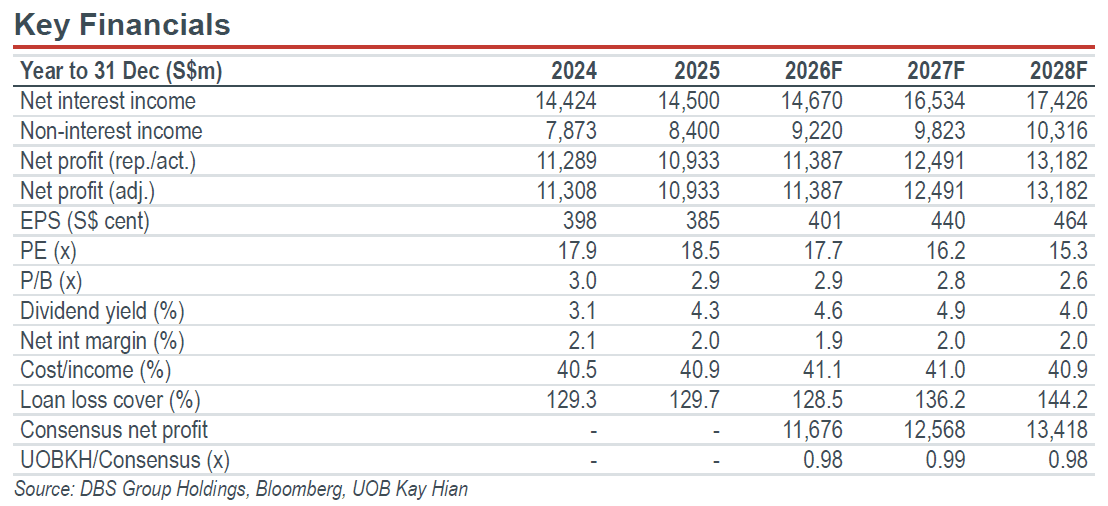
- We like DBS for its leadership in wealth management and attractive 2027 dividend yield of 4.9%. Maintain BUY. Target price: S$84.70.
Analysis
- DBS Group Holdings (DBS) reported 3Q26 net profit of S$2,813m (-5% yoy, -9% qoq), as weaker markets trading income offset franchise growth. ROE was 17.5%. The results are below our net profit forecast of S$2,941m.
- Balance sheet growth supported NII. Net interest income (NII) rose 4% yoy and qoq to S$3,711m, supported by hedging and balance sheet expansion. NIM was stable qoq at 1.87%. Customer loans reached S$479b, up 11% yoy and 3% qoq in constant-currency terms, led sequentially by non-trade corporate and wealth management lending.
- Wealth assets reached a new high despite softer quarterly fees. Net fee income increased 6% yoy but declined 2% qoq. Wealth management fees rose 9% yoy but fell 6% qoq to S$864m as investment activities moderated. Wealth AUM rose 5% qoq to S$544b, up 16% yoy. Transaction services fees reached a record of S$268m, up 8% yoy.
- Markets trading income weakened. Treasury customer income was S$919m (+10% yoy). Markets trading income fell 65% yoy and 68% qoq to S$152m amid unfavourable equity market conditions.
- Costs remained controlled. Operating expenses declined 1% yoy but increased 1% qoq to S$2,373m. The cost-to-income ratio rose 2.1ppt qoq to 40.6%. For 9M26, the ratio was broadly stable at 39.3%.
- Asset quality improved and allowance coverage strengthened. NPLs declined 3% qoq to S$4,632m and the NPL ratio improved 0.1ppt qoq to 0.9%. New NPLs fell to S$82m from S$155m in 2Q26. Specific allowances were S$191m, with loan-specific credit costs at 17bp. There was a small S$16m general allowance write-back. NPL coverage rose 4ppt qoq to 134%.
- Capital remained healthy. Fully phased-in CET-1 CAR fell 0.6ppt qoq to 14.0%. MAS has reduced DBS’ operational risk multiplier from 1.8x to 1.5x on 4 Nov 26. Adjusting for the change, CET-1 CAR was 14.1%.
Highlights
- DBS reported 3Q26 net profit of S$2,813m, down 5% yoy and 9% qoq, due to weaker markets trading income. Underlying momentum remained healthy, with NII rising 4% yoy, wealth AUM reaching S$544b and record net new money of S$15b. Asset quality improved as NPL ratio fell to 0.9%.
- Management expects NII and loans to grow about 5% in 2027, alongside high single-digit to low double-digit growth in non-interest income. A resilient wealth franchise, disciplined costs and S$2.6b of unused share buyback capacity support earnings and capital return outlook.
- We like DBS for its leadership in wealth management and attractive 2027 dividend yield of 4.9%. Maintain BUY. Target price: S$84.70.
Analysis
- DBS Group Holdings (DBS) reported 3Q26 net profit of S$2,813m (-5% yoy, -9% qoq), as weaker markets trading income offset franchise growth. ROE was 17.5%. The results are below our net profit forecast of S$2,941m.
- Balance sheet growth supported NII. Net interest income (NII) rose 4% yoy and qoq to S$3,711m, supported by hedging and balance sheet expansion. NIM was stable qoq at 1.87%. Customer loans reached S$479b, up 11% yoy and 3% qoq in constant-currency terms, led sequentially by non-trade corporate and wealth management lending.
- Wealth assets reached a new high despite softer quarterly fees. Net fee income increased 6% yoy but declined 2% qoq. Wealth management fees rose 9% yoy but fell 6% qoq to S$864m as investment activities moderated. Wealth AUM rose 5% qoq to S$544b, up 16% yoy. Transaction services fees reached a record of S$268m, up 8% yoy.
- Markets trading income weakened. Treasury customer income was S$919m (+10% yoy). Markets trading income fell 65% yoy and 68% qoq to S$152m amid unfavourable equity market conditions.
- Costs remained controlled. Operating expenses declined 1% yoy but increased 1% qoq to S$2,373m. The cost-to-income ratio rose 2.1ppt qoq to 40.6%. For 9M26, the ratio was broadly stable at 39.3%.
- Asset quality improved and allowance coverage strengthened. NPLs declined 3% qoq to S$4,632m and the NPL ratio improved 0.1ppt qoq to 0.9%. New NPLs fell to S$82m from S$155m in 2Q26. Specific allowances were S$191m, with loan-specific credit costs at 17bp. There was a small S$16m general allowance write-back. NPL coverage rose 4ppt qoq to 134%.
- Capital remained healthy. Fully phased-in CET-1 CAR fell 0.6ppt qoq to 14.0%. MAS has reduced DBS’ operational risk multiplier from 1.8x to 1.5x on 4 Nov 26. Adjusting for the change, CET-1 CAR was 14.1%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$71.20
S$84.70
+19.0%
S$83.60
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
United Overseas Bank (UOB SP) - 3Q26: Earnings Shortfall From Other Non-Interest Income

3 Nov 2026
Lendlease Global Commercial REIT (LREIT SP) - 1QFY27: Retail Momentum Builds; Planning More AEIs

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs
Our latest research

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

5 Nov 2026
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income
5 Nov 2026