Company Coverage
Mapletree Industrial Trust (MINT SP): 2QFY27: Revamp Underway
HOLD (Upgraded)
Current price:
Target price:
Upside:
S$1.74
S$1.72
-1.1%
Analyst
Highlights
- Singapore occupancy was broadly stable at 94.2% in 2QFY27. Average rental reversion strengthened to 6.9%, comprising 7.1% for general industrial buildings and 3.7% for hi-tech buildings & business space.
- North American occupancy declined 3.4ppt qoq to 79.1%, reflecting the full-quarter impact of the non-renewal at 7337 Trade Street, San Diego. After quarter-end, MINT secured new 15.5-year and 5.3-year leases for data centres at Alpharetta and San Jose commencing in Oct 26.
- Upgrade to HOLD as MINT’s unit price has dropped 9.8% since our downgrade on 10 Sep 26. Target price: S$1.72.
Analysis
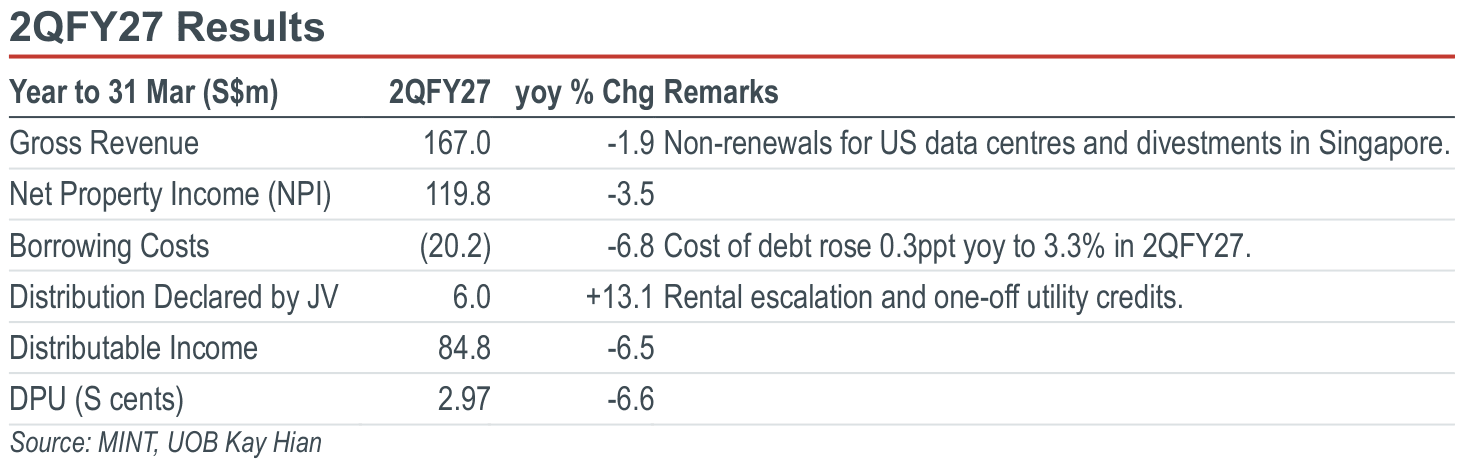
- Mapletree Industrial Trust (MINT) reported DPU of 2.97 cents for 2QFY27, down 6.6% yoy but in line with our expectation.
- Revenue and NPI fell 1.9% and 3.5% yoy respectively in 2QFY27, reflecting lower North American contributions, the absence of income from three Singapore properties divested in Aug 25 and Japanese yen depreciation against the Singapore dollar. Distribution declared by JV increased 13.1% yoy due to utility credits and rental escalation, partially offset by repricing interest rate swaps.
- Singapore and Japan are key stabilisers. Singapore occupancy was broadly stable at 94.2% in 2QFY27, while Japan remained fully occupied. Singapore weighted average rental reversion strengthened to 6.9% from 5.3%, comprising 7.1% for general industrial buildings and 3.7% for hi-tech buildings & business space. Tenant retention was 77.3%. Occupancy for hi-tech buildings & business space improved 1.8ppt qoq to 90.1% due to new leases at Serangoon North Cluster. Mapletree Hi-Tech Park @ Kallang Way maintained leasing momentum with occupancy improving 5.9ppt to 72.4% as of Sep 26 and expected to exceed 75%.
Highlights
- Singapore occupancy was broadly stable at 94.2% in 2QFY27. Average rental reversion strengthened to 6.9%, comprising 7.1% for general industrial buildings and 3.7% for hi-tech buildings & business space.
- North American occupancy declined 3.4ppt qoq to 79.1%, reflecting the full-quarter impact of the non-renewal at 7337 Trade Street, San Diego. After quarter-end, MINT secured new 15.5-year and 5.3-year leases for data centres at Alpharetta and San Jose commencing in Oct 26.
- Upgrade to HOLD as MINT’s unit price has dropped 9.8% since our downgrade on 10 Sep 26. Target price: S$1.72.
Analysis
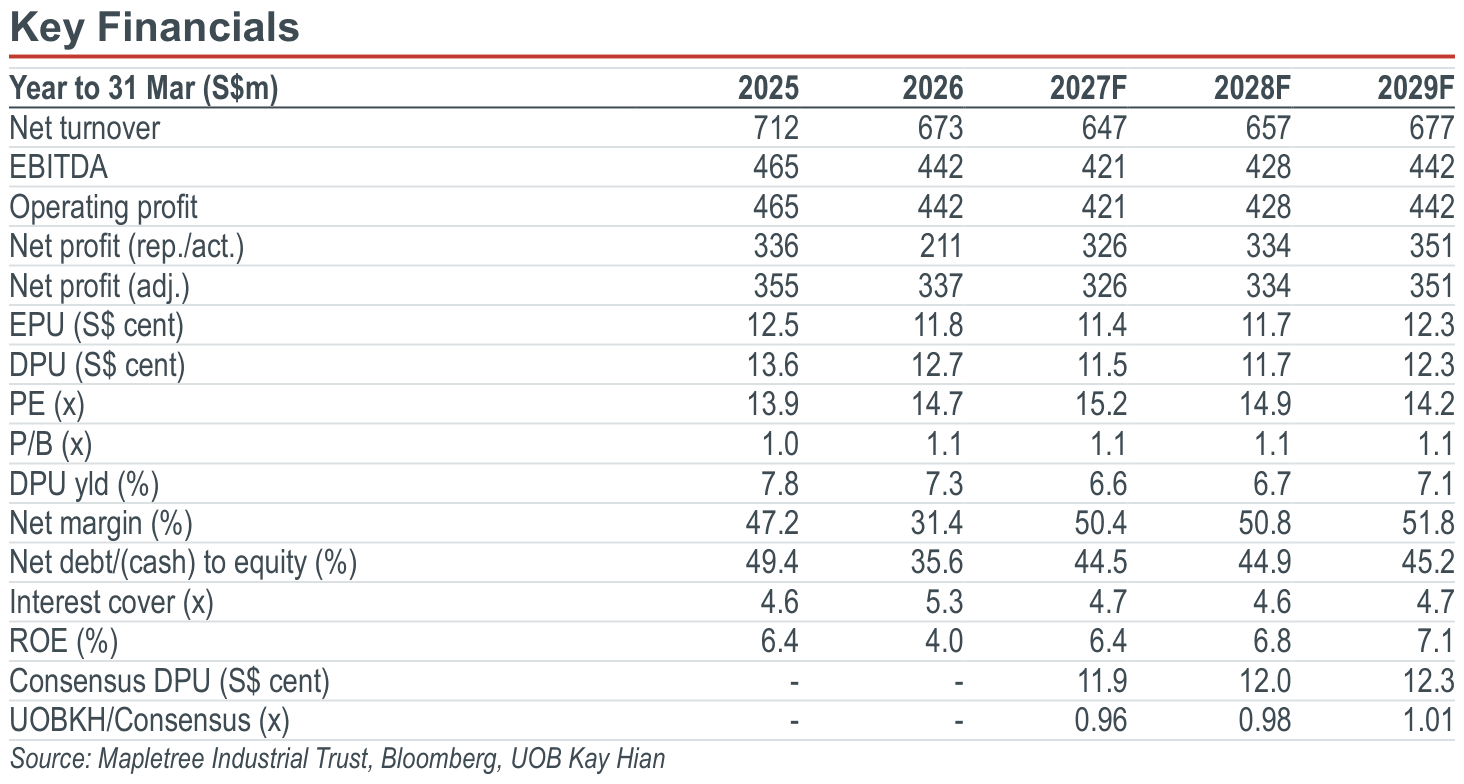
- Mapletree Industrial Trust (MINT) reported DPU of 2.97 cents for 2QFY27, down 6.6% yoy but in line with our expectation.
- Revenue and NPI fell 1.9% and 3.5% yoy respectively in 2QFY27, reflecting lower North American contributions, the absence of income from three Singapore properties divested in Aug 25 and Japanese yen depreciation against the Singapore dollar. Distribution declared by JV increased 13.1% yoy due to utility credits and rental escalation, partially offset by repricing interest rate swaps.
- Singapore and Japan are key stabilisers. Singapore occupancy was broadly stable at 94.2% in 2QFY27, while Japan remained fully occupied. Singapore weighted average rental reversion strengthened to 6.9% from 5.3%, comprising 7.1% for general industrial buildings and 3.7% for hi-tech buildings & business space. Tenant retention was 77.3%. Occupancy for hi-tech buildings & business space improved 1.8ppt qoq to 90.1% due to new leases at Serangoon North Cluster. Mapletree Hi-Tech Park @ Kallang Way maintained leasing momentum with occupancy improving 5.9ppt to 72.4% as of Sep 26 and expected to exceed 75%.
HOLD (Upgraded)
Current price:
Target price:
Upside:
S$1.74
S$1.72
-1.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

21 Sept 2026
Mapletree Pan Asia Commercial Trust (MPACT SP): Green Shoots In Hong Kong And Japan

21 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): Retail Upside From Acquisition; Office Upside From Positive Reversion
Our latest research
29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

29 Oct 2026
UI Boustead REIT (UIBREIT SP): 1HFY27: Steady Progress On Leasing And Co-development

29 Oct 2026