
Company Coverage
Oversea-Chinese Banking Corp (OCBC SP): 3Q26: Banking Strength Offsets Insurance Weakness
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$27.73
S$33.00
19.0%
S$35.70
Analyst
Highlights
OCBC reported 3Q26 net profit of S$2,042m, up 3% yoy but down 8% qoq, as weaker Great Eastern investment returns tempered record banking profits. Strong loan growth supported NII, while fees remained near record levels and wealth AUM reached S$358b.
Asset quality improved. NPLs fell 3% qoq to S$3,044m due to recovery from real estate exposures in China. New NPLs were benign at S$127m as NPL ratio improved 0.1ppt qoq to 0.8%. Credit costs declined to 6bp.
OCBC aims to grow domestically in Malaysia and Indonesia under its New Frontier strategy. While Malaysia is growing from strength to strength, Indonesia faces potential crunch of being relegated to a Standalone Market status by MSCI. Maintain BUY with a lower target price of S$33.00.
Analysis
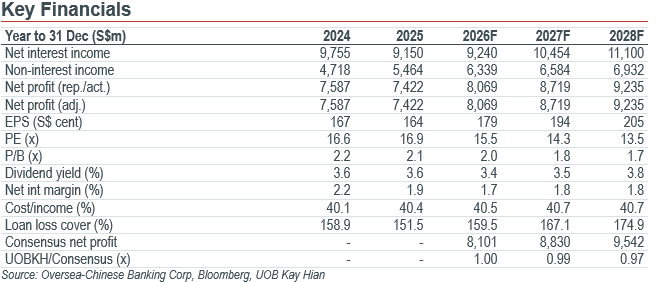
Oversea-Chinese Banking Corp (OCBC) reported 3Q26 net profit of S$2,042m (+3% yoy, -8% qoq), as record Banking Operations profit was offset by weaker Great Eastern investment performance. The results were in line with our forecast net profit of S$2,813m. ROE was 13.1% in 3Q26.
Asset growth offset margin compression. Net interest income (NII) rose 4% yoy and 2% qoq to S$2,313m, supported by loan growth of 14% yoy and 3% qoq in constant-currency terms. NIM fell 18bp yoy and 4bp qoq to 1.66% as higher funding costs outweighed improved asset yields. Higher SORA benefited NII, while US funding costs repriced faster than assets (3M SOFR surged in anticipation and ahead of Fed’s rate hike). Management expects to benefit as US assets reprice in upcoming quarters.
Fees remained near record levels as AUM expanded. Net fee income rose 8% yoy but eased 1% qoq to S$735m. Wealth management fees increased 3% yoy but fell 6% qoq, the second-highest quarterly level. AUM rose 7% yoy and 2% qoq to a record S$358b, supported by continued net new money inflows. Loan, trade, guarantee and remittance fees rose 23% yoy.
Record customer flows cushioned weaker trading income. Trading income declined 10% yoy and 33% qoq to S$465m despite record customer flow income, up 29% yoy. Non-customer flow income turned negative at S$15m, reflecting Great Eastern bond mark-to-market losses and the absence of significant equity gains recorded in 2Q26.
Insurance earnings fell despite resilient underlying business. Life and general insurance income declined 37% yoy and 48% qoq to S$198m, reflecting market-driven valuation losses. New business embedded value rose 14% yoy to S$208m, while its margin improved 6.5ppt qoq to 57.5%.
Income from Bank of Ningbo grew 19% yoy to S$331m in 3Q26.
Expenses eased. Operating expenses were flat yoy and fell 3% qoq to S$1,522m. The cost-to-income ratio rose 3ppt qoq to 40.8%. For 9M26, the ratio was stable at 39.2%.
Highlights
OCBC reported 3Q26 net profit of S$2,042m, up 3% yoy but down 8% qoq, as weaker Great Eastern investment returns tempered record banking profits. Strong loan growth supported NII, while fees remained near record levels and wealth AUM reached S$358b.
Asset quality improved. NPLs fell 3% qoq to S$3,044m due to recovery from real estate exposures in China. New NPLs were benign at S$127m as NPL ratio improved 0.1ppt qoq to 0.8%. Credit costs declined to 6bp.
OCBC aims to grow domestically in Malaysia and Indonesia under its New Frontier strategy. While Malaysia is growing from strength to strength, Indonesia faces potential crunch of being relegated to a Standalone Market status by MSCI. Maintain BUY with a lower target price of S$33.00.
Analysis
Oversea-Chinese Banking Corp (OCBC) reported 3Q26 net profit of S$2,042m (+3% yoy, -8% qoq), as record Banking Operations profit was offset by weaker Great Eastern investment performance. The results were in line with our forecast net profit of S$2,813m. ROE was 13.1% in 3Q26.
Asset growth offset margin compression. Net interest income (NII) rose 4% yoy and 2% qoq to S$2,313m, supported by loan growth of 14% yoy and 3% qoq in constant-currency terms. NIM fell 18bp yoy and 4bp qoq to 1.66% as higher funding costs outweighed improved asset yields. Higher SORA benefited NII, while US funding costs repriced faster than assets (3M SOFR surged in anticipation and ahead of Fed’s rate hike). Management expects to benefit as US assets reprice in upcoming quarters.
Fees remained near record levels as AUM expanded. Net fee income rose 8% yoy but eased 1% qoq to S$735m. Wealth management fees increased 3% yoy but fell 6% qoq, the second-highest quarterly level. AUM rose 7% yoy and 2% qoq to a record S$358b, supported by continued net new money inflows. Loan, trade, guarantee and remittance fees rose 23% yoy.
Record customer flows cushioned weaker trading income. Trading income declined 10% yoy and 33% qoq to S$465m despite record customer flow income, up 29% yoy. Non-customer flow income turned negative at S$15m, reflecting Great Eastern bond mark-to-market losses and the absence of significant equity gains recorded in 2Q26.
Insurance earnings fell despite resilient underlying business. Life and general insurance income declined 37% yoy and 48% qoq to S$198m, reflecting market-driven valuation losses. New business embedded value rose 14% yoy to S$208m, while its margin improved 6.5ppt qoq to 57.5%.
Income from Bank of Ningbo grew 19% yoy to S$331m in 3Q26.
Expenses eased. Operating expenses were flat yoy and fell 3% qoq to S$1,522m. The cost-to-income ratio rose 3ppt qoq to 40.8%. For 9M26, the ratio was stable at 39.2%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$27.73
S$33.00
19.0%
S$35.70
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

6 Nov 2026
DBS Group Holdings (DBS SP) - 3Q26: Focus On Resiliency And Growth Of Core Franchise

5 Nov 2026
United Overseas Bank (UOB SP) - 3Q26: Earnings Shortfall From Other Non-Interest Income

10 Nov 2026
Frasers Logistics & Commercial Trust (FLT SP): 2HFY26: Logistics Strength But Higher Gearing Limits Debt Headroom
Our latest research
10 Nov 2026
Frasers Logistics & Commercial Trust (FLT SP): 2HFY26: Logistics Strength But Higher Gearing Limits Debt Headroom

10 Nov 2026
Venture Corporation (VMS SP): 3Q26: Broadening Growth Led By Portfolio B; Maintain BUY
6 Nov 2026