Periodic/Sector reports
REITs: Data Centre REITs: Value Emerges After The Carnage
OVERWEIGHT (Maintained)
Analyst
Highlights
- Uncertain commercial returns, heavy capital requirements and rising borrowing costs have hurt leveraged neocloud providers and delayed DC IPOs. Established hyperscalers remain better positioned thanks to diversified earnings and stronger cash flows.
- Power shortages, tighter financing and environmental opposition are slowing new development, which reinforce the value proposition of operational DCs and efforts to backfill vacant capacity. AI’s benefits remain intact, but infrastructure investment needs to be spread over a longer period of time.
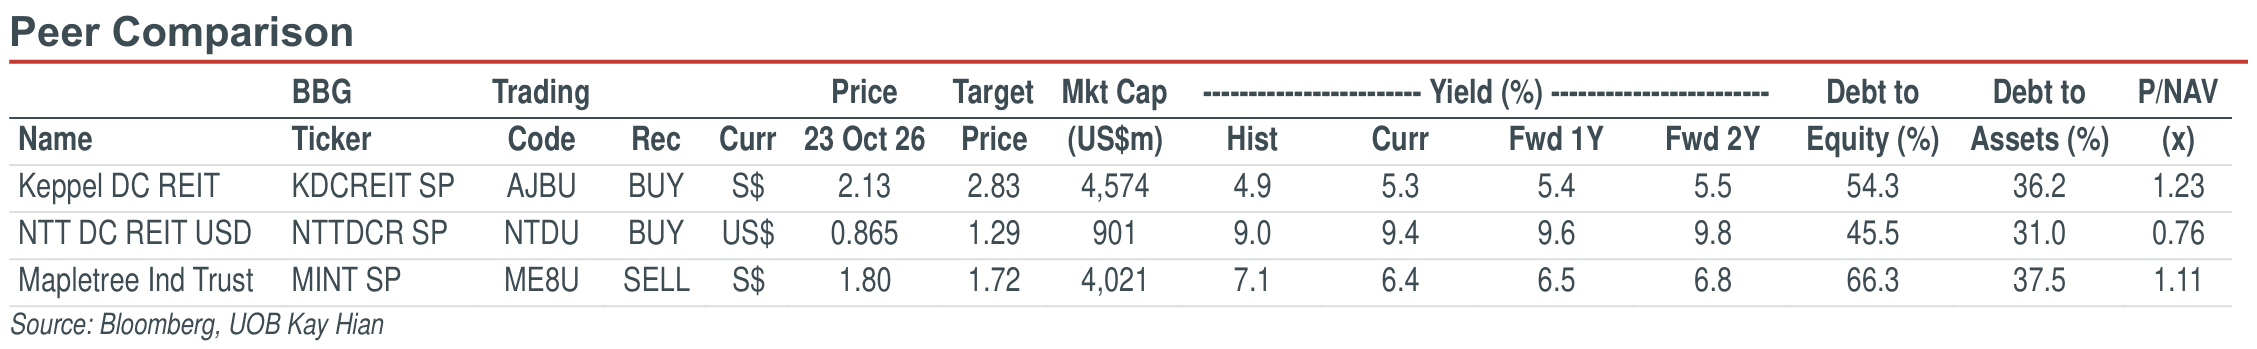
- Maintain OVERWEIGHT. NTTDCR (BUY/Target: US$1.29) offers the highest FY27 DPU yield of 9.4%. KDCREIT (BUY/Target: S$2.83) has a resilient Singapore-centric portfolio and is well supported by sponsor Keppel.
Analysis
- Reality check on AI ROI. Financial markets are reassessing whether artificial intelligence (AI) can generate sufficient commercial returns to justify the enormous upfront investment in chips, data centres (DC) and power infrastructure. Investors are demanding clearer evidence that adoption can translate into recurring revenues, productivity gains and sustainable cash flows, amid uncertainty over monetisation timelines and rising capital intensity. The upfront expenditure is immediate, but the scale and timing of the eventual payoff remain uncertain. Investors have become more selective and are scrutinising whether companies can demonstrate pricing power, profitable customer demand and disciplined capital allocation.
- Creative destruction: Neocloud providers decimated. Neocloud providers, which rent specialised computing capacity to AI developers, operate a capital-intensive and highly leveraged business model. They must commit substantial sums to GPUs and DCs before collecting the associated revenues. This leaves them exposed to heavy debt servicing, falling GPU rental prices and technological advances that could erode the earning power and resale value of their hardware. Dependence on a small number of large customers compound these risks, while construction delays or power constraints postpone their anticipated revenues. Share prices for CoreWeave and Nebius have corrected 46% and 43% respectively thus far in 2H26.
- Many DC IPOs delayed. Recent setbacks in DC and AI infrastructure IPOs suggest investors are becoming less willing to pay premium valuations for growth that requires substantial upfront capital. Australia’s Firmus withdrew its planned IPO in October, while Blackstone-backed AirTrunk postponed its proposed US$1.5b Singapore REIT listing, reportedly targeting completion by early-27. Weak trading debuts have reinforced this caution - South Korean digital infrastructure company Elice fell 32% on its first trading day on 20 Oct 26.
Highlights
- Uncertain commercial returns, heavy capital requirements and rising borrowing costs have hurt leveraged neocloud providers and delayed DC IPOs. Established hyperscalers remain better positioned thanks to diversified earnings and stronger cash flows.
- Power shortages, tighter financing and environmental opposition are slowing new development, which reinforce the value proposition of operational DCs and efforts to backfill vacant capacity. AI’s benefits remain intact, but infrastructure investment needs to be spread over a longer period of time.
- Maintain OVERWEIGHT. NTTDCR (BUY/Target: US$1.29) offers the highest FY27 DPU yield of 9.4%. KDCREIT (BUY/Target: S$2.83) has a resilient Singapore-centric portfolio and is well supported by sponsor Keppel.
Analysis
- Reality check on AI ROI. Financial markets are reassessing whether artificial intelligence (AI) can generate sufficient commercial returns to justify the enormous upfront investment in chips, data centres (DC) and power infrastructure. Investors are demanding clearer evidence that adoption can translate into recurring revenues, productivity gains and sustainable cash flows, amid uncertainty over monetisation timelines and rising capital intensity. The upfront expenditure is immediate, but the scale and timing of the eventual payoff remain uncertain. Investors have become more selective and are scrutinising whether companies can demonstrate pricing power, profitable customer demand and disciplined capital allocation.
- Creative destruction: Neocloud providers decimated. Neocloud providers, which rent specialised computing capacity to AI developers, operate a capital-intensive and highly leveraged business model. They must commit substantial sums to GPUs and DCs before collecting the associated revenues. This leaves them exposed to heavy debt servicing, falling GPU rental prices and technological advances that could erode the earning power and resale value of their hardware. Dependence on a small number of large customers compound these risks, while construction delays or power constraints postpone their anticipated revenues. Share prices for CoreWeave and Nebius have corrected 46% and 43% respectively thus far in 2H26.
- Many DC IPOs delayed. Recent setbacks in DC and AI infrastructure IPOs suggest investors are becoming less willing to pay premium valuations for growth that requires substantial upfront capital. Australia’s Firmus withdrew its planned IPO in October, while Blackstone-backed AirTrunk postponed its proposed US$1.5b Singapore REIT listing, reportedly targeting completion by early-27. Weak trading debuts have reinforced this caution - South Korean digital infrastructure company Elice fell 32% on its first trading day on 20 Oct 26.
OVERWEIGHT (Maintained)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles


Our latest research

22 Oct 2026
REITs: Value Emerges With Expanded Yield Spread

20 Oct 2026
Technology: Stay Selective On Stocks With High Yields And Strong Balance Sheets

16 Oct 2026