
Wealth Daily
Anthropic IPO Tops Range as US Insurers Fall
Today’s Must-Know News
Overnight Markets
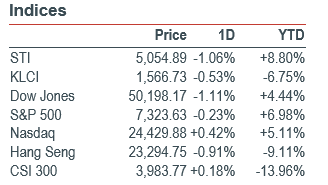
Market Movers: At the 18 November close, the S&P 500 fell 0.23% and the Dow lost about 1.10%. Nvidia (NVDA US) fell about 2.90% in its first session after earnings, reversing an early gain. Its US$130bn fourth-quarter revenue forecast excludes China data-centre compute sales. Tencent (0700.HK) grew revenue 8% YoY to RMB207.3bn, but capital spending more than tripled to RMB65.1bn. Prepayments for computing capacity weighed on free cash flow. Its US receipts (TCEHY US) fell about 2.4% after the release. UnitedHealth (UNH US) lost about 10.2% as investors continued to weigh proposed Medicare Advantage audits. Bloomberg reported that Anthropic priced its IPO at US$83 a share, above the US$70–78 range, ahead of trading. (AP / Nvidia / Tencent / Yahoo Finance / Bloomberg via Yahoo Finance) Nvidia (NVDA US) and Tencent (0700.HK) are our Core Recommendations.
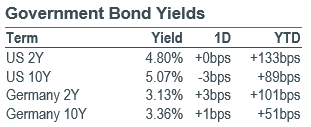
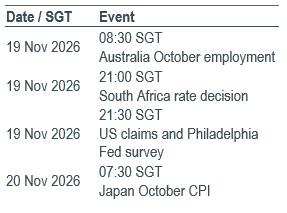
Macro: The Fed voted 10–2 to hold rates at 3.75–4.00% in October. Newly released minutes showed that almost all participants expected further increases under their baseline outlook. A couple saw a case for a move larger than 25bp at the next meeting if incoming data disappointed on inflation. South Africa’s rate decision is due today. Before October inflation rose to 5.2% YoY from 4.5%, 24 of 27 economists polled expected a hold at 7.25%. A hawkish surprise could lift rate expectations. (Federal Reserve / Reuters)
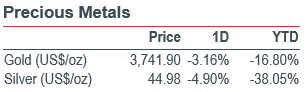
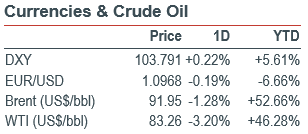
FICC: US commercial crude inventories rose 3.4m barrels to 417.8m. December WTI settled at US$83.26/bbl, down 3.20%, and January Brent at US$91.95, down 1.28%. December gold settled at US$3,741.90/oz, down 3.16%, ahead of the Fed minutes. December silver traded about 4.9% lower near the New York close. (EIA / eOption / Reuters / Yahoo Finance)
AI
Nvidia gives up an early rally after its earnings beat. Nvidia (NVDA US) gained about 2.7% early before closing down 2.89% at US$150.96 in the first full session after earnings. Interim chief executive Colette Kress said customers and partners remained committed. Quarterly revenue had risen 103% YoY to US$115.8bn, but the US$130bn midpoint of its next-quarter forecast includes an extra week and excludes China data-centre compute sales. The reversal shows how much reassurance investors still want about demand under the new leadership. (AP / Nvidia) Nvidia (NVDA US) is our Core Recommendation.
Anthropic prices its IPO above the marketed range. Anthropic priced its IPO at US$83 a share, above its US$70–78 range, Axios reported ahead of the Nasdaq debut. That implies an initial market capitalisation of US$1.08tn and a fully diluted valuation of nearly US$1.5tn. The prospectus separately describes a US$26bn private placement contingent on the IPO closing. The pricing sets a public valuation benchmark for other AI developers, while the first exchange trades will show how much demand persists beyond the offering. (Axios / Anthropic prospectus / Yahoo Finance / Bloomberg)
Palo Alto Networks agrees to buy Applied Compute for US$4.5bn. Palo Alto Networks (PANW US) agreed after the close to purchase Applied Compute for US$4.5bn in stock, subject to regulatory clearance. The acquisition would let customers adapt and run open-weight models within their own security controls. Fiscal first-quarter revenue rose 39% YoY to US$3.44bn and next-generation security annual recurring revenue grew 66% to US$9.73bn. Shares had already closed 9.90% higher before the announcements, leaving investors to assess the deal’s dilution alongside that growth. (Palo Alto Networks acquisition / Palo Alto Networks results / Yahoo Finance price)
Google opens its interactive world model to premium subscribers. Alphabet (GOOGL US) began offering Genie 4 to eligible Google AI Ultra subscribers, while AI Pro members can join a waitlist. Users can change a scene with text while exploring it, and the model generates sound that changes with the action. Google identifies scene persistence and camera latency as remaining limitations. Offering the model first on its premium tier gives Google a way to test whether interactive worlds can attract or retain paying subscribers. (Google) Alphabet (GOOGL US) is our Core Recommendation.
Americas
Medicare audit proposal drives a second sell-off in US health insurers. UnitedHealth (UNH US) fell 10.21% to US$349.91 and Humana (HUM US) lost 12.98% to US$385.78 as investors reassessed Monday’s proposed Medicare Advantage audit changes. US regulators propose extrapolating audit findings starting with payment year 2018 and estimate average recoveries of about US$9bn per payment year across the programme. The proposal leaves individual insurers’ exposure uncertain, making the eventual audit method and the mix of Medicare Advantage business important to future earnings. (CMS / Yahoo Finance)
TJX gains as stronger comparable sales lift its outlook. TJX (TJX US) rose 8.05% to US$140.30 after fiscal third-quarter net sales increased 6% YoY to US$16.0bn and comparable sales rose 4%. Diluted earnings reached US$1.39 per share, up 9%, or US$1.34 after excluding a five-cent net tariff-refund benefit. TJX now expects full-year comparable sales growth of 4% and adjusted earnings of US$5.17–5.20 per share. The adjusted figure gives investors a clearer view of what merchandise demand contributed. (TJX filing / AP)
Target sees more customers and raises its sales outlook. Target (TGT US) gained 4.01% to US$165.93 as third-quarter net sales rose 7.1% YoY to US$27.1bn. Comparable sales grew 5.6% on 5.0% higher traffic. Adjusted earnings reached US$2.65 per share, including a US$0.50 tariff refund. Excluding it, adjusted earnings were US$2.15, up 21% YoY. Target lifted its full-year sales growth forecast to about 6%, giving investors a way to judge whether the recovery in customer visits carries through holiday trading. (Target / AP)
Lowe lifts its sales outlook and trims its margin forecast. Lowe’s (LOW US) rose 1.05% to US$222.78 after third-quarter sales increased 9.3% YoY to US$22.8bn, with comparable sales up 1.8%. Adjusted earnings rose 1.3% to US$3.10 per share, including a US$0.34 tariff-refund benefit. Management raised its full-year sales forecast from US$92.0bn to US$92.5bn while trimming expected adjusted operating margin from 11.6% to 11.5%. The narrower margin outlook tempers what stronger sales imply for underlying profit growth. (Lowe’s / Yahoo Finance price)
Take-Two rises as early reviews lift expectations for Grand Theft Auto VI. Take-Two Interactive (TTWO US) gained 6.22% to US$216.61 as early reviews of Rockstar Games’ Grand Theft Auto VI lifted expectations for its launch. Oppenheimer estimated the game could generate US$1.85bn of gross revenue in its first three days, compared with US$1bn for its predecessor. The estimate sets a high bar for opening sales, while the durability of demand and spending on additional content will matter to bookings beyond the launch. (AP / Proactive / Rockstar Games)
Greater China
AI investment narrows Tencent’s operating margin. Tencent (0700.HK) reported third-quarter revenue of RMB207.3bn, up 8% YoY. Non-IFRS operating profit fell 6% to RMB68.1bn and its margin narrowed to 33% from 38%. Excluding new AI products, operating profit on the same basis rose 8% to RMB83.3bn. Capital expenditure payments rose 225% to RMB65.1bn, showing how rapidly spending is rising relative to revenue. Tencent’s US receipts fell about 2.4% in the session after the results. (Tencent / US receipt history) Tencent (0700.HK) is our Core Recommendation.
JD Health drops after reported profit falls. JD Health (6618.HK) fell about 15.4% in its first Hong Kong session after its quarterly results. Third-quarter revenue rose 16.9% YoY to RMB20.0bn, while reported profit fell 15.3% to RMB1.56bn. Non-IFRS profit increased just 1.5% to RMB1.93bn. Even on the company’s adjusted measure, earnings growth lagged revenue by more than 15 percentage points. The next results will show whether a larger sales base translates into stronger profit growth. (JD Health / HKEX / HK price history)
AstraZeneca licence fee lifts CSPC’s nine-month profit. CSPC Pharmaceutical (1093.HK) reported nine-month profit attributable to shareholders of RMB7.08bn, up 101.5% YoY, on revenue of RMB25.26bn, up 27.0%. Licence fee income increased 307% to RMB6.27bn. Of that total, RMB5.74bn came from recognising part of AstraZeneca’s upfront payment. Sales of finished pharmaceutical products grew 10.6% to RMB15.38bn. Investors assessing repeatable earnings can track medicine sales separately from the timing of licence income under the partnership. (CSPC / HKEX / S&P Capital IQ)
Weibo softer sales and higher costs squeeze operating returns. Weibo (WB US; 9898.HK) fell about 4.0% in US trading after third-quarter revenue declined 7% YoY to US$410.2m. Operating profit dropped to US$64.3m from US$117.3m, taking the margin to 16% from 27%. Costs and expenses increased 6%, partly because of higher advertising production costs. The combination leaves earnings more exposed to weak advertising demand; stabilising revenue alone may be insufficient without better production efficiency and tighter control of the operating cost base. (Weibo / Market data)
Asia ex. China
Japan exports hit a record, but its trade deficit widens. Japan’s October merchandise exports climbed 20.5% YoY to ¥11.77tn, a record in value terms. Shipments to the US increased 23.9% and those to China grew 13.3%. Imports rose faster, up 21.6% to ¥12.25tn, even as import volumes edged down 0.2%. The trade deficit consequently widened to ¥476.5bn from ¥301.9bn a year earlier. For companies exposed to Japan’s trade cycle, higher import costs offset part of the benefit of strong overseas sales. (Japan Customs / Reuters)
Jardine leads Singapore’s blue chips after its trading update. Jardine Matheson (J36 SP) gained 2.43% to US$60.59 in its first Singapore session after its quarterly update, even as the Straits Times Index fell about 1.1%. Jardine expects a full-year dividend of at least US$2.5 per share, up 6% YoY. It had completed 36% of its US$500m share buyback and recycled or agreed to recycle US$1.4bn of capital, excluding Hongkong Land and Astra. Those transactions give shareholders another measure of progress alongside the dividend. (Jardine Matheson / The Business Times)
Hanwha Systems wins its first US radar customer. Hanwha Systems (272210 KS) said US defence company Rebellion Industries placed its first American radar order. The initial agreement covers a pilot project, with delivery expected by early 2027. Hanwha did not disclose a contract value. Its shares finished 0.92% higher in Seoul. The order gives the South Korean supplier a US customer reference. The financial significance will become clearer if Rebellion commits to purchases beyond the pilot. (Yonhap / Korea price history)
EMEA and Others
Britain’s regulated networks drive SSE’s profit growth. SSE (SSE LN) reported adjusted first-half operating profit of £1.10bn, up 68% YoY, and adjusted earnings of 66.5p per share, up 83%. It invested £2.56bn, 63% more than a year earlier, with about 70% directed to regulated electricity networks. Those networks supplied around two-thirds of adjusted operating profit. SSE maintained its full-year adjusted earnings range of 168p–193p per share, giving investors a benchmark for the return on its expanding grid investment. (SSE)
Experian raises buybacks as margins improve. Experian (EXPN LN) announced a further US$500m share repurchase after first-half organic revenue grew 7% YoY. Benchmark operating profit from ongoing activities rose 11% at actual exchange rates to US$1.28bn, while the corresponding margin expanded 50 basis points to 28.8%. The credit-data group expects 6%–7% organic revenue growth for the full year as higher interest rates weigh on US mortgage volumes. The buyback takes repurchases announced this calendar year to US$2.5bn. (Experian)
Traders' Corner
Our Technical View
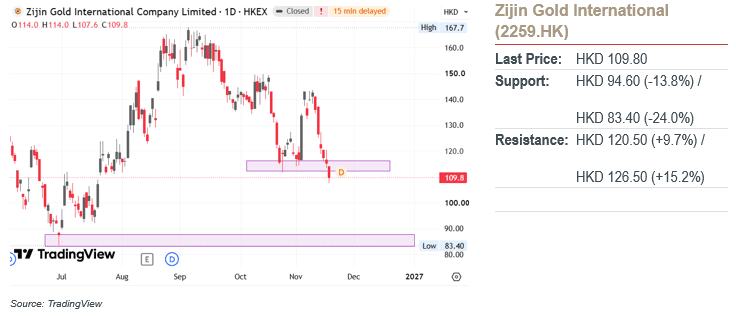
Price violated its previous low support zone during recent downward testing.
The RSI sits firmly in bearish territory and continues to fall.
Provided price remains capped below the support-turned-resistance ceiling, we see continued downward progression toward deeper structural lows.
Our Technical View
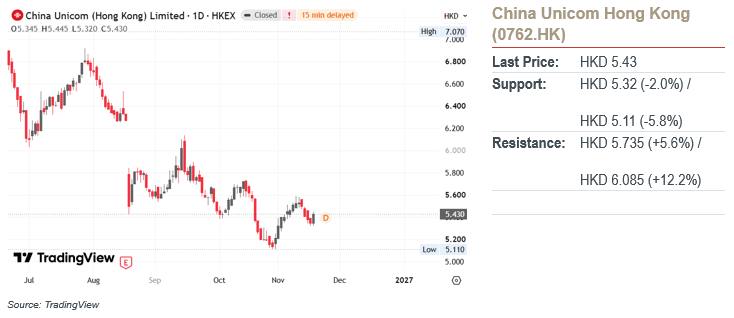
Price formed a bullish engulfing candlestick pattern during recent pullback testing, signaling the potential formation of a higher low.
The RSI is rising steadily toward its neutral 50 level.
Provided price remains supported above the bullish engulfing pattern low on intraday dips, we see continued upward progression toward higher overhead resistance targets.
Market Movers: At the 18 November close, the S&P 500 fell 0.23% and the Dow lost about 1.10%. Nvidia (NVDA US) fell about 2.90% in its first session after earnings, reversing an early gain. Its US$130bn fourth-quarter revenue forecast excludes China data-centre compute sales. Tencent (0700.HK) grew revenue 8% YoY to RMB207.3bn, but capital spending more than tripled to RMB65.1bn. Prepayments for computing capacity weighed on free cash flow. Its US receipts (TCEHY US) fell about 2.4% after the release. UnitedHealth (UNH US) lost about 10.2% as investors continued to weigh proposed Medicare Advantage audits. Bloomberg reported that Anthropic priced its IPO at US$83 a share, above the US$70–78 range, ahead of trading. (AP / Nvidia / Tencent / Yahoo Finance / Bloomberg via Yahoo Finance) Nvidia (NVDA US) and Tencent (0700.HK) are our Core Recommendations.
Macro: The Fed voted 10–2 to hold rates at 3.75–4.00% in October. Newly released minutes showed that almost all participants expected further increases under their baseline outlook. A couple saw a case for a move larger than 25bp at the next meeting if incoming data disappointed on inflation. South Africa’s rate decision is due today. Before October inflation rose to 5.2% YoY from 4.5%, 24 of 27 economists polled expected a hold at 7.25%. A hawkish surprise could lift rate expectations. (Federal Reserve / Reuters)
FICC: US commercial crude inventories rose 3.4m barrels to 417.8m. December WTI settled at US$83.26/bbl, down 3.20%, and January Brent at US$91.95, down 1.28%. December gold settled at US$3,741.90/oz, down 3.16%, ahead of the Fed minutes. December silver traded about 4.9% lower near the New York close. (EIA / eOption / Reuters / Yahoo Finance)
AI
Nvidia gives up an early rally after its earnings beat. Nvidia (NVDA US) gained about 2.7% early before closing down 2.89% at US$150.96 in the first full session after earnings. Interim chief executive Colette Kress said customers and partners remained committed. Quarterly revenue had risen 103% YoY to US$115.8bn, but the US$130bn midpoint of its next-quarter forecast includes an extra week and excludes China data-centre compute sales. The reversal shows how much reassurance investors still want about demand under the new leadership. (AP / Nvidia) Nvidia (NVDA US) is our Core Recommendation.
Anthropic prices its IPO above the marketed range. Anthropic priced its IPO at US$83 a share, above its US$70–78 range, Axios reported ahead of the Nasdaq debut. That implies an initial market capitalisation of US$1.08tn and a fully diluted valuation of nearly US$1.5tn. The prospectus separately describes a US$26bn private placement contingent on the IPO closing. The pricing sets a public valuation benchmark for other AI developers, while the first exchange trades will show how much demand persists beyond the offering. (Axios / Anthropic prospectus / Yahoo Finance / Bloomberg)
Palo Alto Networks agrees to buy Applied Compute for US$4.5bn. Palo Alto Networks (PANW US) agreed after the close to purchase Applied Compute for US$4.5bn in stock, subject to regulatory clearance. The acquisition would let customers adapt and run open-weight models within their own security controls. Fiscal first-quarter revenue rose 39% YoY to US$3.44bn and next-generation security annual recurring revenue grew 66% to US$9.73bn. Shares had already closed 9.90% higher before the announcements, leaving investors to assess the deal’s dilution alongside that growth. (Palo Alto Networks acquisition / Palo Alto Networks results / Yahoo Finance price)
Google opens its interactive world model to premium subscribers. Alphabet (GOOGL US) began offering Genie 4 to eligible Google AI Ultra subscribers, while AI Pro members can join a waitlist. Users can change a scene with text while exploring it, and the model generates sound that changes with the action. Google identifies scene persistence and camera latency as remaining limitations. Offering the model first on its premium tier gives Google a way to test whether interactive worlds can attract or retain paying subscribers. (Google) Alphabet (GOOGL US) is our Core Recommendation.
Americas
Medicare audit proposal drives a second sell-off in US health insurers. UnitedHealth (UNH US) fell 10.21% to US$349.91 and Humana (HUM US) lost 12.98% to US$385.78 as investors reassessed Monday’s proposed Medicare Advantage audit changes. US regulators propose extrapolating audit findings starting with payment year 2018 and estimate average recoveries of about US$9bn per payment year across the programme. The proposal leaves individual insurers’ exposure uncertain, making the eventual audit method and the mix of Medicare Advantage business important to future earnings. (CMS / Yahoo Finance)
TJX gains as stronger comparable sales lift its outlook. TJX (TJX US) rose 8.05% to US$140.30 after fiscal third-quarter net sales increased 6% YoY to US$16.0bn and comparable sales rose 4%. Diluted earnings reached US$1.39 per share, up 9%, or US$1.34 after excluding a five-cent net tariff-refund benefit. TJX now expects full-year comparable sales growth of 4% and adjusted earnings of US$5.17–5.20 per share. The adjusted figure gives investors a clearer view of what merchandise demand contributed. (TJX filing / AP)
Target sees more customers and raises its sales outlook. Target (TGT US) gained 4.01% to US$165.93 as third-quarter net sales rose 7.1% YoY to US$27.1bn. Comparable sales grew 5.6% on 5.0% higher traffic. Adjusted earnings reached US$2.65 per share, including a US$0.50 tariff refund. Excluding it, adjusted earnings were US$2.15, up 21% YoY. Target lifted its full-year sales growth forecast to about 6%, giving investors a way to judge whether the recovery in customer visits carries through holiday trading. (Target / AP)
Lowe lifts its sales outlook and trims its margin forecast. Lowe’s (LOW US) rose 1.05% to US$222.78 after third-quarter sales increased 9.3% YoY to US$22.8bn, with comparable sales up 1.8%. Adjusted earnings rose 1.3% to US$3.10 per share, including a US$0.34 tariff-refund benefit. Management raised its full-year sales forecast from US$92.0bn to US$92.5bn while trimming expected adjusted operating margin from 11.6% to 11.5%. The narrower margin outlook tempers what stronger sales imply for underlying profit growth. (Lowe’s / Yahoo Finance price)
Take-Two rises as early reviews lift expectations for Grand Theft Auto VI. Take-Two Interactive (TTWO US) gained 6.22% to US$216.61 as early reviews of Rockstar Games’ Grand Theft Auto VI lifted expectations for its launch. Oppenheimer estimated the game could generate US$1.85bn of gross revenue in its first three days, compared with US$1bn for its predecessor. The estimate sets a high bar for opening sales, while the durability of demand and spending on additional content will matter to bookings beyond the launch. (AP / Proactive / Rockstar Games)
Greater China
AI investment narrows Tencent’s operating margin. Tencent (0700.HK) reported third-quarter revenue of RMB207.3bn, up 8% YoY. Non-IFRS operating profit fell 6% to RMB68.1bn and its margin narrowed to 33% from 38%. Excluding new AI products, operating profit on the same basis rose 8% to RMB83.3bn. Capital expenditure payments rose 225% to RMB65.1bn, showing how rapidly spending is rising relative to revenue. Tencent’s US receipts fell about 2.4% in the session after the results. (Tencent / US receipt history) Tencent (0700.HK) is our Core Recommendation.
JD Health drops after reported profit falls. JD Health (6618.HK) fell about 15.4% in its first Hong Kong session after its quarterly results. Third-quarter revenue rose 16.9% YoY to RMB20.0bn, while reported profit fell 15.3% to RMB1.56bn. Non-IFRS profit increased just 1.5% to RMB1.93bn. Even on the company’s adjusted measure, earnings growth lagged revenue by more than 15 percentage points. The next results will show whether a larger sales base translates into stronger profit growth. (JD Health / HKEX / HK price history)
AstraZeneca licence fee lifts CSPC’s nine-month profit. CSPC Pharmaceutical (1093.HK) reported nine-month profit attributable to shareholders of RMB7.08bn, up 101.5% YoY, on revenue of RMB25.26bn, up 27.0%. Licence fee income increased 307% to RMB6.27bn. Of that total, RMB5.74bn came from recognising part of AstraZeneca’s upfront payment. Sales of finished pharmaceutical products grew 10.6% to RMB15.38bn. Investors assessing repeatable earnings can track medicine sales separately from the timing of licence income under the partnership. (CSPC / HKEX / S&P Capital IQ)
Weibo softer sales and higher costs squeeze operating returns. Weibo (WB US; 9898.HK) fell about 4.0% in US trading after third-quarter revenue declined 7% YoY to US$410.2m. Operating profit dropped to US$64.3m from US$117.3m, taking the margin to 16% from 27%. Costs and expenses increased 6%, partly because of higher advertising production costs. The combination leaves earnings more exposed to weak advertising demand; stabilising revenue alone may be insufficient without better production efficiency and tighter control of the operating cost base. (Weibo / Market data)
Asia ex. China
Japan exports hit a record, but its trade deficit widens. Japan’s October merchandise exports climbed 20.5% YoY to ¥11.77tn, a record in value terms. Shipments to the US increased 23.9% and those to China grew 13.3%. Imports rose faster, up 21.6% to ¥12.25tn, even as import volumes edged down 0.2%. The trade deficit consequently widened to ¥476.5bn from ¥301.9bn a year earlier. For companies exposed to Japan’s trade cycle, higher import costs offset part of the benefit of strong overseas sales. (Japan Customs / Reuters)
Jardine leads Singapore’s blue chips after its trading update. Jardine Matheson (J36 SP) gained 2.43% to US$60.59 in its first Singapore session after its quarterly update, even as the Straits Times Index fell about 1.1%. Jardine expects a full-year dividend of at least US$2.5 per share, up 6% YoY. It had completed 36% of its US$500m share buyback and recycled or agreed to recycle US$1.4bn of capital, excluding Hongkong Land and Astra. Those transactions give shareholders another measure of progress alongside the dividend. (Jardine Matheson / The Business Times)
Hanwha Systems wins its first US radar customer. Hanwha Systems (272210 KS) said US defence company Rebellion Industries placed its first American radar order. The initial agreement covers a pilot project, with delivery expected by early 2027. Hanwha did not disclose a contract value. Its shares finished 0.92% higher in Seoul. The order gives the South Korean supplier a US customer reference. The financial significance will become clearer if Rebellion commits to purchases beyond the pilot. (Yonhap / Korea price history)
EMEA and Others
Britain’s regulated networks drive SSE’s profit growth. SSE (SSE LN) reported adjusted first-half operating profit of £1.10bn, up 68% YoY, and adjusted earnings of 66.5p per share, up 83%. It invested £2.56bn, 63% more than a year earlier, with about 70% directed to regulated electricity networks. Those networks supplied around two-thirds of adjusted operating profit. SSE maintained its full-year adjusted earnings range of 168p–193p per share, giving investors a benchmark for the return on its expanding grid investment. (SSE)
Experian raises buybacks as margins improve. Experian (EXPN LN) announced a further US$500m share repurchase after first-half organic revenue grew 7% YoY. Benchmark operating profit from ongoing activities rose 11% at actual exchange rates to US$1.28bn, while the corresponding margin expanded 50 basis points to 28.8%. The credit-data group expects 6%–7% organic revenue growth for the full year as higher interest rates weigh on US mortgage volumes. The buyback takes repurchases announced this calendar year to US$2.5bn. (Experian)
Traders' Corner
Our Technical View
Price violated its previous low support zone during recent downward testing.
The RSI sits firmly in bearish territory and continues to fall.
Provided price remains capped below the support-turned-resistance ceiling, we see continued downward progression toward deeper structural lows.
Our Technical View
Price formed a bullish engulfing candlestick pattern during recent pullback testing, signaling the potential formation of a higher low.
The RSI is rising steadily toward its neutral 50 level.
Provided price remains supported above the bullish engulfing pattern low on intraday dips, we see continued upward progression toward higher overhead resistance targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


