Analyst
Elena Chen
elena.chen@uobkh.comAnalyst
Qi Wang, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Key China Market Indices
Index | Price | Past 2-Week Return | YTD Return |
Hang Seng Index | 23,093 | -4.6% | -9.9% |
HSCEI Index | 7,756 | -4.8% | -13.0% |
Hang Seng Tech Index | 3,872 | -7.8% | -29.8% |
Shanghai Composite Index | 3,690 | -3.2% | -7.0% |
CSI 300 Index | 4,105 | -4.9% | -11.3% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Stronger growth reduces stimulus urgency, but domestic demand remains weak. China’s 3Q 2026 GDP growth recovered to 4.5% yoy from 4.3% in 2Q 2026, supported by exports and industrial production. September retail sales improved to 1.1% yoy, partly reflecting holiday timing, while fixed asset investment contracted 7.2% in 9M26, weighed down by a 20.6% decline in property investment. The pickup in growth may reduce the urgency for a large new stimulus package, with policymakers likely to prioritise deploying existing support. Export strength supports growth, but household deleveraging continues to restrain consumption. The macro picture remains mixed.
- AI return concerns and fund outflows weigh on Hong Kong equities. The Hang Seng TECH Index fell 7.8% over the past two weeks, against a 4.6% decline in the Hang Seng Index. Investors are reassessing how quickly heavy AI spending can generate profitable revenue. Southbound investors recorded HKD 23.7bn of net selling, reducing an important source of demand for Hong Kong shares. Foreign fund outflows and elevated US yields add to this pressure. Separately, offshore trust tax enforcement may prompt affected investors to raise cash through share sales, adding potential selling pressure.
- 3Q reporting season brings earnings risks into focus. Earnings delivery is the next test after the sell-off. CATL and China Mobile have already reported 3Q 2026 results below expectations. For upcoming internet results, rising AI costs could limit profit growth even as revenues improve, while heavy capital spending may keep free cash flow under pressure. These pressures leave room for further earnings revisions as results are released, even after the sharp correction in share prices.
- A technical rebound would not yet confirm a sustained recovery. The sharp correction leaves room for a short-term bounce, particularly if policy support helps stabilize sentiment. However, a price rebound alone would not resolve earnings uncertainty or reverse fund outflows. We remain cautious on the indices, with a sustained recovery requiring stronger profits and more supportive fund flows. High-dividend, cash-rich defensive stocks may outperform the broader market in the near term, while selective long-term growth opportunities remain attractive. Tencent (0700.HK) remains our Core Recommendation as a leading AI practitioner with increasingly attractive long-term investment opportunities at current valuations (12x forward PE).
- Best-performing sectors: Utilities -1.7% (e.g. 1816.HK, 1038.HK); Consumer Staples -1.8% (e.g. 2319.HK, 6055.HK); Real Estate -2.4% (e.g. 0823.HK, 0083.HK).
- Potential movers and shakers: Details inside.
Positive | Anta Sports (2020 HK), SHKP (0016 HK) |
Neutral | COLI (0688 HK), CR Land (1109 HK), Longfor (0960 HK) |
Negative | CATL (300750 CH/3750 HK), Sands China (1928 HK) |
- Must Watch Events: Details below.
Date | Macro Data | Sector / Company Events |
Oct 26-29 | CPC Fifth Plenum: policy and implementation signals |
|
Oct 27 | China September industrial profits | HSBC (0005.HK) |
Oct 28 | US FOMC decision (US date; Oct 29 HKT): USD/HKD funding costs | PetroChina (0857.HK), Ping An (2318.HK) |
Oct 29 | US 3Q GDP and September PCE inflation: rates and China export demand | Midea (0300.HK) |
Oct 30 |
| ABC (1288.HK), ICBC (1398.HK), CCB (0939.HK), BOC (3988.HK), CNOOC (0883.HK) |
Oct 31 | China October official manufacturing and non-manufacturing PMIs |
|
Oct 31-Nov 4 |
| Canton Fair Phase 3: export orders and buyer demand |
Nov 2 / 4 | China October RatingDog manufacturing / services PMIs |
|
Nov 5-10 |
| China International Import Expo opens Nov 5: consumption and trade signals |
Best 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Utilities | -1.7% | -1.7% | Cgn Power Co.,Ltd. (1816.HK) +2.3%, Ck Infrastructure Holdings Limited (1038.HK) +1.7%, China Everbright Environment Group Limited (0257.HK) +3.4% |
Consumer Staples | -1.8% | -18.4% | China Mengniu Dairy Company Limited (2319.HK) +2.1%, China Tobacco International (Hk) Company Limited (6055.HK) +12.9%, Yihai International Holding Ltd. (1579.HK) +6.7% |
Real Estate | -2.4% | -3.8% | Link Asset Management Limited (00823.HK) +1.9%, Sino Land Company Limited (0083.HK) +2.1%, Anhui Conch Cement Company Limited (0914.HK) +3.7% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Utilities fell 1.7% over two weeks, leaving the YTD decline at 1.7%. CGN Power and CK Infrastructure gained during the broader sell-off. CGN Power’s new generating capacity supports earnings growth, while potential tariff improvement in 2027 offers a further catalyst beyond its defensive appeal.
- Consumer Staples fell 1.8% over two weeks, extending the YTD decline to 18.4%. Mengniu and Yihai gained. Easing dairy competition could support Mengniu’s margin recovery, providing a company-specific catalyst despite subdued household demand.
- Real Estate fell 2.4% over two weeks, taking the YTD decline to 3.8%. Link REIT and Sino Land gained despite continued weakness in mainland property. Mainland property investment fell 20.6% in 9M26, underscoring the need for stronger policy support to revive the housing market.
Worst 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Information Technology | -10.0% | -32.1% | Tencent Holdings Ltd. (0700.HK) -9.1%, Semiconductor Manufacturing International Corporation (0981.HK) -18.4%, Lenovo Group Limited (0992.HK) -31.1% |
Industrials | -10.7% | -7.4% | Contemporary Amperex Technology Co., Limited (3750.HK) -27.4%, Kingboard Laminates Holdings Ltd. (1888.HK) -23.1%, Weichai Power Co.,Ltd. (2338.HK) -12.1% |
Materials | -12.6% | -27.2% | Zijin Mining Group Company Limited (2899.HK) -10.6%, Cmoc Group Limited (3993.HK) -15.6%, China Hongqiao Group Limited (1378.HK) -10% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Information Technology fell 10.0% over two weeks, extending its YTD decline to 32.1%. Lenovo and SMIC declined sharply during the AI-related sell-off, despite continued structural support from AI infrastructure investment and semiconductor localization. For PC makers such as Lenovo, higher memory and CPU costs add pressure on profitability.
- Industrials fell 10.7% over two weeks, taking the YTD decline to 7.4%. CATL’s 3Q gross margin fell 2.5ppt qoq to 20.7%. Management attributed the decline to product mix and tax-related costs. Tax-sharing negotiations with customers remain ongoing, adding uncertainty to near-term margin recovery. However, domestic EV battery market share rose to 44.2% in Jan-Sep from 42.8% a year earlier, while its share outside China increased to 33.7% in Jan-Aug from 29.0%. These gains reinforce our China Export Shock 2.0 thesis. CATL remains our Core Recommendation, supported by its technology leadership and global expansion.
- Materials was the weakest sector, down 12.6% over two weeks and 27.2% YTD. Zijin Mining’s third-quarter net profit attributable to shareholders rose 26.0% yoy to RMB 18.4bn, but declined sequentially as lower realized gold prices and higher mining costs weighed on earnings. Stronger copper performance partly offset these pressures. In 3Q 2026, operating cash flow of RMB28.8bn comfortably covered approximately RMB6.0bn of cash capital expenditure, supporting future mine development and production growth. However, costs, project execution and acquisition spending will influence how much of this growth translates into shareholder returns. We continue to see a role for gold in portfolio diversification amid de-dollarization, geopolitical and monetary uncertainty. Zijin remains an Investment Opportunity, offering gold exposure alongside production growth and copper expansion.
Southbound Trading Summary (Past 2 Weeks)
(HKD millions) | Ticker | Total Buy | Total Sell | Net Buy (Sell) | % of Total Turnover | Past 2-Week Return | Data |
Southbound Total | HSHKI.HK | 333,355 | 357,039 | (23,684) | 34% | -5.5% | Full |
TENCENT | 0700.HK | 26,400 | 23,739 | 2,662 | 26% | -9.1% | Full |
BABA-W | 9988.HK | 12,964 | 16,529 | (3,565) | 21% | -8.6% | Full |
SMIC | 0981.HK | 9,074 | 15,092 | (6,019) | 39% | -18.4% | Full |
CNOOC | 0883.HK | 11,314 | 12,000 | (686) | 57% | -3.3% | Partial |
XIAOMI-W | 1810.HK | 8,605 | 10,588 | (1,983) | 23% | 3.2% | Partial |
YOFC | 6869.HK | 8,263 | 10,639 | (2,376) | 42% | -33.3% | Partial |
Z.AI | 2513.HK | 8,225 | 7,432 | 794 | 37% | -22.2% | Partial |
KB LAMINATES | 1888.HK | 6,784 | 7,991 | (1,207) | 42% | -23.1% | Partial |
HUA HONG GRACE | 1347.HK | 1,864 | 3,336 | (1,472) | 29% | -28.7% | Partial |
WUXI BIO | 2269.HK | 1,653 | 3,213 | (1,560) | 29% | -14.9% | Partial |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026.
Note: Based on the two-week period from Oct 12 to Oct 23, 2026. For Stock Connect Southbound trading, only the top 10 most actively traded securities are disclosed. “Full data” means the stock appeared on the top 10 list for each of the past few trading days. “Partial data” means otherwise.
- Southbound outflows added to selling pressure during the correction. Mainland investors recorded HKD 23.68bn of net selling over Oct 12-23, making Southbound flows an additional headwind for Hong Kong equities.
- Mainland investors bought Tencent and Z.AI on weakness, but selling pressure remained heavy. Tencent attracted HKD 2.66bn of net buying but fell 9.1%, while Z.AI received HKD 0.79bn and dropped 22.2%. These purchases were insufficient to stabilize their share prices.
- Selling extended across Alibaba, semiconductor and hardware stocks. Alibaba recorded HKD 3.57bn of net selling, while SMIC saw HKD 6.02bn of outflows and fell 18.4%. YOFC, Kingboard Laminates and Hua Hong also recorded outflows alongside sharp declines. Xiaomi stood out with a 3.2% gain despite net selling, showing greater price resilience than other technology names facing Southbound outflows.
Stocks: Potential Movers and Shakers
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our China Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
CATL | Consumer Discretionary | Core Recommendation | Earnings | Negative |
- CATL’s 3Q 2026 net profit came in below estimates at RMB 21.25bn (+14.5% yoy/-5.8% qoq) due to increased share of lower-margin energy storage battery in revenue mix, tax hikes and inventory provision.
- Policy headwinds. China cut the VAT rebate on LIB exports from 9% to 6% on 1 Apr 2026, and began imposing a 2% consumption tax on LIBs on 1 Sep 2026. As such, CATL’s net profit per GWh dropped from RMB 104mn in 1Q 2026 to RMB 97mn/RMB 82mn in 2Q 2026/3Q 2026, as the company bore the tax hikes during the period. China's VAT rebate on the LIB exports will be cancelled by 1 Jan 27, and the consumption tax on LIBs will rise to 4% by 1 Sep 27.
- Unit profitability will largely depend on tax-sharing negotiations. Lithium carbonate prices fell 10% over the past week to below RMB 100,000/tonne, roughly half their mid-May peak of over RMB 200,000/tonne. Given the linkage between battery prices and costs, CATL’s net profit per GWh has historically remained at around RMB 100mn through lithium carbonate price cycles. Going forward, unit profitability will largely depend on negotiations with automakers over sharing the additional tax burden. Our earnings forecasts assume a 50:50 split between CATL and its customers.
- We maintain 2026-28 net profit forecasts at RMB 89.1bn/RMB 104.9bn/RMB 116.4bn respectively, based on sales volume of 1.00/1.23/1.45 TWh (+51%/23%/18% yoy) and per GWh net profit of RMB 89mn/85mn/80mn. Maintain BUY with the target prices of RMB 343/HKD 400 for A-share/H-share, pegged to 15x 2027F PE (1SD below historical mean). CATL remains our Core Recommendation. (Ken Lee)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Sands China (1928 HK) | Consumer Discretionary | No Recommendation | Earnings | Negative |
- Market share rose, but normalized EBITDA was flat qoq. Sands China posted 3Q 2026 adjusted property EBITDA of USD 529mn (+23% qoq, -12% yoy). Assuming a normalized VIP win rate, EBITDA would have been USD 518mn (flat qoq, -14% yoy), with margin at 27.0% (+0.3ppt qoq, -4.5ppt yoy), weighed by higher payroll and unfavourable premium-mass hold at The Londoner. Gross gaming revenue (GGR) rose 6% qoq and 3% yoy to USD1.9bn (vs the industry’s 1% qoq decline), recovering to 93% of 3Q19 levels. We estimate market share rose 1.8ppt qoq to 25.3%.
- Strong VIP luck offset weaker mass hold. VIP GGR rose 105% qoq and 41% yoy on a higher win rate of 3.6% (vs 1.4% in 2Q2026). Mass GGR was flat qoq but down 2% yoy, as steady volume and some super high-end premium-mass wins were offset by a lower hold rate of 20.4% (vs 23.1% in 3Q 2025), mainly at The Londoner. Slot GGR rose 18% yoy on volume growth.
- Premium softness seen as temporary, while mass share is at its highest since 4Q23. Management attributed softer premium demand to a mix of factors rather than any single driver, such as China’s offshore trust taxation, and sees underlying demand as solid. Strong mid-tier and base-mass growth at The Parisian and Sands Macao lifted mass revenue share to 26.1%.
- The Venetian’s renovation is due for completion by Chinese New Year 2028. Rooms out of inventory rose from about 400 in 3Q 2026 to about 500 in 4Q 2026, while about 600 renovated rooms have returned, with feedback above expectations and mass revenue improving qoq. Premium gaming salons will be added on completion.
- Maintain BUY; cut target price by 17% to HKD 16.90. We lower our 2026/27 EBITDA forecasts by 7%/6% and roll our valuation forward to 2027. We also reduce our target EV/EBITDA multiple from 12.0x to 10.0x to reflect a weaker-than-expected industry backdrop. (Stella Guo/Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Anta Sports (2020 HK) | Consumer Discretionary | No Recommendation | Earnings | Positive |
- Golden Week trading improved after weaker 3Q sales. The Anta brand recorded a mid-single-digit decline in 3Q 2026 retail sales, versus low-single-digit growth in 2Q 2026. Offline sales at Anta Core and Anta Kids fell by high single digits and low single digits, respectively, while online sales were broadly flat. Management attributed the weakness to softer consumption and extreme weather, which weighed on traffic and conversion. It will focus on shopping mall penetration, store operations and consolidating lower-tier street stores. Fila retail sales fell by low single digits, versus low-single-digit growth in 2Q 2026. Offline declines at Fila Core and Fila Kids were partly offset by mid-single-digit growth at Fila Fusion on a low base. Online sales grew by low single digits, supported by promotions for breathable shell jackets and China Open products.
- Management remains confident in full-year targets after a solid start to 4Q 2026. During the National Day Golden Week (Oct 1-7), retail sales rose by high single digits for the Anta brand, low teens for Fila and over 20% for other brands. For 9M26, the Anta brand, Fila and other brands recorded low-single-digit, mid-single-digit and over 30% retail sales growth respectively. With a softer backdrop already factored in and a disciplined Double 11 promotional strategy, management reiterated its full-year retail sales targets (low-single-digit growth for the Anta brand, mid single digits for Fila and over 20% for other brands) and operating margin targets of around 20% for the Anta brand (around 16% excluding government subsidies and tax rebates), around 25% for Fila and over 25% for other brands.
- Other brands maintained strong momentum, with Kolon targeting around 20% growth over the next few years. Other brands (excluding Jack Wolfskin) rose 25-30% in 3Q 2026, in line with 2Q 2026, with Descente, Kolon and Maia Active growing 15-20%, 30% and over 30% respectively. Kolon’s same-store sales rose more than 15%, and management will prioritise brand health by opening only 10-15 stores a year and keeping all-channel discounts within 10%.
- Puma’s initial focus is China, while Jack Wolfskin’s new stores are tracking in line. Following the completion of the Puma stake acquisition, two Anta nominees have joined Puma’s supervisory board. Management will initially focus on China, where Puma contributes only a small share of global revenue, which could potentially double over time. Jack Wolfskin’s new-image stores opened in Sept performed in line with expectations through the Mid-Autumn and National Day holidays.
- Maintain BUY with an unchanged target price of HKD 112.20. We maintain our earnings forecasts and roll our DCF-based valuation forward to 2027. Our target price implies 18.3x 2026F PE and 17.0x 2027F PE. (Stella Guo/Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
COLI CR Land Longfor | Real Estate | COLI: No Recommendation CR Land: No Recommendation Longfor: No Recommendation | Sales / Products | Neutral |
- New-home sales weakened further in September, while second-hand transactions remained stronger. New-home GFA sold fell 22.6% yoy, versus a 15.4% decline in August, marking the steepest monthly contraction in 2026. Sales value fell 21.1% yoy. Property investment fell 27.2% yoy and completions 36.7% yoy, while the decline in new starts narrowed to 26.1% from 30.5%. In 9M26, second-hand transaction GFA rose 10.7% yoy to 617.5m sqm, 1.3x the 470.0m sqm of residential new-home GFA sold. Tier 1 prices kept rising, with new-home and second-hand price indices up 0.1% and 0.2% mom in Sep 2026, while Tier 2 second-hand prices fell 0.2% mom. Household medium- to long-term loans increased by RMB 87.4bn in September, 65% less than the RMB 250.0bn increase a year earlier. We attribute September’s lending increase mainly to quarter-end seasonality.
- Tier 1 cities led high-frequency sales in Oct 2026, but listing prices kept falling. Over 1-25 Oct 2026, new-home sales rose 2% yoy in four Tier 1 cities and fell 23% in nine Tier 2 cities, while second-hand sales rose 22% yoy in three Tier 1 cities and fell 1% in eight Tier 2 cities. Momentum kept fading after the Golden Week, as Shanghai new-home sales turned negative at -7% yoy, joining Guangzhou and Shenzhen at -4% and -18%. The ICE index showed average second-hand listing prices in 100 major cities down 0.6% mom as of 25 Oct, with all four Tier 1 cities now recording declines after Shanghai turned negative.
- Maintain UNDERWEIGHT on China’s property sector, with COLI remaining our top pick. We expect the second-hand market to continue outperforming the primary market, as mortgage interest subsidies mainly benefit smaller units, which account for a larger share of second-hand transactions. Meanwhile, presale reforms are likely to delay new launches. Top picks remain COLI. (Liu Jieqi/ Damon Shen)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
SHKP | Real Estate | No Recommendation | Insider Dealing | Positive |
- The Kwok family keeps buying SHKP shares. SHKP’s controlling shareholder Kwong Siu-hing purchased 2.59mn shares for around HKD 277mn over ten trading days between Sep 11 and Oct 5, at an average price of around HKD 107.19. This lifted her stake from 28.13% to 28.22%. A trust of which director Adam Kwok is a beneficiary bought another 220,000 shares for around HKD 23mn on Oct 7, bringing total family purchases to 2.81mn shares, or around HKD 301mn. We view the purchases as a positive signal that the owners see value following the recent pullback.
- Development margins recovered and gearing declined. SHKP’s Hong Kong development margin rose to 14.8% in fiscal 2H26, from 7.6% in 1H26 and 8.7% in 2H25. Net gearing fell 4.4ppt yoy to 10.7% at end-June. The stock trades at 0.49x P/NAV and offers a 4.1% FY27 dividend yield.
- Maintain BUY with a target price of HKD 143.80. SHKP remains our top pick for its low gearing, exposure to the Hong Kong residential market and dividend yield. (Liu Jieqi/ Damon Shen)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Lead investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
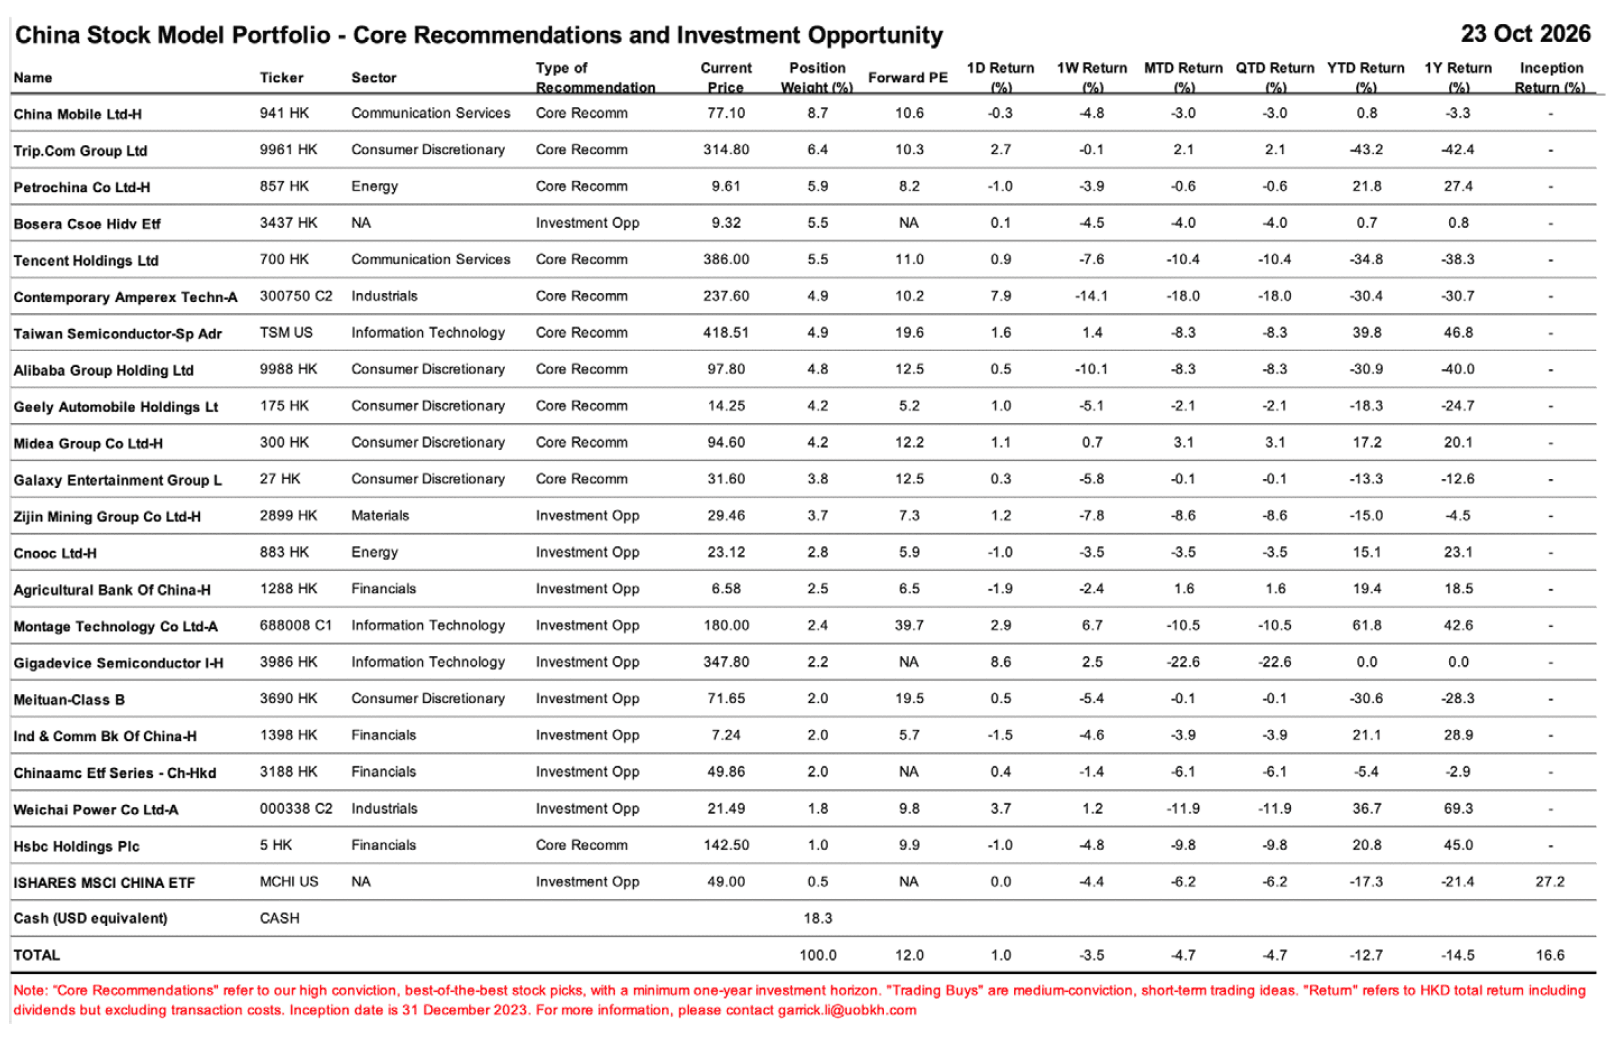
Appendix - China Stock Model Portfolio
Key China Market Indices
Index | Price | Past 2-Week Return | YTD Return |
Hang Seng Index | 23,093 | -4.6% | -9.9% |
HSCEI Index | 7,756 | -4.8% | -13.0% |
Hang Seng Tech Index | 3,872 | -7.8% | -29.8% |
Shanghai Composite Index | 3,690 | -3.2% | -7.0% |
CSI 300 Index | 4,105 | -4.9% | -11.3% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Stronger growth reduces stimulus urgency, but domestic demand remains weak. China’s 3Q 2026 GDP growth recovered to 4.5% yoy from 4.3% in 2Q 2026, supported by exports and industrial production. September retail sales improved to 1.1% yoy, partly reflecting holiday timing, while fixed asset investment contracted 7.2% in 9M26, weighed down by a 20.6% decline in property investment. The pickup in growth may reduce the urgency for a large new stimulus package, with policymakers likely to prioritise deploying existing support. Export strength supports growth, but household deleveraging continues to restrain consumption. The macro picture remains mixed.
- AI return concerns and fund outflows weigh on Hong Kong equities. The Hang Seng TECH Index fell 7.8% over the past two weeks, against a 4.6% decline in the Hang Seng Index. Investors are reassessing how quickly heavy AI spending can generate profitable revenue. Southbound investors recorded HKD 23.7bn of net selling, reducing an important source of demand for Hong Kong shares. Foreign fund outflows and elevated US yields add to this pressure. Separately, offshore trust tax enforcement may prompt affected investors to raise cash through share sales, adding potential selling pressure.
- 3Q reporting season brings earnings risks into focus. Earnings delivery is the next test after the sell-off. CATL and China Mobile have already reported 3Q 2026 results below expectations. For upcoming internet results, rising AI costs could limit profit growth even as revenues improve, while heavy capital spending may keep free cash flow under pressure. These pressures leave room for further earnings revisions as results are released, even after the sharp correction in share prices.
- A technical rebound would not yet confirm a sustained recovery. The sharp correction leaves room for a short-term bounce, particularly if policy support helps stabilize sentiment. However, a price rebound alone would not resolve earnings uncertainty or reverse fund outflows. We remain cautious on the indices, with a sustained recovery requiring stronger profits and more supportive fund flows. High-dividend, cash-rich defensive stocks may outperform the broader market in the near term, while selective long-term growth opportunities remain attractive. Tencent (0700.HK) remains our Core Recommendation as a leading AI practitioner with increasingly attractive long-term investment opportunities at current valuations (12x forward PE).
- Best-performing sectors: Utilities -1.7% (e.g. 1816.HK, 1038.HK); Consumer Staples -1.8% (e.g. 2319.HK, 6055.HK); Real Estate -2.4% (e.g. 0823.HK, 0083.HK).
- Potential movers and shakers: Details inside.
Positive | Anta Sports (2020 HK), SHKP (0016 HK) |
Neutral | COLI (0688 HK), CR Land (1109 HK), Longfor (0960 HK) |
Negative | CATL (300750 CH/3750 HK), Sands China (1928 HK) |
- Must Watch Events: Details below.
Date | Macro Data | Sector / Company Events |
Oct 26-29 | CPC Fifth Plenum: policy and implementation signals |
|
Oct 27 | China September industrial profits | HSBC (0005.HK) |
Oct 28 | US FOMC decision (US date; Oct 29 HKT): USD/HKD funding costs | PetroChina (0857.HK), Ping An (2318.HK) |
Oct 29 | US 3Q GDP and September PCE inflation: rates and China export demand | Midea (0300.HK) |
Oct 30 |
| ABC (1288.HK), ICBC (1398.HK), CCB (0939.HK), BOC (3988.HK), CNOOC (0883.HK) |
Oct 31 | China October official manufacturing and non-manufacturing PMIs |
|
Oct 31-Nov 4 |
| Canton Fair Phase 3: export orders and buyer demand |
Nov 2 / 4 | China October RatingDog manufacturing / services PMIs |
|
Nov 5-10 |
| China International Import Expo opens Nov 5: consumption and trade signals |
Best 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Utilities | -1.7% | -1.7% | Cgn Power Co.,Ltd. (1816.HK) +2.3%, Ck Infrastructure Holdings Limited (1038.HK) +1.7%, China Everbright Environment Group Limited (0257.HK) +3.4% |
Consumer Staples | -1.8% | -18.4% | China Mengniu Dairy Company Limited (2319.HK) +2.1%, China Tobacco International (Hk) Company Limited (6055.HK) +12.9%, Yihai International Holding Ltd. (1579.HK) +6.7% |
Real Estate | -2.4% | -3.8% | Link Asset Management Limited (00823.HK) +1.9%, Sino Land Company Limited (0083.HK) +2.1%, Anhui Conch Cement Company Limited (0914.HK) +3.7% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Utilities fell 1.7% over two weeks, leaving the YTD decline at 1.7%. CGN Power and CK Infrastructure gained during the broader sell-off. CGN Power’s new generating capacity supports earnings growth, while potential tariff improvement in 2027 offers a further catalyst beyond its defensive appeal.
- Consumer Staples fell 1.8% over two weeks, extending the YTD decline to 18.4%. Mengniu and Yihai gained. Easing dairy competition could support Mengniu’s margin recovery, providing a company-specific catalyst despite subdued household demand.
- Real Estate fell 2.4% over two weeks, taking the YTD decline to 3.8%. Link REIT and Sino Land gained despite continued weakness in mainland property. Mainland property investment fell 20.6% in 9M26, underscoring the need for stronger policy support to revive the housing market.
Worst 3 Hang Seng Sectors (Past 2 Weeks)
Hang Seng Sector Index | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
Information Technology | -10.0% | -32.1% | Tencent Holdings Ltd. (0700.HK) -9.1%, Semiconductor Manufacturing International Corporation (0981.HK) -18.4%, Lenovo Group Limited (0992.HK) -31.1% |
Industrials | -10.7% | -7.4% | Contemporary Amperex Technology Co., Limited (3750.HK) -27.4%, Kingboard Laminates Holdings Ltd. (1888.HK) -23.1%, Weichai Power Co.,Ltd. (2338.HK) -12.1% |
Materials | -12.6% | -27.2% | Zijin Mining Group Company Limited (2899.HK) -10.6%, Cmoc Group Limited (3993.HK) -15.6%, China Hongqiao Group Limited (1378.HK) -10% |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026
- Information Technology fell 10.0% over two weeks, extending its YTD decline to 32.1%. Lenovo and SMIC declined sharply during the AI-related sell-off, despite continued structural support from AI infrastructure investment and semiconductor localization. For PC makers such as Lenovo, higher memory and CPU costs add pressure on profitability.
- Industrials fell 10.7% over two weeks, taking the YTD decline to 7.4%. CATL’s 3Q gross margin fell 2.5ppt qoq to 20.7%. Management attributed the decline to product mix and tax-related costs. Tax-sharing negotiations with customers remain ongoing, adding uncertainty to near-term margin recovery. However, domestic EV battery market share rose to 44.2% in Jan-Sep from 42.8% a year earlier, while its share outside China increased to 33.7% in Jan-Aug from 29.0%. These gains reinforce our China Export Shock 2.0 thesis. CATL remains our Core Recommendation, supported by its technology leadership and global expansion.
- Materials was the weakest sector, down 12.6% over two weeks and 27.2% YTD. Zijin Mining’s third-quarter net profit attributable to shareholders rose 26.0% yoy to RMB 18.4bn, but declined sequentially as lower realized gold prices and higher mining costs weighed on earnings. Stronger copper performance partly offset these pressures. In 3Q 2026, operating cash flow of RMB28.8bn comfortably covered approximately RMB6.0bn of cash capital expenditure, supporting future mine development and production growth. However, costs, project execution and acquisition spending will influence how much of this growth translates into shareholder returns. We continue to see a role for gold in portfolio diversification amid de-dollarization, geopolitical and monetary uncertainty. Zijin remains an Investment Opportunity, offering gold exposure alongside production growth and copper expansion.
Southbound Trading Summary (Past 2 Weeks)
(HKD millions) | Ticker | Total Buy | Total Sell | Net Buy (Sell) | % of Total Turnover | Past 2-Week Return | Data |
Southbound Total | HSHKI.HK | 333,355 | 357,039 | (23,684) | 34% | -5.5% | Full |
TENCENT | 0700.HK | 26,400 | 23,739 | 2,662 | 26% | -9.1% | Full |
BABA-W | 9988.HK | 12,964 | 16,529 | (3,565) | 21% | -8.6% | Full |
SMIC | 0981.HK | 9,074 | 15,092 | (6,019) | 39% | -18.4% | Full |
CNOOC | 0883.HK | 11,314 | 12,000 | (686) | 57% | -3.3% | Partial |
XIAOMI-W | 1810.HK | 8,605 | 10,588 | (1,983) | 23% | 3.2% | Partial |
YOFC | 6869.HK | 8,263 | 10,639 | (2,376) | 42% | -33.3% | Partial |
Z.AI | 2513.HK | 8,225 | 7,432 | 794 | 37% | -22.2% | Partial |
KB LAMINATES | 1888.HK | 6,784 | 7,991 | (1,207) | 42% | -23.1% | Partial |
HUA HONG GRACE | 1347.HK | 1,864 | 3,336 | (1,472) | 29% | -28.7% | Partial |
WUXI BIO | 2269.HK | 1,653 | 3,213 | (1,560) | 29% | -14.9% | Partial |
Source: UOB Kay Hian and iFinD, as of Oct 23, 2026.
Note: Based on the two-week period from Oct 12 to Oct 23, 2026. For Stock Connect Southbound trading, only the top 10 most actively traded securities are disclosed. “Full data” means the stock appeared on the top 10 list for each of the past few trading days. “Partial data” means otherwise.
- Southbound outflows added to selling pressure during the correction. Mainland investors recorded HKD 23.68bn of net selling over Oct 12-23, making Southbound flows an additional headwind for Hong Kong equities.
- Mainland investors bought Tencent and Z.AI on weakness, but selling pressure remained heavy. Tencent attracted HKD 2.66bn of net buying but fell 9.1%, while Z.AI received HKD 0.79bn and dropped 22.2%. These purchases were insufficient to stabilize their share prices.
- Selling extended across Alibaba, semiconductor and hardware stocks. Alibaba recorded HKD 3.57bn of net selling, while SMIC saw HKD 6.02bn of outflows and fell 18.4%. YOFC, Kingboard Laminates and Hua Hong also recorded outflows alongside sharp declines. Xiaomi stood out with a 3.2% gain despite net selling, showing greater price resilience than other technology names facing Southbound outflows.
Stocks: Potential Movers and Shakers
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our China Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
CATL | Consumer Discretionary | Core Recommendation | Earnings | Negative |
- CATL’s 3Q 2026 net profit came in below estimates at RMB 21.25bn (+14.5% yoy/-5.8% qoq) due to increased share of lower-margin energy storage battery in revenue mix, tax hikes and inventory provision.
- Policy headwinds. China cut the VAT rebate on LIB exports from 9% to 6% on 1 Apr 2026, and began imposing a 2% consumption tax on LIBs on 1 Sep 2026. As such, CATL’s net profit per GWh dropped from RMB 104mn in 1Q 2026 to RMB 97mn/RMB 82mn in 2Q 2026/3Q 2026, as the company bore the tax hikes during the period. China's VAT rebate on the LIB exports will be cancelled by 1 Jan 27, and the consumption tax on LIBs will rise to 4% by 1 Sep 27.
- Unit profitability will largely depend on tax-sharing negotiations. Lithium carbonate prices fell 10% over the past week to below RMB 100,000/tonne, roughly half their mid-May peak of over RMB 200,000/tonne. Given the linkage between battery prices and costs, CATL’s net profit per GWh has historically remained at around RMB 100mn through lithium carbonate price cycles. Going forward, unit profitability will largely depend on negotiations with automakers over sharing the additional tax burden. Our earnings forecasts assume a 50:50 split between CATL and its customers.
- We maintain 2026-28 net profit forecasts at RMB 89.1bn/RMB 104.9bn/RMB 116.4bn respectively, based on sales volume of 1.00/1.23/1.45 TWh (+51%/23%/18% yoy) and per GWh net profit of RMB 89mn/85mn/80mn. Maintain BUY with the target prices of RMB 343/HKD 400 for A-share/H-share, pegged to 15x 2027F PE (1SD below historical mean). CATL remains our Core Recommendation. (Ken Lee)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Sands China (1928 HK) | Consumer Discretionary | No Recommendation | Earnings | Negative |
- Market share rose, but normalized EBITDA was flat qoq. Sands China posted 3Q 2026 adjusted property EBITDA of USD 529mn (+23% qoq, -12% yoy). Assuming a normalized VIP win rate, EBITDA would have been USD 518mn (flat qoq, -14% yoy), with margin at 27.0% (+0.3ppt qoq, -4.5ppt yoy), weighed by higher payroll and unfavourable premium-mass hold at The Londoner. Gross gaming revenue (GGR) rose 6% qoq and 3% yoy to USD1.9bn (vs the industry’s 1% qoq decline), recovering to 93% of 3Q19 levels. We estimate market share rose 1.8ppt qoq to 25.3%.
- Strong VIP luck offset weaker mass hold. VIP GGR rose 105% qoq and 41% yoy on a higher win rate of 3.6% (vs 1.4% in 2Q2026). Mass GGR was flat qoq but down 2% yoy, as steady volume and some super high-end premium-mass wins were offset by a lower hold rate of 20.4% (vs 23.1% in 3Q 2025), mainly at The Londoner. Slot GGR rose 18% yoy on volume growth.
- Premium softness seen as temporary, while mass share is at its highest since 4Q23. Management attributed softer premium demand to a mix of factors rather than any single driver, such as China’s offshore trust taxation, and sees underlying demand as solid. Strong mid-tier and base-mass growth at The Parisian and Sands Macao lifted mass revenue share to 26.1%.
- The Venetian’s renovation is due for completion by Chinese New Year 2028. Rooms out of inventory rose from about 400 in 3Q 2026 to about 500 in 4Q 2026, while about 600 renovated rooms have returned, with feedback above expectations and mass revenue improving qoq. Premium gaming salons will be added on completion.
- Maintain BUY; cut target price by 17% to HKD 16.90. We lower our 2026/27 EBITDA forecasts by 7%/6% and roll our valuation forward to 2027. We also reduce our target EV/EBITDA multiple from 12.0x to 10.0x to reflect a weaker-than-expected industry backdrop. (Stella Guo/Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Anta Sports (2020 HK) | Consumer Discretionary | No Recommendation | Earnings | Positive |
- Golden Week trading improved after weaker 3Q sales. The Anta brand recorded a mid-single-digit decline in 3Q 2026 retail sales, versus low-single-digit growth in 2Q 2026. Offline sales at Anta Core and Anta Kids fell by high single digits and low single digits, respectively, while online sales were broadly flat. Management attributed the weakness to softer consumption and extreme weather, which weighed on traffic and conversion. It will focus on shopping mall penetration, store operations and consolidating lower-tier street stores. Fila retail sales fell by low single digits, versus low-single-digit growth in 2Q 2026. Offline declines at Fila Core and Fila Kids were partly offset by mid-single-digit growth at Fila Fusion on a low base. Online sales grew by low single digits, supported by promotions for breathable shell jackets and China Open products.
- Management remains confident in full-year targets after a solid start to 4Q 2026. During the National Day Golden Week (Oct 1-7), retail sales rose by high single digits for the Anta brand, low teens for Fila and over 20% for other brands. For 9M26, the Anta brand, Fila and other brands recorded low-single-digit, mid-single-digit and over 30% retail sales growth respectively. With a softer backdrop already factored in and a disciplined Double 11 promotional strategy, management reiterated its full-year retail sales targets (low-single-digit growth for the Anta brand, mid single digits for Fila and over 20% for other brands) and operating margin targets of around 20% for the Anta brand (around 16% excluding government subsidies and tax rebates), around 25% for Fila and over 25% for other brands.
- Other brands maintained strong momentum, with Kolon targeting around 20% growth over the next few years. Other brands (excluding Jack Wolfskin) rose 25-30% in 3Q 2026, in line with 2Q 2026, with Descente, Kolon and Maia Active growing 15-20%, 30% and over 30% respectively. Kolon’s same-store sales rose more than 15%, and management will prioritise brand health by opening only 10-15 stores a year and keeping all-channel discounts within 10%.
- Puma’s initial focus is China, while Jack Wolfskin’s new stores are tracking in line. Following the completion of the Puma stake acquisition, two Anta nominees have joined Puma’s supervisory board. Management will initially focus on China, where Puma contributes only a small share of global revenue, which could potentially double over time. Jack Wolfskin’s new-image stores opened in Sept performed in line with expectations through the Mid-Autumn and National Day holidays.
- Maintain BUY with an unchanged target price of HKD 112.20. We maintain our earnings forecasts and roll our DCF-based valuation forward to 2027. Our target price implies 18.3x 2026F PE and 17.0x 2027F PE. (Stella Guo/Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
COLI CR Land Longfor | Real Estate | COLI: No Recommendation CR Land: No Recommendation Longfor: No Recommendation | Sales / Products | Neutral |
- New-home sales weakened further in September, while second-hand transactions remained stronger. New-home GFA sold fell 22.6% yoy, versus a 15.4% decline in August, marking the steepest monthly contraction in 2026. Sales value fell 21.1% yoy. Property investment fell 27.2% yoy and completions 36.7% yoy, while the decline in new starts narrowed to 26.1% from 30.5%. In 9M26, second-hand transaction GFA rose 10.7% yoy to 617.5m sqm, 1.3x the 470.0m sqm of residential new-home GFA sold. Tier 1 prices kept rising, with new-home and second-hand price indices up 0.1% and 0.2% mom in Sep 2026, while Tier 2 second-hand prices fell 0.2% mom. Household medium- to long-term loans increased by RMB 87.4bn in September, 65% less than the RMB 250.0bn increase a year earlier. We attribute September’s lending increase mainly to quarter-end seasonality.
- Tier 1 cities led high-frequency sales in Oct 2026, but listing prices kept falling. Over 1-25 Oct 2026, new-home sales rose 2% yoy in four Tier 1 cities and fell 23% in nine Tier 2 cities, while second-hand sales rose 22% yoy in three Tier 1 cities and fell 1% in eight Tier 2 cities. Momentum kept fading after the Golden Week, as Shanghai new-home sales turned negative at -7% yoy, joining Guangzhou and Shenzhen at -4% and -18%. The ICE index showed average second-hand listing prices in 100 major cities down 0.6% mom as of 25 Oct, with all four Tier 1 cities now recording declines after Shanghai turned negative.
- Maintain UNDERWEIGHT on China’s property sector, with COLI remaining our top pick. We expect the second-hand market to continue outperforming the primary market, as mortgage interest subsidies mainly benefit smaller units, which account for a larger share of second-hand transactions. Meanwhile, presale reforms are likely to delay new launches. Top picks remain COLI. (Liu Jieqi/ Damon Shen)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
SHKP | Real Estate | No Recommendation | Insider Dealing | Positive |
- The Kwok family keeps buying SHKP shares. SHKP’s controlling shareholder Kwong Siu-hing purchased 2.59mn shares for around HKD 277mn over ten trading days between Sep 11 and Oct 5, at an average price of around HKD 107.19. This lifted her stake from 28.13% to 28.22%. A trust of which director Adam Kwok is a beneficiary bought another 220,000 shares for around HKD 23mn on Oct 7, bringing total family purchases to 2.81mn shares, or around HKD 301mn. We view the purchases as a positive signal that the owners see value following the recent pullback.
- Development margins recovered and gearing declined. SHKP’s Hong Kong development margin rose to 14.8% in fiscal 2H26, from 7.6% in 1H26 and 8.7% in 2H25. Net gearing fell 4.4ppt yoy to 10.7% at end-June. The stock trades at 0.49x P/NAV and offers a 4.1% FY27 dividend yield.
- Maintain BUY with a target price of HKD 143.80. SHKP remains our top pick for its low gearing, exposure to the Hong Kong residential market and dividend yield. (Liu Jieqi/ Damon Shen)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Lead investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
Appendix - China Stock Model Portfolio
Analyst
Elena Chen
elena.chen@uobkh.comAnalyst
Qi Wang, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


